


EU unveils tighter steel import quotas, new allocation structure
According to a document published in the Official Journal of the EU, seen by Fastmarkets, the new framework will include the expected significant reductions in tariff-free volumes to 18.3 million tonnes.
But it will also introduce a two-tier quota system under which one part will be available only to countries benefiting from an existing or future free-trade agreement with the EU (the FTA Part), while the other part will be available to all third countries on a Most Favoured Nation (MFN) basis (the MFN Part).
MFN quotas were allocated according to each country’s average share of EU imports in each product category during 2022-24. This distinguished many more countries with allocated country-specific quotas compared with the previous safeguard.
For the FTA part, quotas were allocated more flexibly, considering trade agreements, market distortions and the need to diversify supply, as well as special situations affecting certain countries.
As a result, some FTA partners received different levels of access. In particular, Ukraine was given more favorable quotas than other FTA countries.
Both the MFN and the FTA parts of the country-specific quota were accessible simultaneously to economic operators, functioning as a single quota with a single order number.
When a country does not belong to the pool of countries with FTA, economic operators can only access the MFN Part of the country-specific quota.
The regulation also introduced a change to residual quotas, which open at the start of each quarter. Instead of a single residual quota available to “Other countries,” the new system will split residual volumes into “FTA quota – Country-Specific Quota (CSQ),” “FTA Quota – Other countries” and “Other Countries.”
FTA Quota – CSQ will be open to countries with an existing or future free-trade agreement with the EU that have a country-specific quota.
FTA Quota – Other countries will be open to countries with an existing or future free-trade agreement with the EU that do not have a country-specific quota.
This gives FTA countries greater flexibility, and will potentially delay exposure to the 50% tariff compared with non-FTA suppliers, according to the regulation.
The other countries residual quota will be open to all countries except those listed in Section 3 of Annex II of the regulation.
All residual quotas distributed under this regulation will be administered on a first-come, first-served basis.
Any volumes imported outside these quotas will be subject to a 50% tariff.
The measures were intended to protect the bloc’s steel industry from global overcapacity and unfair trade practices.
In 2025, a growing share of the EU’s steel demand was being met by external suppliers rather than domestic producers, prompting the use of tighter trade measures.
EU crude steel production declined by 2.9% year on year in 2025 to 125.8 million tonnes, down from 129.6 million tonnes in 2024. This was the lowest level on record and was around 60 million tonnes below the figures seen before the 2008 global financial crisis, according to European steel industry association EUROFER.
Meanwhile, apparent steel consumption in Europe increased by 4.5% year on year in 2025 to around 130 million tonnes, the first rise after three consecutive years of decline. But this improvement was overshadowed by a sharp surge in imports, particularly in the final quarter, when inbound volumes jumped by more than 50% quarter on quarter.
Import volumes of semi-finished and finished steel products in Europe rose by 14% year on year in 2025, to 40 million tonnes, according EUROFER.
Initial market reaction
The market was digesting the news, with quota cuts for some origins viewed as being extremely punitive.
For instance, allocation of the hot-rolled coil quota (Category 1A) for Turkey, which was traditionally one of the key suppliers of this product to Europe, was reduced by 60% to 642.249 tonnes, versus 1.59 million tonnes under the previous safeguard.
Another trading source said that the regulation was less of protection mechanism and more of a deal to create more complication and to add bureaucratic barriers for business, adding that the current quota distribution would make it “very tough” for new origins to enter the market.
Despite this, he expected no drastic price changes in the European domestic market in the near term, due to the limited demand and spending caused by the caution related to the unstable political situation in the world as well as to the seasonal summer slowdown.
None of the HRC suppliers contacted by Fastmarkets’ on June 30 reported any immediate price rises.
Fastmarkets’ daily steel hot-rolled coil index, domestic, exw Northern Europe, was calculated at €683.13 ($779.92) per tonne on June 30, up by €1.88 per tonne from €681.25 per tonne on June 29.
The index was down by €3.12 per tonne week on week and by €7.79 per tonne month on month.
A source from Ukraine expressed concern that the country was not exempted from the new safeguard in the way it was under the previous regulation, and was now subject to both safeguarding and the EU’s Carbon Border Adjustment Mechanism (CBAM), despite the difficult economic conditions it was facing because of the Russian invasion.


European Commission confirms steel quota allocations, FTA preference
The European Commission has published country quota allocations for the Steel Regulation that will replace the safeguard measure from 1 July. Half of the 18.3 million-tonne annual quota has been allocated exclusively to free trade agreement partners, with the other half accessible for all countries, including FTA partners, Kallanish notes.
FTA partners will therefore retain a higher share of EU market access than the average quota volume reduction of 47%. A significant number of partners have provisionally agreed to their allocated quotas following negotiations, the Commission says. However, it adds it will continue engaging with trading partners at the WTO under the ongoing Article XXVII GATT negotiations.
Because the regulation is being adopted by urgency procedure, it is initially valid until end-2026. Member States will be asked to vote within 14 days after the regulation’s adoption by the College of Commissioners.
The regulation will then be re-submitted to the relevant Member State committee under the normal comitology procedure before the end of 2026.
Quotas incorporate two parts – those available to all third countries on a Most Favoured Nation (MFN) basis, and those available only to countries benefiting from an existing or future free trade agreement with the EU.
In addition, when a country-specific quota opened for a country having an existing or future free trade agreement with the Union is exhausted, operators from that country should be allowed access to an additional tariff quota – FTA Quota – Country-Specific Quota (CSQ). This quota is accessible on a first-come, first-served basis.
Whenever a country does not have a country-specific quota in a certain product category, that country should have access only to a residual, “other countries” quota. The residual quota is also split into two parts: a residual MFN Part and a residual FTA Part.
In view of the specificity of product category 1A – hot rolled coil – which amounts to nearly one third of total quota volumes, the Commission considers it necessary to guarantee specific quotas to certain trading partners under both the MFN Part of the residual quota and FTA Quota – Other countries.
The Commission says it also identified a serious risk of crowding out of certain origins leading to reduced sources of supply that would negatively impact effective market access for several FTA partners, also impacting their Union customers.
Turkey, for example, has been allocated a 642,295-tonne annual quota for category 1A – hot rolled coil. This is split into a 321,749t MFN quota and 320,546t FTA quota. This means Turkey receives a quarterly quota of 160,574t, valid through June 2027. India’s annual quota is 597,274t, equating to 149,319t quarterly.
The FTA quota CSQ is 120,921t per quarter.
The other countries (MFN residual) quota is 5,564t per quarter. The FTA quota – other countries (residual) quota is 4,272t per quarter.
Other large quota allocations include Vietnam’s 469,988t annual quota for Category 4A Metallic Coated Sheets and South Korea’s 442,795t for Category 4B Metallic Coated Sheets.
In a Q&A issued regarding the regulation, the Commission poses the question of whether partners will retaliate against the new measure. “Ultimately, the only way to avoid this proliferation of unilateral measures is to address the root of overcapacity collectively,” it answers.
EU trade commissioner Maroš Šefčovič says: “We are providing market participants with predictability through clear and transparent quota distribution rules, while applying a fair and objective methodology. The approach strikes a careful balance between our FTA commitments, the Article XXVIII negotiations in the WTO and the need to maintain diversified supply. The constructive progress made with our trading partners also shows that the EU’s WTO-compliant approach is effective in practice.”

Europe’s green steel shift needs $400bn: Bloomberg
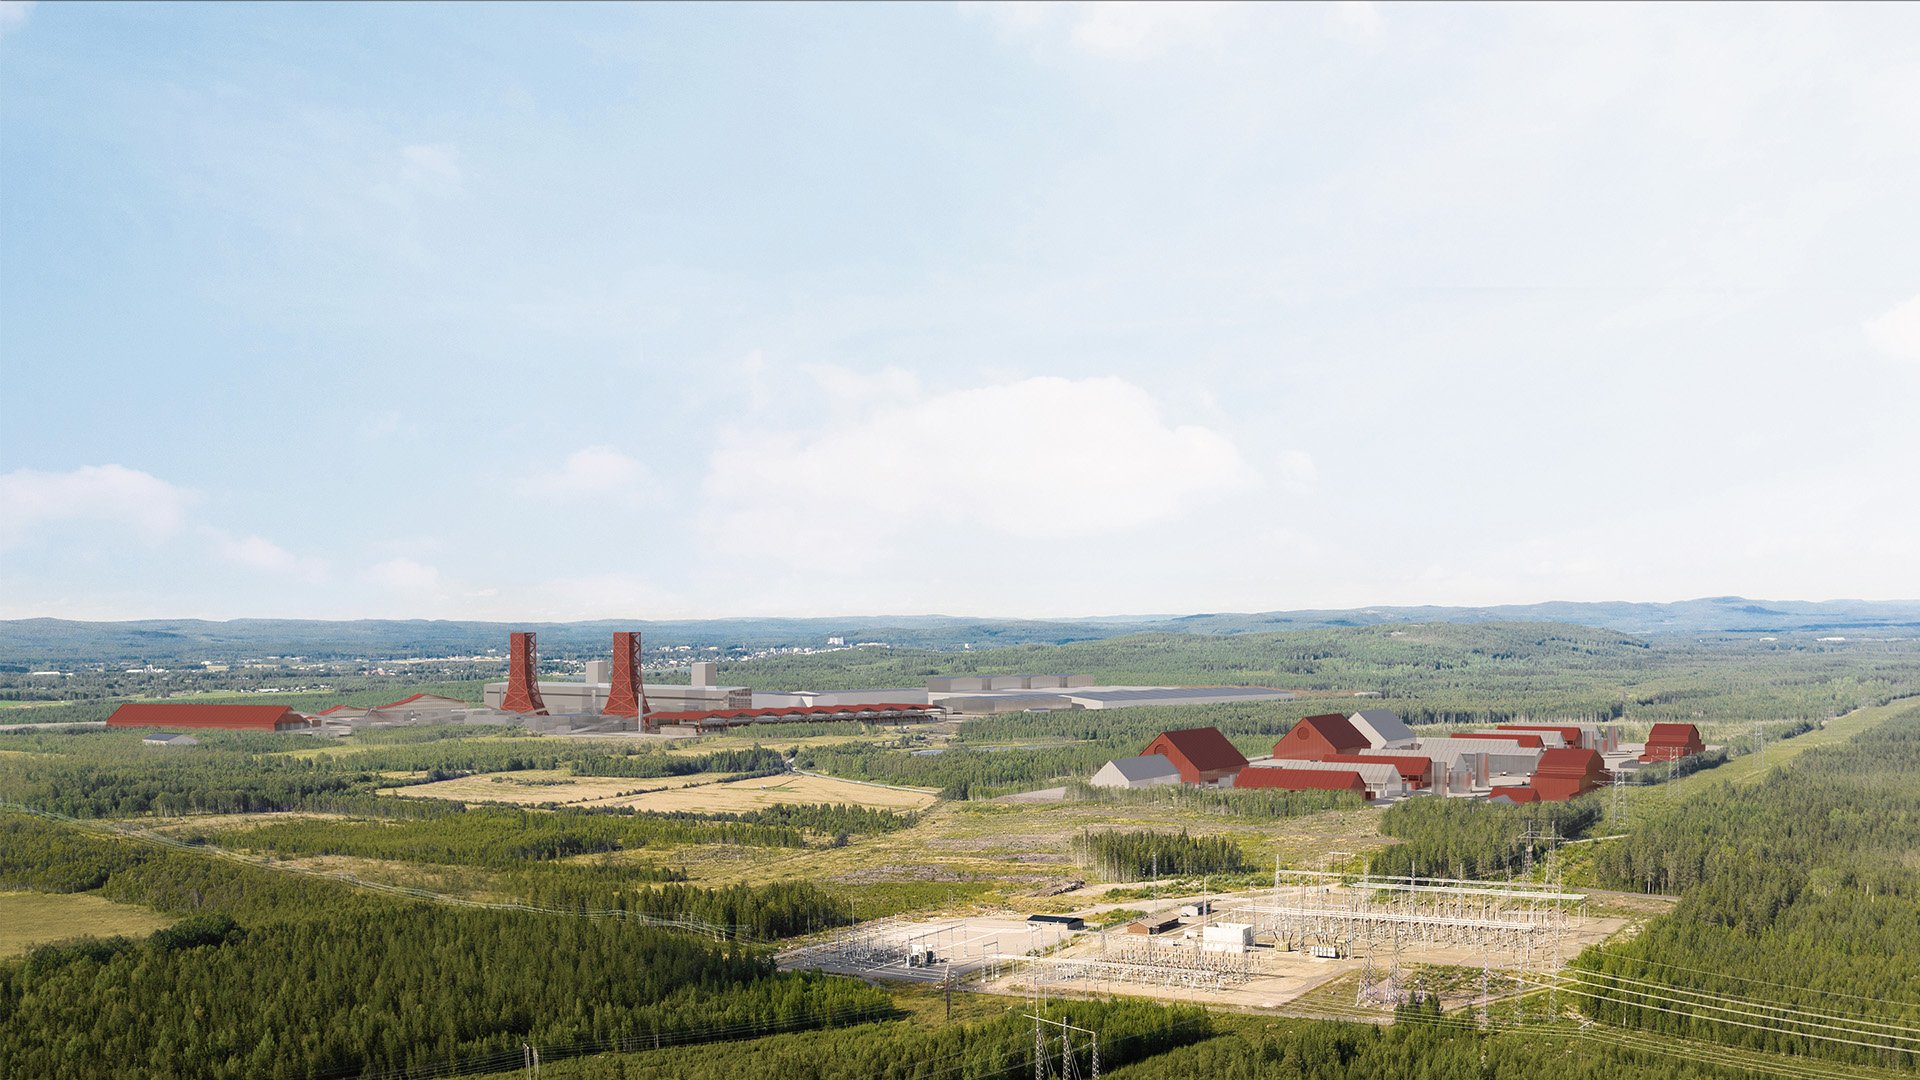
Shifting from coal-based blast furnace-basic oxygen furnace (BF-BOF) to electric arc furnace (EAF) steelmaking in Europe could cost $400 billion, Bloomberg Intelligence analysts say in a note seen by Kallanish.
Steelmakers are expected to shoulder about $90 billion in direct furnace conversion costs, while clean power, hydrogen electrolysers, and associated transport and storage account for the rest. Around 190 to 300 terawatt-hours (TWh) of carbon-free electricity might be required for a complete transition, compared with 75 TWh today. Factoring in renewable capital spending costs of $691-2,852/kilowatt, this may translate to a potential $126 billion for new generation capacity. Steel’s share of the hydrogen infrastructure and grid firming could add another $200 billion, Bloomberg estimates.
For Europe, its steel resilience depends on this “costly shift”, the analysts highlight. A large part of EU steelmakers’ iron ore and coal needs – essential for the over 55% of EU steel made through the BF-BOF route – is met through imports. Switching to EAFs, which melt scrap and/or direct reduced iron (DRI) using electricity, can lower the bloc’s import reliance.
“For Europe, green steel is a route to supply chain resilience and competitiveness, not just lower emissions,” they add.
However, the sector’s transition to a more resilient green steel model hinges on major policy changes. Europe needs to secure the input base, with scrap treated as a strategic feedstock; lower clean energy costs; protect the investment case from unfair imports; and create low-carbon steel demand through green public procurement.
“The optimal European steel model is circular first, EAF-led, enabled by direct reduced iron, power-competitive and trade-protected,” Bloomberg says. However, EAF conversion, while technically feasible, is hindered by power prices, grid capacity, DRI availability, and weak margins. In the case of hydrogen, while essential for deep decarbonisation, “Europe should not assume full upstream self-sufficiency.”
“The realistic end state is hybrid: domestic EAFs using high-quality scrap, hydrogen clusters where economics work and selective green hot briquetted iron imports, protected by the EU carbon border tax and trade defences,” the analysts conclude.

ISTA expresses concern over final import quota numbers
The UK’s International Steel Trade Association (ISTA) has expressed concern over the incoming tariff rate quotas (TRQ) for imports of steel into the nation, Kallanish learns from a statement.
ISTA says that while it is appreciative of the actions taken in relation to the transitional agreement following feedback, it is “very disappointed” with the size of TRQs and country splits.
“There has been very limited movement against ISTA requests with most at UK Steel’s behest,” the association says.
It notes an increase in Category 1, HRC, and a small reduction in the galvanized volumes from the European Union, which has not been fully utilised. It highlights a small increase in Category 4 for South Korea, and some changes for long products in Categories 12, 17 and 26, which have risen while Category 28 has declined.
ISTA says it remains concerned that whilst some HS codes have been removed, others have been added along with a number of new categories.
“Whilst we support UK steel manufacture, the UK mills are ill prepared to service the market both in terms of what the end users need and when, and financially in terms of the provision of usual credit payment terms,” the statement continues.
As such, steel shortages and a flight to products made from steel manufactured overseas could occur.
“The measures still include products which are not manufactured in the UK partly due to all the encompassing HS codes,” ISTA adds.
The association will continue to engage with the Department for Business and Trade and ministers on these issues and push for a review of the measures at the latest, in six months.
“This is not a good day for the industry that they passionately believe in,” ISTA concludes.
One trader tells Kallanish that the new quotas are “a lot more workable” in some categories, while others remain too restricted. However, he points to risks of oversupply in the near-term.
“People have stocked up based on the provisional quotas,” the trader says. “It’s made everyone panic so much and buy so heavily, resulting in high stocks. Now the quotas have been relaxed, there’s going to be more availability in addition to the transitional agreement.”
Another source says the quotas are “a shock to the market, people will have to reshape their business models”.
Another says it is “too early to say” what the impact of the quotas will be on supply and prices.
In an online post, USP Steel says that UK steel supply is to tighten significantly from the reductions in quotas. USP expects steel prices to increase by 30-35% during the second half of the year, and by 50% in worst cases, depending on the origin.
“We can’t see the EU numbers so we can’t judge if we’ve had a raw deal,” another source says.

Green steel appears viable with production-cost limits: study
German steel companies can hold their own against international competition with environmentally friendly steel, if the costs for crude steel can be kept below €600/tonne ($685/t). But this strongly depends on political measures to provide the framework conditions, Kallanish learns from a new study.
The study, commissioned by foundation Hans-Böckler-Stiftung, and carried out by the University of Mannheim, finds that the transition will only succeed if the industrial policy framework is right for the transition’s critical phase.
This requires, amongst other things, a long-term cap on industrial electricity and hydrogen prices. On European level, it would need a ‘Buy European’ rule in public procurement and safeguards against steel being sold at rock-bottom prices “as a result of environmental and social dumping and subsidies”.
Without a functional steel sector, the German economy along the value chain will lose up to €50 billion in value-added revenue a year, the authors have calculated.
“It is like with computer chips, antibiotics, and chemicals: we cannot do without steel, and if we do, we will see a bad surprise,” the study notes.
In terms of prices, they propose a guaranteed electricity price of €60/megawatt-hour (MWh), including grid charges and all levies, and for green hydrogen, a guaranteed purchase price of €140/MWh until 2035.
Under these conditions, they calculate that the costs of crude steel on the DRI route would come to €590/t. In view of an average market price for hot-rolled coil of €640/t over the past three years, that cost level is economically viable, according to the study. On the electric-arc furnace route, scrap-based crude steel would cost €464/t, which is viable as well, the authors note.
North Rhine-Westphalian production falls 20% in a decade
Germany’s strongest state for steel production and processing, North Rhine-Westphalia, has lost roughly 20% of its output over the past decade according to the state’s statistics office.
In 2025, the tonnage of crude steel and steel products amounted to 45.8 million tonnes, down by 20.1% from 2015 levels, and also 6.4% below the figure of 2024. The statistics counts crude steel along with semi-finished products, rolled products, and also finished products made by fabricators. The figure of 45.8mt therefore includes multiple instances of double counting along the value chain, the office explains.
The NRW statistics methods differ from those used for the national statistics by association WV Stahl, which clearly differentiates between crude steel, pig iron, and rolled products.
Sources at WV Stahl confirmed to Kallanish that the 20% drop over a ten-year period is plausible.
NRW statistics also reports an average selling value of €786/tonne ($896/t) in 2025, 46.5% higher than in 2015, but 4.7% below the value of 2024.
While these figures are not broken down by product group, they roughly correspond with published prices by Kallanish. In 2015, hot-rolled coil prices in NW Europe dipped under the €400/t mark for most of the year, while 2024 were altogether higher than those in 2025, when an upsurge kicked in only in the second half.

French steel prices decline on downstream weakness
French long and flat product prices are softening by around €15-20/tonne ($17.1-22.0/t) in large contracts compared to last month, amid the impact of limited downstream demand, Kallanish hears.
In the flat products segment, black hot rolled sheet prices are falling by around €20/t on-month to €760-770/t delivered, in line with weak coil sales across Europe.
In long products, downstream sentiment is negative amid limited demand, high costs and pressure on margins. Domestic merchant bar is under pressure from Spanish producers cutting prices, with current French levels at €320-330/t delivered, excluding size extras of around €410/t. Section prices are holding stable for now, supported by firmer demand, with first-category sections at €810-820/t delivered.
Rebar prices have edged down from last month’s peak of €720/t delivered to around €690-700/t, with activity dragging due to a subdued construction sector and weak demand (see Kallanish 26 June).
Last week’s activity was further hampered by extreme heat conditions in France, with both mills and distributors confirming the slowdown caused by the heatwave.

German mills report little disruption from heat wave
Last week’s record temperatures have not caused noteworthy disruption in the logistics of steel mills and associated operations in Germany, Kallanish observes.
Steel mills and their related association have so far not reported any issues. Saarland mills Saarstahl and Dillinger see no particular problems from low water levels on its waterways, a spokeswoman tells Kallanish.
Further down the Rhine, thyssenkrupp Steel is not aware of impairments to its logistics either. “The Rhine is not fed from glaciers anymore, but mainly from rainfall, therefore dry periods take influence on its water levels,” a spokeswoman notes. However, this has not yet been the case in recent weeks, she says.
Salzgitter receives most of its supplies via the Mittellandkanal canal, which is relatively stable in terms of water levels. Heat aside, the company recently worded complaints over train transport bottlenecks due to a number of construction sites along the railway routes.
So far during 2026, there have been no noteworthy reports on impairments of Germany’s industrial waterways overall, compared to previous dry years seen in 2018 and 2019.
Meanwhile, on various motorways the heat caused cracks in the pavement, resulting in several routes being blocked temporarily. Going forward, this could become a problem for typical transport routes used in local steel and scrap logistics.

Sideralba acquires new facility
Italian steel processor and tube producer Sideralba has acquired a production facility in Misinto, in the province of Monza, from Eusider Group, as part of an ongoing collaboration between the two companies, Sideralba ceo Luigi Rapullino confirms to Kallanish.
The Misinto site is equipped with three facilities producing electric resistance welded tubes in round, rectangular, square and oval sections, in hot rolled and galvanised steel as well as two slitting lines for strip cutting. The product range covers diameters from 12mm to 76mm in wall thicknesses of 2mm and 3mm.
The acquisition strengthens Sideralba’s presence in the Italian market and broadens its product offering, while consolidating its positioning in the European market.
In a release Rapullino calls this “a historically complex moment, characterised by strong market instability and geopolitical uncertainty. This acquisition is a testament to the company’s tenacity and firm determination to continue on its structured growth path”.
The move is part of a longer-term industrial strategy aimed at technological innovation, increased production capacity and international expansion.
In 2023 Sideralba invested over €30 million ($34.2m) in the sustainable growth and modernisation of its main site in Acerra, near Naples, to improve energy efficiency and diversify product range. The investment was part of a two-year programme involving a new warehouse, a photovoltaic farm, new equipment and modernisation of existing production lines.
The previous year, Marcegaglia and Sideralba created a 50/50 joint venture in Tunisia called SM Tunis Acier to strengthen their presence in the local cold rolled and hot-dipped galvanized coil market. The partners invested a combined €10m in an existing facility owned by Sideralba with the objective to double its CRC and HDG production capacity to 400,000 tonnes/year by 2023.

Imports have a role to play: 7 Steel
Imports will have a role to play in the UK steel market, even with the reduced tariff-rate quotas, 7 Steel UK chief executive Carles Rovira tells Kallanish.
“Imports have always been there … and they have a role to fill. I don’t think the quotas are shutting down the imports. I think the quotas are designed to strengthen the domestic industry,” he says ahead of the 1 July implementation.
In a separate statement, he describes the quotas as “a step in the right direction” but adds that “delivery now matters more than design”. He warns the government risks “holding back both producers and customers” if the growth of the UK steel and manufacturing sector is not supported.
“I think to have a strong domestic supplier is good for the whole supply chain, and obviously have imports also, which need to play their role as well,” Rovira notes, adding that there is always a higher risk when buyers opt for non-domestic material.
Sourcing domestically will not work for every customer, as some may be more fixed on prices as their priority, he acknowledges, but it will for some who see value in buying British. “Each customer is different because they have different needs,” he explains.
“There are very different situations in the downstream market. There are customers who are importing 100% of the product, of the raw material, [and] there are customers that are importing 40% of their product. I don’t see how for customers that are importing 30% or 40% of their product, that’s going to mean a big change in the business. They’re going to import a bit less, but they’re still relying on the domestic supply,” he adds.
“Imports will change over time, the country of origin, the product, and there will be disruptions. The domestic supplier should be there to support the supply chain and the customers throughout the years, because we have been here for 20 years, and we expect to be here 20 more,” he continues.
The steelmaker is looking to reallocate some of its export volumes away from Europe and into the domestic market, while also increasing its stock levels to be able to meet any increase in demand.
Rovira adds that the final quota numbers will signal if there is any further investment opportunity. The firm is reviewing its rod and bar mill portfolio, which could see some small size increases for merchant bar and sections. Its owner, Sev.en GI, recently announced £100 million ($132m) in investments for the steelmaker.