


UK HRC market ready to restock, prices perceived as bottomed
UK hot-rolled coil prices have reached bottom levels, market sources said Aug. 19, with distributors reportedly ready to restock on better end-user demand and recent stability.
Market participants reported a general stability in offer levels, with the Platts assessment hovering around GBP700/mt DDP through August.
This is in contrast to dramatic slides witnessed since April peaks — when the assessment stood at GBP1225/mt. Prices fell GBP185/mt in May, GBP150/mt in June and GBP80/mt in July before reaching a rough stabilization point in the last few weeks.
Demand levels have been poor after the initial price drop following the Russian invasion of Ukraine in February, given market uncertainties and fears of devaluation, with some sources preferring the term “correction” to characterize the recent pricing trend.
However, UK HRC prices have fallen beyond levels seen in the market prior to the Russian invasion and the resultant rally, where January-February prices were assessed between GBP800-850/mt DDP UK.
This has led sources to describe current price levels as “non-sensical,” given dramatically higher input costs, especially on energy, creating a squeeze between downward demand pressures and tightening production margins.
“Compared to prices pre-invasion, the current spot level is non-sensical,” said a stockholder source. “It’s purely driven by the demand question – many have been ready to push the button in terms of restocking but were waiting for some certainty before doing so.”
Sources widely consider current levels as the bottom, plateauing longer than expected due to the traditional summer wind-down, but with an uptick in both demand and offer levels in sight.
Buy- and sell-side sources agree that price increases will need to be substantial to push the market upward, as some buyers continue to attempt to drive the market lower, perceiving opportunity for cheaper offers.
“The market needs a strong signal that this is the end and prices have to go up,” said a mill source.
A stockholder agreed, offering that buyers are “waiting for a trigger point. If mills are bullish and push prices up by GBP100/mt or more people will be more inclined to believe it,” he said.
For distributors, end-user demand is reportedly improving, with holes beginning to appear in inventories worthy of restocking – stockholders were heard on the day as ready to engage more substantive purchasing now some stability has returned to the market.
Northern European mills remain the focus, able to offer high-quality material at competitive prices and short lead-times.
Offers from Northwest European mills were heard Aug. 19 at GBP680-690/mt DDP UK, with domestic offers reported on a range of GBP690-705/mt DDP. Offers from a domestic mill at this level were heard as pulled on the day, however, regarded as “unsustainable” by the mill source – anticipating near-term increases.
Rising prices in the non-EU import market continue to avert buyer attention, with Asian and Turkish material heard higher on week at GBP710-715/mt and GBP730-750/mt respectively, both DDP West Midlands. Long lead times and lingering uncertainties on late-Q4 price direction – the delivery time for said material – also render imports further afield as unattractive.
The Platts assessment was down GBP10/mt on week, at GBP695/mt DDP West Midlands, UK.
Platts is part of S&P Global Commodity Insights.
— Benjamin Steven


EU HRC market mood bearish on low demand
Sentiment in the European hot-rolled coil market was downward on Aug. 19 due to weak demand, caused by high stocks of distributors and limited end-users’ consumption.
Trading activity is unlikely to see a substantial recovery in September as distributors have high stocks of coil. In addition, they are expected to focus on destocking to minimize inventories by the year end, taking into account limited steel consumption by end-users.
Platts assessed hot-rolled coil in Northern Europe down Eur5/mt day on day at Eur745/mt ex-works Ruhr on Aug. 19.
Two sources reported offers at Eur750/mt ex-works Ruhr, another three market participants estimated achievable prices at Eur750/mt ex-works Ruhr.
One source, however, said that the European buyers viewed achievable prices at Eur700/mt ex-works Ruhr.
Two sources reported unconfirmed deals at prices around Eur700/mt ex-works Ruhr. This information, however, has not been widely confirmed in the market.
“Market is silent, the mills are desperate for orders as there is no hope for restocking,” a Northern European distributor said. “Offers are at Eur750/mt ex-works and there are rumors that some deals have been settled at Eur700/mt ex-works.”
Some market participants believe that the European steelmakers need to further reduce production to balance supply and demand as equipment stoppages and output cuts introduced this summer were not sufficient to support domestic prices.
Platts assessed hot-rolled coil in Southern Europe down Eur10/mt day on day at Eur710/mt ex-works Italy on Aug. 19.
Tradable value has been heard at Eur700-720/mt ex-works Italy.
Platts is part of S&P Global Commodity Insights.
— Maria Tanatar, Benjamin Steven

Eisen-Fischer invests in bending equipment
German rebar bender and distributor Eisen-Fischer is in the process of finalising a larger investment spree at its site in Diez in the state of Hesse.
Eisen-Fischer Group consists of 13 locations, most of them for sanitary, construction and D-I-Y products, with three sites specialising in steel distribution. A couple of years ago, the group decided to have its Diez site concentrate on rebar processing and distribution, and moved the miscellaneous other rolled steel products to the affiliates in Bad Hersfeld and Erfurt.
The installation of new and additional equipment began in 2020. Now, the site has three times the space for rebar processing and storage it used to have previously. All fuel-driven stir-up bending machines have since been replaced for new ones with electric servo motors, also with an eye on environmentally sensible operation, site director Markus Wagenbach tells Kallanish.
The company is still waiting for the delivery of a double-bending system of the Permatic type from German engineering company Pendax, which specialises in rebar processing equipment.
With a higher degree of automation, such machines require only one instead of three operators like a conventional machine. Wagenbach notes the decision in favour of a Permatic was made partly because of the difficulty of recruiting staff. Also, some of the conventional machines were fed with coil, while the Permatic can work all from bars, so that the more expensive and scarcer coil material can be saved for other purposes.
With a total of 13 processing machines and seven cranes, the firm will be able to produce 3,000 tonnes/month. On a storage space of 10,000m², it can store 5,000t of straight and coiled rebar, plus 2,500t of wire mesh.
Christian Koehl Germany


Australian miners welcome proposed reform to ensure economical net-zero roadmap
The Australian mining industry welcomed on 18 August the federal government’s proposed safeguard mechanism reform to help industry to reduce emissions, Kallanish reports.
The government is consulting on options to reform the safeguard mechanism to deliver Australia’s target to become net-zero in 2050. The consultation closes on 20 September.
The idea is to strengthen the country’s competitiveness in a decarbonising global economy by gradually reducing emissions limits (baselines), introducing credits for facilities that emit less than their baseline, and providing tailored treatment to emissions-intensive, trade-exposed (EITE) facilities.
According to Tania Constable, ceo of the Minerals Council of Australia (MCA), the mining industry is looking forward to a roadmap to net-zero that is orderly and not disruptive.
“Policy reform should not drive businesses to reduced production or closure due to an inability to compete with competitor countries who are not implementing strict emissions constraints on their export industries,” she adds.
The mining sector (including energy commodities) accounted for 69% of the country’s exports revenues in FY22. In addition, public coffers have received AUD 254 billion ($176.64m) in taxes and royalties from the industry, showing how relevant it is for its economy.
“It’s vital that Australia’s export industries continue to thrive and remain internationally competitive,” says Constable, noting that the industry “recognises the need to reduce emissions globally, nationally and at the sites and facilities driving Australia’s resources industry.”
She argues the transition must reflect technology readiness and costs and that mining is making “great progress” in decarbonising. If restrictions are too harsh, emissions will be shifted overseas to jurisdictions less strict, which would be neither sustainable nor real emissions reduction, the ceo concludes.

Thyssenkrupp Schulte offers lifecycle assessment for components
Thyssenkrupp Schulte, part of thyssenkrupp Materials Services, has launched an offer to support customers on their way to greater sustainability.
Under the “greenability” label, Germany’s leading distributor in terms of locations has developed two new solutions for analysis and calculation of carbon footprint.
For a fee, the “greenability carbon tracking” variant gives customers full transparency on the carbon footprint of their purchased finished or semi-finished parts and components, Kallanish hears. In the so-called “cradle to gate plus end of life” approach, both the procurement process and the entire supply chain are examined. The data collected is supplemented in a TÜV-certified process with information from licensed databases, the company notes.
Customers who want to go one step further can select the “greenability carbon compensation” option. Here, the calculated CO2 footprint is compensated. For this purpose, the customer selects an independently verified compensation project in which the sum of the consumed CO2 value is invested. The parts and components may subsequently be designated as “climate neutral” and bear the corresponding greenability label, tk Schulte says.
Christian Koehl Germany

Northern European wire rod market remains stagnated
Northern European wire rod prices have remained flat again this week due to low demand and higher energy costs in Europe.
“Summer holidays and traditional maintenance at plants also continue to lead to low demand from steelmakers,” a buyer from the Netherlands tells Kallanish. “I expect prices to go up in the next 2-3 months, but mills will probably reduce the used capacities amid high production costs.”
Domestic transaction prices for drawing-quality wire rod are at €870/tonne ($881/t) ex-works and mesh is at €850/t, sources say.
Producers are asking for €860/t ex-works, on average, for mesh-quality rod.
“Imports from countries outside the EU continue to influence the market and such offers are reported at around €790/t cfr,” another merchant notes. “Scrap prices are climbing again and not expected to drop soon.” This will also put pressure on the market, he adds.
Scrap values in Germany increased slightly so far in August. Old thick scrap sort 3 was at €350/t, while the price for new scrap sort 2/8 was at €360/t. In Austria, scrap prices are also up: old thick scrap sort 3 is at €350/t and new scrap sort 2/8 at €365/t (see Kallanish passim).
Most northern European wire rod market participants expect the market to be stable in the next few weeks. Some expect that the extremely low river water levels in Germany and other parts of Europe could impact raw materials deliveries this month and maybe spill into September.
Svetoslav Abrossimov Bulgaria
Italian rebar prices widen upward; Spanish market holds steady
Seasonal steel mill closures resulted in minimal activity in the rebar market in Southern Europe in the week to Wednesday August 17, sources told Fastmarkets.
In Italy, local mills had increased their offer prices prior to the August maintenance closures. Buyers, forecasting surges in prices heading into the fourth quarter because of the energy crisis, have accepted these higher levels, sources added.
As a result, Fastmarkets has adjusted its price assessment for Italian rebar upward.
Italy
Rebar demand in Italy had picked up in mid-July, with buyers stocking up small volumes ahead of the August summer holidays. But activity dropped off over the summer season. Despite this, local mills have maintained high prices because buyers expect prices to move upward in September, Fastmarkets heard.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar) domestic, exw Italy, was €860-934 ($875-950) per tonne on Wednesday, widening upward by €24 per tonne from €860-910 per tonne on August 10.
While prices are likely to remain stable throughout August, potential energy costs heading into the fourth quarter could sharply drive up prices, market sources told Fastmarkets.
Energy rationing, as proposed by the European Commission on July 20, could push up energy prices.
On August 5 the European Commission approved a plan, encouraging EU countries to voluntarily reduce gas consumption by at least 15% between August 2022 and March 2023.
While there is no evidence that countries will self-impose energy restrictions, if this did happen, energy prices would rise. This in turn would force mills to increase prices, Fastmarkets heard.
With a potential global recession on the horizon, consumption levels heading into the next quarter remains uncertain. If the economy constricts, end-user demand could drop off across several key segments.
If demand drops but input costs surge, mills may be forced to extend production cuts considerably, market sources said.
Spain
Mill maintenance closures resulted in minimal activity in the Spanish rebar market this past week, Fastmarkets heard.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, delivered, Spain, was €780-810 per tonne on Wednesday, unchanged since July 27.
In July, demand increased as buyers re-stocked before the summer season. However, market activity has since dropped, sources told Fastmarkets.
Prices are likely to remain stable until September, sources added.
Sliding international scrap costs since mid-April have also affected the price direction of rebar. After jumping in early July, scrap prices had retreated by the second half of July. In early August, they started to rise again.
Fastmarkets’ daily calculation of the index for steel scrap, HMS 1&2 (80:20 mix), North Europe origin, cfr Turkey, was $394.07 per tonne on Wednesday, up from $387.81 per tonne on August 10.
Published by: India-Inés Levy

Sluggish demand for European HRC amid summer closures, persistent overstocking
Trading activity in the European hot-rolled coil market remained subdued on Thursday August 18 with buyers increasingly pessimistic about low demand heading into the fourth quarter because of persistent overstocking among buyers and depressed end-user consumption, Fastmarkets heard.
Fastmarkets calculated its daily steel HRC index, domestic, ex-works Northern Europe, at €751.67 ($764.58) per tonne on Thursday, down by just €5.83 per tonne from €757.50 per tonne on Wednesday.
The latest calculation of the index is down by €42.08 per tonne week on week and by €99.58 per tonne month on month.
Market sources estimated achievable prices at €750-770 per tonne exw on Thursday.
Mills, despite offering discounts, contended with low volumes traded because of high inventories among buyers, Fastmarkets heard.
Market activity remained quiet, as would be expected during the low season, with buyers delaying large-volume orders until September, by which time there was expected to be more clarity around price trends. Some small-volume orders were achieved, however.
A pessimistic outlook regarding post-holiday prospects persisted, with some sources not expecting the traditional revival of trade in September. Mills remained unlikely to restart in September with the offer prices they initially planned, one market participant said. Continued low demand could create downward pressure on prices.
A gloomy outlook persisted in regard to whether demand from the automotive industry would pick up in the fourth quarter. With a possible recession looming, fears around sliding consumption continued to create uncertainty, Fastmarkets heard.
Fastmarkets’ calculation of its daily steel HRC index, domestic, exw Italy, was €740.00 per tonne on Thursday, down by €3.75 per tonne from €743.75 per tonne the day before.
The latest calculation of the Italian index is down by €31.00 per tonne week on week and by €30.00 per tonne month on month.
The calculation was based on buyers’ estimates of achievable prices reported at €720-750 per tonne exw.
As a result of summer maintenance closures, there was minimal trading activity, Fastmarkets heard.
Buyers were postponing their restocking activity until September in order to more accurately assess key trends such as energy cost increases and possible low consumption levels, sources told Fastmarkets.
Imports
Demand for overseas coil was also subdued in the week to Thursday.
Offers of Turkish HRC imports were reported at €690-700 per tonne cfr Antwerp.
Overall, demand among domestic buyers for imports remained low.
“In general, EU buyers are not very interested in overseas HRC bookings for the time being, due to long lead times and little difference with the domestic HRC prices in Europe,” a market participant said.
Published by: India-Inés Levy

EU HRC prices stable as market doubts September salvation
The European hot-rolled coil market remained uncertain on price direction Aug. 18, given rising input costs in a quiet market environment.
Platts assessed hot-rolled coil in Northern Europe stable Aug. 18 at Eur750/mt ex-works Ruhr.
Distributor sources reported tradable value at Eur750/mt ex-works Ruhr, though the market was heard as extremely quiet given the ongoing holiday period. Offers were heard on a range of Eur750-800/mt ex-works Ruhr, though market participants did not interpret this as indicative of an uptrend.
A strong wait-and-see sentiment was identified as the market moved into late August, with only a few weeks left before the traditional restocking period in September.
However, stockholders continued to report high stock levels due to prebooked and incoming import material — as well as poor end-user demand — meaning that most deny intention to restock substantially for the remainder of the year.
“We have no problems getting stock anywhere,” a distributor said. “Our sales are picking up a bit and inventories are going down to the point we can look at replenishment, but not for this year, to be honest.”
Price direction is very uncertain, with poor demand and rising production costs pushing the market on both sides. Some mills were heard as offering with the condition that prices could include variable extras on energy costs at time of delivery, but this was not agreed on by buyers or widespread in the market on the day.
“It’s very quiet at the moment,” another distributor source said. “Everyone’s waiting for something to happen, be that a price rise or further decline. There’s been some attempts to put something on the table in terms of base price increases or extras for energy or transport, but this was more to gauge reception from buyers than it was any attempt to lead the market in an upward direction.”
Given ongoing uncertainties in the market and recent devaluation of material, buyers were heard as requiring firm offer prices in negotiations — resistant to flexible surcharges to absorb mill costs downstream.
The Italian market remained silent, with tradable value indications continuing to surround Eur720/mt ex-works Italy — the unchanged Platts assessment on the day.
— Benjamin Steven, Maria Tanatar
Offshore wind growth to boost steel demand: WoodMac
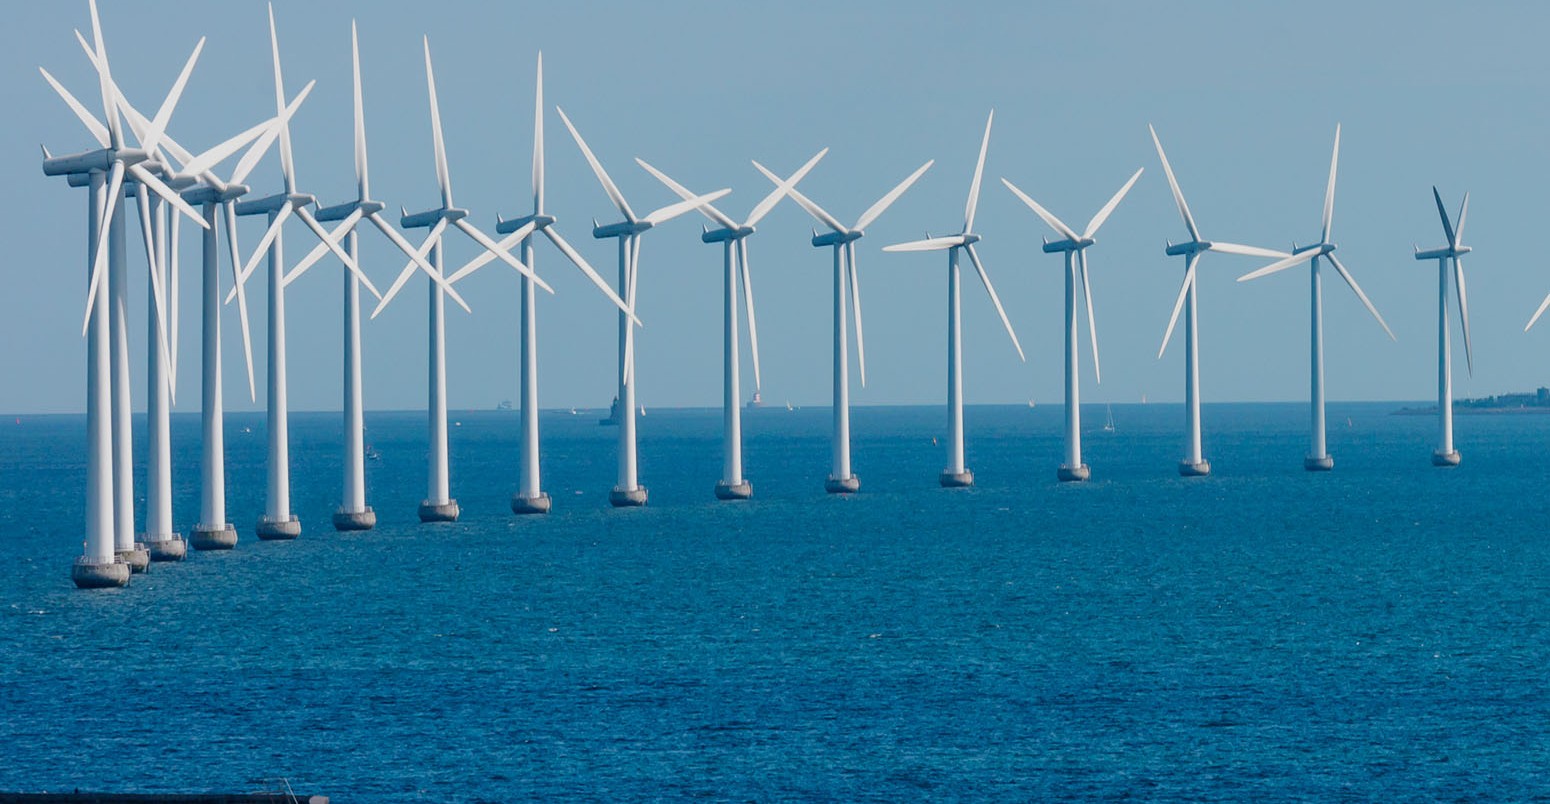
Growth in the offshore wind market is set to explode, with wind tower tonnage getting heavier, meaning more demand for steel, says Wood Mackenzie.
With increasing numbers of countries committing to tougher climate targets, offshore wind is a key technology that will power global decarbonisation – the industry is no longer in its infancy, the consultancy points out. Almost $1 trillion is predicted to flow into the market over the next decade, Kallanish notes.
Driven by continually larger turbine technology, by 2029 most towers will be over nine metres in diameter – a significant increase from the average five to six metres that was required in 2021. Turbines will also need more tower sections, which will result in a four-fold increase in demand for those sections.
By 2031, the average tower will be nearly three times heavier in comparison to a decade before. Beyond 2030, meanwhile, the uptake and globalisation of floating wind farms will further increase both complexity and weights of the required components.
Offshore wind towers will need nearly 500% more steel in 2031 compared to 2022 demand levels. As the volume of orders increases, similarly the annual spend on towers will increase five-fold, with the cumulative spend from 2022 to 2031 reaching €15 billion ($15.3 billion).
“Up until now, offshore developers have had the luxury of significant oversupply in the offshore wind market,” says Wood Mackenzie research analyst Finlay Clark. “With ample supply to cater for fluctuating demand, suppliers’ margins have been squeezed to unsustainably low levels. Aggressive bidding in tenders, combined with higher steel and logistics costs, is also having a detrimental impact as developers’ cost pressures are passed onto the supply chain.”
However, towards 2025 the growth in demand will significantly outpace the growth in supply.
Adam Smith Poland