


Demand boosts rebar prices in Italy; prices down in Spain
Rebar prices rose in Italy but dropped in Spain in the seven days ended Wednesday July 13, while mills will may prices higher this week across all long steel products amid surging energy costs, sources told Fastmarkets.
Italy
While prices for domestic rebar in Italy have been tumbling over the past month, significant boosts in demand indicate the price floor may have been reached and prices could recover, sources told Fastmarkets.
Fastmarkets’ price assessment for steel reinforcing bar (rebar) domestic, exw Italy was €830-880 ($833-883) per tonne on Wednesday, up by €5-20 per tonne from €810-875 per tonne week on week.
Producers are likely to re-set prices higher this week before shutting for the low season to reopen at higher prices in August, market participants said.
“Demand is a little better in July, maybe because customers have finished stocks and now the need to buy before mills shut down for summer” adding that “constructions are going on, and as usual in July all sites are trying to accelerate before the August summer holidays,” a source told Fastmarkets.
With energy shortages and subsequent energy cost rises remaining uncertain, producers are wary about taking large-volume orders, Fastmarkets heard.
While international scrap prices have increased, European scrap is still under pressure. In Italy, domestic scrap prices have fallen by €100 per tonne month on month, in part due to increased supply as steel mills reduce production over the low season.
Declines in scrap prices, however, are not enough to compensate for surging energy costs. In July 2022, average electricity prices in Italy were around €400 per megawatt-hour, up from about €271 per MWh in June 2022 and sharply up from €103 per MWh in July 2021.
Despite scrap prices declining in Italy, mills are therefore still pushing for higher prices, Fastmarkets heard.
Spain
While demand and prices remained depressed for domestic rebar in Spain, a price trend reversal could be possible due to increasing input costs, market sources told Fastmarkets.
Fastmarkets’ price assessment for steel reinforcing bar (rebar), domestic, delivered, Spain was €760-780 ($763-783) per tonne on Wednesday, down by €20 per tonne from €780-800 per tonne the previous week.
Weak demand, low trading activity and a wait-and-see attitude in the market continued to prevail, causing prices for Spanish rebar to drop further in the week.
However, with mills like ArcelorMittal due to raise prices by as much as €60 in the coming week, an uptrend appears to be likely, Fastmarkets heard. Sources expected buyers to return to the market for restocking in the upcoming weeks, sources told Fastmarkets.
Decreasing international scrap costs since mid-April have been a major factor in the falling rebar market, but prices began to increase last week. International scrap prices have since begun to flatten amid religious holidays in Middle Eastern countries.
Fastmarkets’ daily calculation of the index for steel scrap, HMS 1&2 (80:20 mix), North Europe origin, cfr Turkey was $398.48 per tonne on Tuesday July 12, up from $371.50 the previous week.
Published by: India-Inés Levy


Germany’s Klockner acquires two local stainless steel service centers
German metals producer and distributor Klockner & Co said July 13 that it has acquired two local stainless steel service centers, Hernandez Stainless GmbH and RSC Rostfrei Coilcenter GmbH, for an undisclosed figure as part of its bid to expand to expand its operations in Germany.
The company carried out the purchases through its Becker Stahl-Service subsidiary, one of the largest service centers in Europe in the flat steel sector, with sales of around Eur700 million ($703 million) in fiscal year 2021.
“Both of these acquisitions are of major strategic importance for us,” Klockner CEO Guido Kerkhoff said. “Hernandez Stainless and RSC Rostfrei Coilcenter will strengthen our position as a leading digital one-stop shop platform for steel, stainless steel and aluminum, and as a pioneer in sustainability. Going forward, we will be able to provide our customers with an even more comprehensive and custom-fit product and service portfolio.”
Hernandez provides surface machining and stocks stainless flat products. RSC is specialized in stainless steel coil cutting. Hernandez and RSC operate extensive machine facilities and supply around 400 distributors throughout Europe as well as stainless steel processors in various industries. RSC is also a major supplier to Hernandez.
Klockner has said it is driving forward an expansion of its in-house product and service portfolio. The additions to the portfolio as a result of this latest transaction will enable customers to purchase processed stainless steel through Becker. Becker has also already significantly expanded its service center activities in carbon steel and aluminum.
The newly acquired units, which generated sales of around Eur160 million in fiscal year 2021, are expected to be included in the company’s consolidated financial statements from the beginning of the third quarter of 2022. The transactions remain subject to approval by the competition authorities.
Domestic prices for hot-rolled coil in Northern Europe were stable on July 13 as market activity remained low, with restocking expected by end-July. Platts assessed HRC in Northern Europe at Eur855/mt ex-works Ruhr July 13, stable day on day, according to S&P Global Commodity Insights data.
— Annalisa Villa


EU HRC market sees spot levels at odds with buyers’ expectations
Distribution sources saw a “difficult” EU HRC market July 14 as end-users compared current spot prices with more expensive material purchased during the rally seen in the wake of Russia’s invasion of Ukraine.
S&P Global Commodity Insights assessed hot-rolled coil in Northwest Europe stable on the day at Eur855/mt ex-works Ruhr. In South Europe, HRC was also assessed stable at Eur780/mt EXW Italy.
The market was largely aligned on workable levels for the Northern European market, with tradable value indications heard in a range of Eur850-870/mt EXW Ruhr.
Offers were heard higher at Eur900/mt EXW Ruhr from one mill, though this price level was not yet considered realistic for the market, with the price seen relatively stable for the near term at Eur850/mt EXW.
While the European market has seen a degree of demand revival, substantial restocking remains limited due to material bought during the rally experienced at the onset of the war in Ukraine.
HRC prices in NWE hit Eur1,460/mt EXW Ruhr at the peak, as assessed by Platts March 21.
“Prices have stopped falling but today’s levels at Eur300-500/mt away from what was bought by service centers and stockholders at market peaks,” said a distributor source.
“This isn’t unanimous for the market, as some traded back-to-back, but it’s definitely weighing on the general sentiment.”
However, demand was expected to recover further in July for September orders.
“Indeed, the main problem is that buyers are sitting on big volumes booked at tragically higher prices,” said an Italian trader source.
“But they will have to come back and restock in July otherwise they won’t be able to get material in time for September — especially considering all the stoppages in August.”
Buyers were heard avoiding the import market for similar reasons, with uncertainty as to the price direction in Q4. Material was heard as custom-cleared in ports at substantial volumes, with ample space remaining in safeguard quotas, averting fears that purchased import material would be subject to a safeguard duty of up to 25%.
Instead, the lack of interest was said to be motivated by fears that material to arrive in Q4 could be odds with future spot prices, with price volatility in either direction — reinforced by a preference to protect high profits achieved in H1.
“Prices at the moment are at a decent level but there are fears material arriving in September-October could be too expensive or too cheap,” said a distributor source.
“Nobody needs the business to breakeven — no one needs the activity after good business from the first six months. Pressures aren’t as they were decades ago, no one has to sell or produce — most are sitting on a bag of gold.”
— Benjamin Steven, Maria Tanatar
Klöckner acquires stainless operations
Klöckner & Co has acquired the companies Hernandez Stainless GmbH and RSC Rostfrei Coilcenter GmbH, Kallanish learns from the German distribution group.
Both acquisitions were made through Klöckner subsidiary Becker Stahl-Service. The acquisitions mark Becker’s entry into stainless steel processing in a significant extension to its product and service portfolio. Hernandez provides surface machining and stocks stainless flat products. RSC is specialised in stainless steel coil cutting.
Hernandez and RSC operate extensive machine facilities and supply around 400 distributors throughout Europe, as well as stainless steel processors in various industries. RSC is also a major supplier to Hernandez. Together, the two companies have about 70 employees and generated sales of around €160 million ($160m) in 2021. Hernandez is headquartered in Hockenheim and RSC in Süssen, both in the German state of Baden-Württemberg.
The two companies are expected to be included in the consolidated financial statements from the beginning of the third quarter. The transactions remain subject to approval by competition authorities.
Christian Koehl Germany


Materials prices put brake on German construction
After a reasonably good first quarter, German construction activity in the wake of the Russian attack on Ukraine was dealt a blow, and could keep ailing in the months to come.
In April, industry orders were 11.7% below April 2021, and 16.4% lower than in March, industry association Hauptverband der Deutschen Bauindustrie reports. “Investors are suspending their projects, scared by the overall insecurity and the strong increase of materials prices,” comments Hauptverband manager Tim Oliver Müller. This is especially true for residential construction.
Materials prices in May reached another all-time high, rising 17.6% above values in May 2021. “These are increases last seen in 1970,” the association states. For steel alone, the increase was far larger, at as much as 94%. Construction companies cannot make offers because the original cost calculation might simply become invalid during the project. “We fear that many residential projects will be postponed, due to construction costs, and rising interests for loans,” Müller says.
A manager at a rebar distributor words it even sharper. “Private residential construction is nearly dead, because people cannot afford it,” he tells Kallanish. In reference to rebar mills and the exorbitant prices they achieved in recent months, he says “they finally see that they are biting the hands that feed them.”
Christian Koehl Germany
Northwest EU rebar coils and bar prices re-align
The spread between prices of straight rebar and rebar in coil from northwest European mills has more or less zeroed after widening significantly last year, Kallanish hears from market players.
Until two years ago, the two sorts differentiated only on size extras, which equate to €265/tonne ($267) added for straight bar and €280 for coil. The gap formed during the Covid-19 pandemic and has since been cultivated by mills, as coil has become relatively scarcer. The premium for coil was easily €20-30/t, and in some transactions was reported reaching €100.
Some sources are still seeing premiums today of €20 or more, but others find the difference has vanished altogether. This would correspond with the suspension seen in demand. Previously, coil supply, especially, was tight – some sources even say it was limited deliberately by the mills. Now that supply exceeds demand, mills are pressured to sell with buyer-friendly conditions.
Base prices on the market have dropped further in July, and either sort is now seen at between €750/t and €800/t. Wire mesh is seen at around €900/t, the mark quoted for rebar only two weeks ago.
Christian Koehl Germany
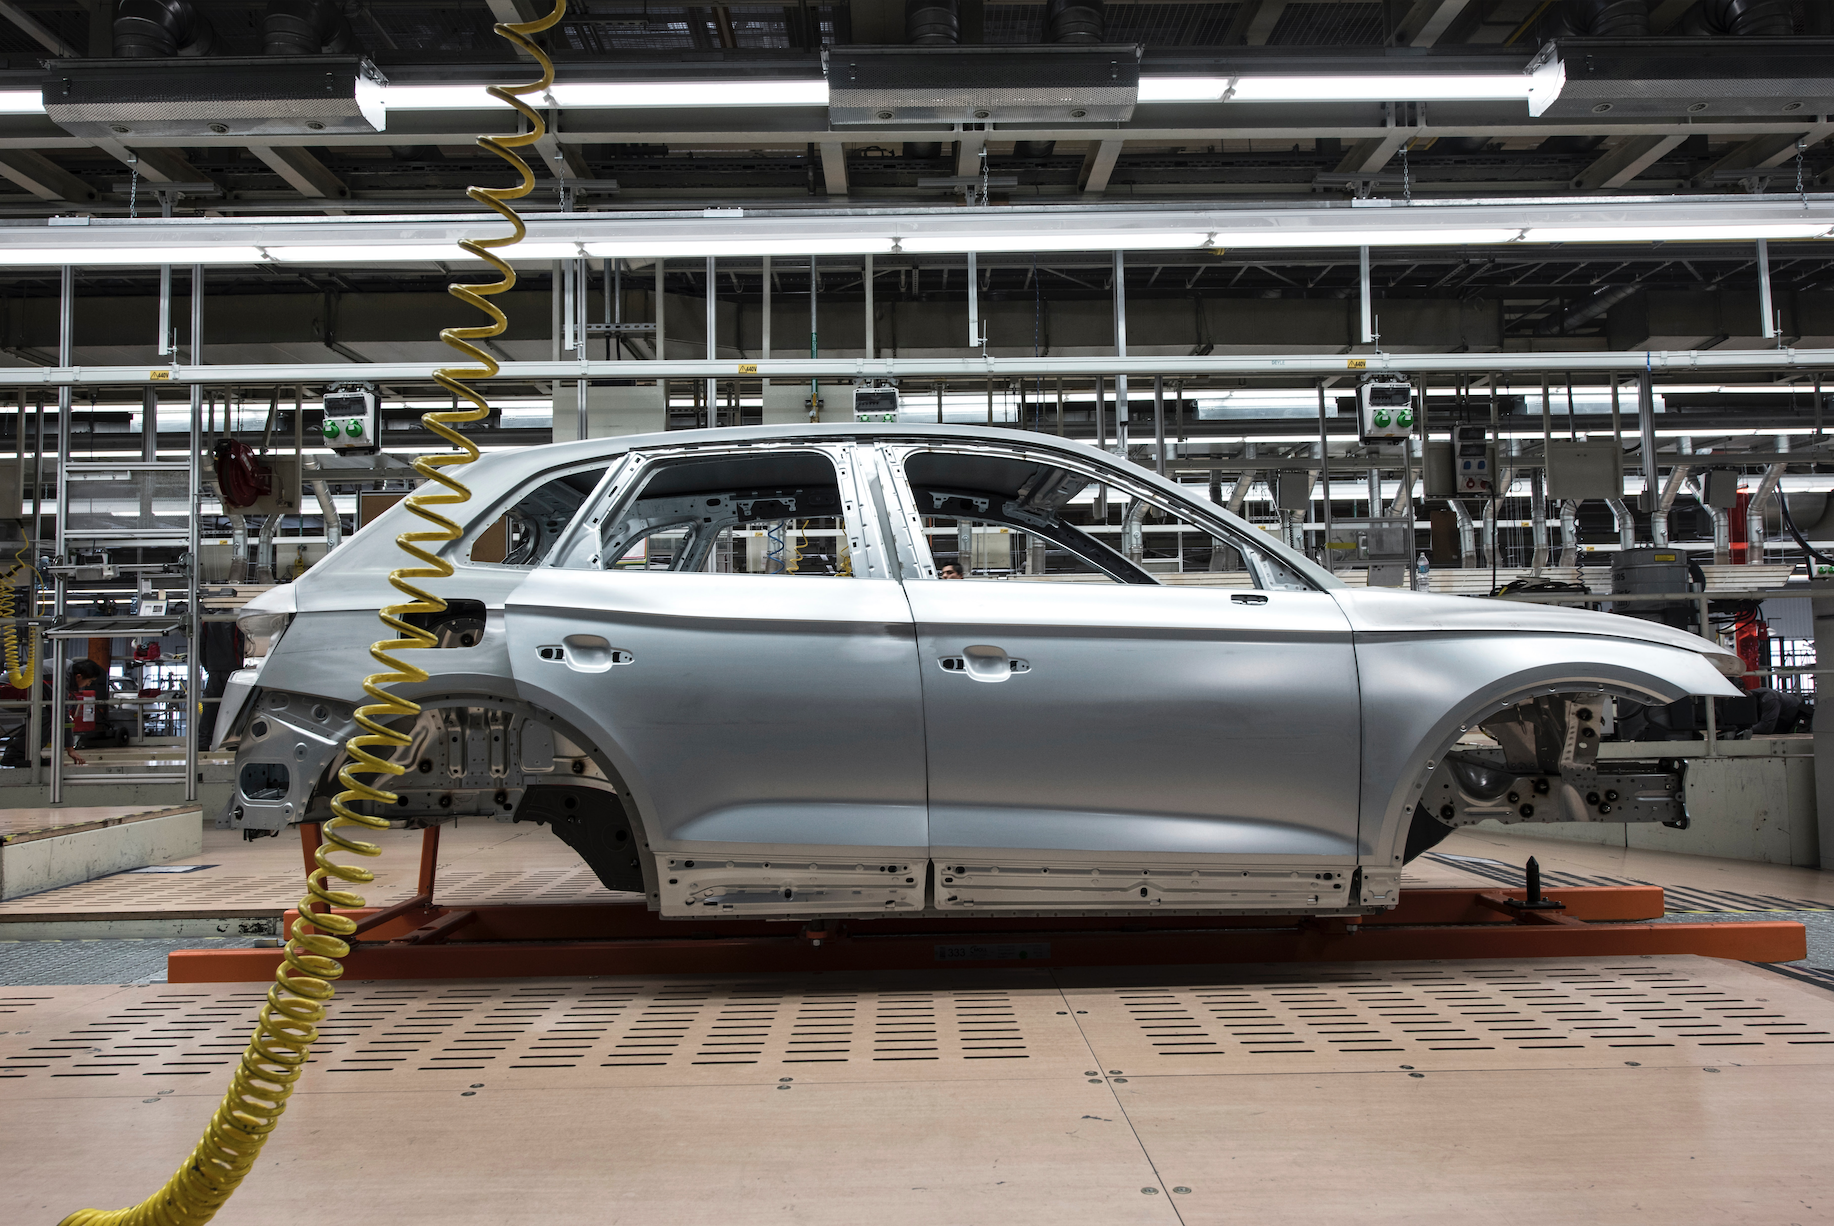
Chinese auto industry ends June with full recovery
In the first half of 2022, China’s automotive industry was hit by supply disruptions, demand contraction and weakening expectations. In particular, blockades in areas such as Jilin and Shanghai caused a cliff-like drop in production and sales from late March to April. Subsequent stimulus policies have enabled the industry to recover since May, and to register a best-ever June performance, Kallanish observes.
Output in June rose further, by 29.7% from the prior month to 2.5 million units, also up 28.2% year-on-year, according to data from the China Association of Automotive Manufacturers (CAAM). Total production in the first six months this year was 12.12m units, a y-o-y decrease of just 3.7%, representing a considerable recovery after being hit by severe lockdowns in April.
In contrast to passenger cars, the performance of commercial vehicles was still sluggish despite a m-o-m rebound. This was due to the high base resulting from the elimination of backward trucks as part of environmental protection policies last year. Also, in H1 this year, infrastructure construction was affected by the epidemic, which also slowed demand for trucks.
Monthly production of new energy vehicles (NEVs), meanwhile, hit a record high at 590,000 units, soaring 130% y-o-y. In H1, output was boosted to 2.66m units, a surge of 120%, and the penetration rate reached 21.6%.
In H2, CAAM expects challenges from chip shortages, high costs of NEVs, fewer policies to promote consumption, and weak commercial vehicles demand.
The association has adjusted its annual auto sales forecast down to 27m units, a rise of 3% y-o-y. Of that, sales of NEVs, passenger cars, and commercial cars are expected to rise 56% and 7%, and decline 16% y-o-y, respectively.
Kallanish Asia
UK says antidumping measures on rebar from China should be removed
The UK government has proposed that the antidumping measures on rebar from China are removed to meet demand from the construction industry.
In its initial findings, the UK’s Trade Remedies Authority has proposed July 13 that existing antidumping measures on imports of Steel Concrete Reinforcement Bars, also called High Fatigue Performance rebar, from China should be revoked.
Keeping them “would not be in the economic interests of the UK” due to high demand and the fall in supply from Russia, Belarus and Ukraine in the meantime, according to the TRA.
HFP rebars are mainly used in the construction industry. The industry has been rebounding since the pandemic.
In 2020-21, 27% of total rebar imports came from Belarus, Russia and Ukraine. These imports are likely to drop substantially due to the Russian invasion of Ukraine and the resulting sanctions.
The antidumping measures were imposed back in July 2016 by the European Commission when the UK was still a part of the EU. This is the transitioned measure that was subject to the TRA’s transition review.
The EC allowed the EU measure to expire on July 29, 2021, without review.
“We have a duty to weigh up the impact of dumping on UK producers against the broader effects on the UK economy of imposing tariffs,” TRA Chief Executive Oliver Griffiths said.
“Our judgement is that the impact on the British economy of higher prices would significantly outweigh the impact on the sole UK producer of rebar of removing tariffs on Chinese imports,” he said.
Following the July 13 publication, there will be a 30-day period in which interested parties can comment on the report. The TRA will then consider and produce a Final Recommendation, which will be sent to the Secretary of State for International Trade who will make the final decision on whether to uphold the TRA’s recommendation.
UK Steel reaction
UK Steel, the association that represents the country’s steel producers, told S&P Global Commodity Insights July 7 that it will present “concrete evidence to Government and the TRA demonstrating that it would be an unforgivable error to uphold such a recommendation that would cause huge damage to UK steel industry.”
The association said the UK rebar market is amply supplied both from domestic production as well as from imports, half of which are from the EU, but also a wide array of other origins including Turkey, Algeria and India, “so it is truly bewildering as to how the TRA concluded that UK supply would be constrained but for dumped steel from China.”
China is currently exempt from safeguards on rebar as it is considered a developing country whose exports to the UK fall below the 3% threshold, a reason why it was important to keep the antidumping measures in place on this product, according to the association.
The main rebar producer in the UK is Celsa UK and Liberty Steel UK also makes rebar, but both only started producing from the end of 2020, whereas the injury period for this investigation was since 2017. Thus, they were not fully considered for the purposes of this review, UK Steel told S&P Global.
In 2021, the UK imported 35% of its rebar from Portugal, 14% from Spain, 13% Russia, 11% from Algeria and 9% from Turkey, according to UK Steel data. China used to be one of the main rebar exporters before the introduction of the measures in 2016, but after 2016 import volumes from China have clearly dropped.
UK HFP rebar imports:
(all tariff codes listed in the measure taken at an 8 digit level)
| 2014 | 2015 | 2016 | 2017 | 2018 | 2019 | 2020 | 2021 | |
| Imports from China (mt) | 262,105 | 372,659 | 1,285 | 959 | 1,974 | 6,832 | 5,203 | 223 |
| Total rebar imports (mt) | 551,559 | 590,370 | 390,006 | 422,976 | 491,250 | 449,061 | 329,505 | 143,966 |
| Rebar imports from China as % of total imports | 47.52% | 63.12% | 0.33% | 0.23% | 0.40% | 1.52% | 1.58% | 0.15% |
Source: UK Trade Data (HMRC)
China accounts for 78% of global rebar production and just 2% of its spare rebar capacity could meet the entirety of the UK’s demand requirements, at a time when Chinese domestic steel demand is weakening, according to UK Steel.
China rebar futures hit lows
In China, the most actively traded October rebar contract on the Shanghai Futures Exchange was at Yuan 3,910/mt ($581/mt) on July 12, down Yuan 286/mt from July 8, according to the Platts assessment by S&P Global. The price hit a low of Yuan 3,891/mt during the trading session — the lowest since December 2020.
In the seaborne rebar market, most participants were holding a wait-and-see stance after China rebar futures hit a 19-month low amid high warehouse stock levels in Hong Kong and Singapore.
Platts assessed the 16-32 mm BS4449 Grade 500 rebar price down $10/mt at $639/mt CFR Southeast Asia, while Chinese export 16-20 mm diameter BS500B grade rebar slipped $10/mt to $628/mt FOB China from July 8, according to data from S&P Global.
— Annalisa Villa

EU long steel demand remains weak, but mills target hikes
European domestic steel sections prices remained largely stable week on week, as buyers held back from booking orders amid slow end-user demand, sources said.
Platts’ European medium sections price (category 1, S235 JR) assessment was at Eur1,200/mt delivered July 13, unchanged week on week.
One large European mill was heard by multiple buyers to target a minimum Eur60/mt hike on long steel prices amid rising energy costs and ferrous scrap prices.
In Northern Europe, the Platts July assessment for domestic shredded scrap was at Eur360/mt delivered to the mill July 11, down sharply from Eur397.50/mt in June but up from expectations of Eur290-300/mt delivered in early July.
“We are in a wait-and-see mode [before buying] to see end-user demand as there are holidays now in Belgium and next week in the Netherlands,” a Benelux-based distributor said, citing a lowest workable level at Eur1,180/mt delivered for medium sections, up from Eur1,150/mt delivered one week earlier.
A second Benelux-based distributor cited a slightly higher workable level at Eur1,180-1,200/mt delivered.
One European mill source said around Eur1,200/mt delivered was now workable, following recent sales around Eur1,150-1,180/mt delivered.
“I believe prices have bottomed out and that stocks levels are low, but while there is some uncertainty on demand, I think there will be some buying activity,” the mill source added.
A second European mill source cited lower medium sections offers at Eur1,240-1,250/mt delivered, down from 1,250-1,300/mt delivered July 6.
“We see the same low demand and negative sentiment — I’m not sure when demand will return, but buyers are underestimating the reduction in the number of offers when they return as the mill stoppages will be massive,” the second mill source said.
Multiple producers reported upcoming summer maintenance stoppages of varying lengths, including as long as seven weeks, and further capacity utilization reductions in order to mitigate the hike in energy costs. Low water levels on key steel trading waterways such as the Rhine may also affect mill capacity utilization rates, as barges carrying key raw materials cannot be loaded to capacity, sources said.
Elsewhere, Northwest European domestic rebar prices also softened in the week to July 13.
The assessment of Platts’ TSI Northwest Europe Rebar was down Eur5/mt to Eur1,015/mt ex-works July 13.
German mills were heard to offer rebar at Eur1,020/mt EXW, while a French mill was heard to offer around Eur1,010/mt delivered Benelux, down week on week from Eur1,045/mt delivered July 6, but up Eur985-990/mt delivered July 7-8.
Import rebar offers to Europe were heard at Eur830-850/mt CFR from Turkey for the EU tariff-free import quota, but buyers were heard to not be so keen to book so far forward, with the euro-US dollar exchange rate also reducing the attractiveness of imports. Offers from Algeria were also heard at a similar price range of Eur830-850/mt CFR.
Platts assessed the euro at $1.0086 at 4:30 pm London time July 13, up from $1.0070 July 12.
An Italian mill was expected to raise domestic rebar prices by around Eur40/mt higher to Eur900/mt EXW Italy July 14, sources said.
Platts’ assessment for Southern European shredded scrap was at Eur350/mt delivered to the mill July 11, down sharply from Eur400/mt delivered in July. However, Italian mill sources cited higher prices July 12, with shredded scrap rising to Eur370-380/mt delivered.
— Viral Shah, Maria Tanatar
Northern European HRC prices stable, market awaits restocking
Domestic prices for hot-rolled coil in Northern Europe were stable on July 13 as market activity remained low with restocking expected by end-July.
Platts assessed HRC in Northern Europe at Eur855/mt ex-works Ruhr July 13, stable day on day, according to S&P Global Commodity Insights data.
Four buyers and one steelmaker reported tradable value for domestic HRC at Eur850-860/mt ex-works Ruhr.
One of the buyers also reported a deal settled at Eur850/mt ex-works Ruhr and said that a Northern European producer has increased offers to Eur900/mt ex-works Northern Europe.
Anticipated restocking combined with production cuts implemented by EU steelmakers and some revival of steel consumption by carmakers are likely to support the prices. Some market sources, however, questioned the extent of the demand recovery.
“Demand is better, but it is moving up from such a low point that it is hardly going to reach normal rates this year,” a Northern European distributor said.
“Market activity remains weak at the moment, any improvement is slow, and expected restocking has not started yet,” a producer said.
Other sources, however, believed that taking into account reduced steel output, longer summer maintenance of steelmakers and equipment stoppages, the buyers will have to restock for September no later than the end of July, supporting domestic price recovery.
In addition, interest in imported HRC was limited due to long lead times.
Deals for HRC from Asia were heard at Eur770-780/mt CFR Antwerp.
HRC in Southern Europe was assessed at Eur780/mt ex-works Italy July 13, up Eur5 day on day.
Italian steelmakers were offering HRC at Eur800/mt ex-works, with buyers estimating achievable prices at Eur770-790/mt ex-works.
— Maria Tanatar