


EUROMETAL President at EFDA conference in Madrid


Fernando Espada represented EUROMETAL as a speaker at the 7th European Fastener Distribution Conference organized by the European Fastener Distributor Association (EFDA) the 12 May in Madrid.
One of the key issues of the Madrid conference was the development and challenges of the increasing metal prices which have a significant impact on the production and procurement situation of fasteners.

German rebar market holds breath amid international correction
Activity in the German rebar market has subsided to the point that mills have stopped giving offer prices, Kallanish hears from observers.
“There is no daily price at the moment, you’d have to negotiate individually,” a manager of a distributor group says. This situation is mainly the result of the wide gap to prices in other countries, and the downturn in scrap prices. “The sentiment now, on Friday 13th, is that everybody holds still, and nobody wants to seize the blade of a falling knife,” he warns.
While orders are largely held back nowadays, the base prices that would be paid were deals to be concluded would be well under the peak of €1,100/tonne ($1,145) reached in April. Adding the size extra of €265, those peak levels translated to €1,365 delivered. And that was only the minimum of a range that differed widely between mills, inching up to €1,200 base, with some buyers reporting transactions well above that.
It was a period of panic for some, “and whoever needed to refill urgently, also with a view on the disruptions seen for a while in logistics, would pay more,” the manager explains.
Another buyer notes that the higher price mark was set by the southern German mills, and reported by customers buying there regularly for the sake of guaranteed supply and wide product range. “I had a talk with one mill a week ago, and I told them they are far off the real market, when they were €200 above the European average,” he opines.
Christian Koehl Germany

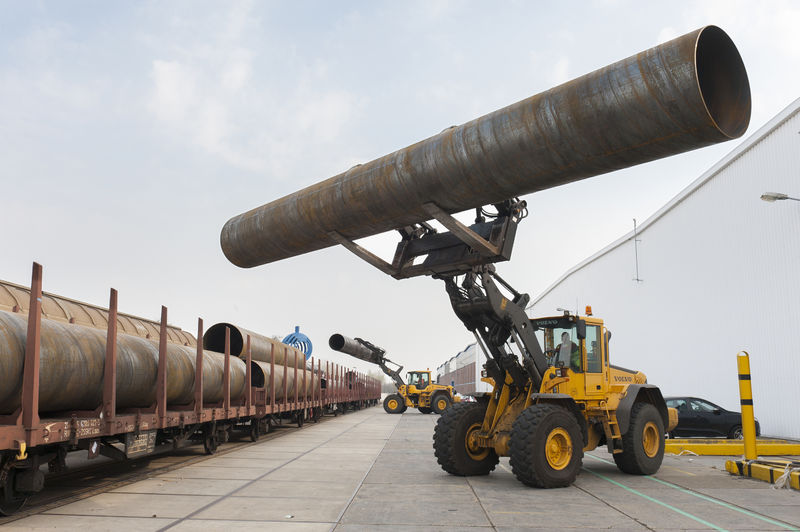
EU launches China seamless pipe anti-dumping expiry review
The European Commission has initiated an expiry review into anti-dumping duties on imports from China of certain circular seamless pipe of external diameter above 406.4mm. This follows a request for the review from the European Steel Tube Association.
The products in question fall under HS codes 7304 19 90, ex 7304 29 90, 7304 39 98 and 7304 59 99, Kallanish notes.
The investigation of a continuation or recurrence of dumping will cover the period from 1 January 2021 to 31 December 2021. The examination of trends relevant for the assessment of the likelihood of a continuation or recurrence of injury will cover the period from 1 January 2018 to the end of the review investigation period.
The investigation will normally be concluded within 12 months and in any event no later than 15 months from the date of the initiation.
The definitive AD rates imposed in 2017 ranged from 29.2% to 54.9% and replaced provisional duties imposed in November 2016 of 43.5-81.1%.
Adam Smith Germany

Only two Russian automotive plants continue production
Russian carmaker AVTOVAZ will halt production from 16 to 20 May due to a lack of semiconductors and other components, according to the firm’s trade union.
Earlier, AVTOVAZ suspended production of cars from 30 April to 11 May due to planned corporate vacation and holidays amid the ongoing shortage of auto components.
French automaker Renault intends to transfer its 68% stake in Russian carmaker AVTOVAZ to Russian science institute NAMI (see Kallanish passim). In March, Renault suspended operations in Russia following the levying of Western sanctions due to the Russian invasion of Ukraine.
At present, the production of cars and trucks in Russia is being carried out only by Haveil Motor Rus and truck-maker Kamaz, Kallanish notes.
The Mazda Sollers plant in Vladivostok is meanwhile on vacation and will resume work on 19 May.
UAZ announced a corporate holiday for six working days in the first half of May. As a result, the conveyor at the enterprise will be stopped for two weeks. Avtotor suspended production of cars during its corporate holiday, which will last from 1 to 22 May.
More than 20 foreign carmakers have suspended production or left the Russian market since Russian forces invaded Ukraine on 24 February and sanctions were imposed against Russia.
Carmakers in Russia decreased output in January-March to 244,000 passenger cars, down by 33.2% on-year (see Kallanish passim). In March alone, 41,000 units were produced, down by 72% on-year, the steepest fall since Covid-19 lockdowns slashed output to 30,000 cars in April 2020, Rosstat says.
Svetoslav Abrossimov Bulgaria

UK firm develops stainless series to replace 300
UK-based GENIUS Materials Technology says it has developed a new series of high-strength austenitic stainless steels to replace the majority of existing grades in the 300 Series.
“Their strength properties are equivalent to Duplex and Super Duplex stainless steels, whilst their ductility and toughness properties have all the advantages that are normally associated with austenitic stainless steels, particularly at sub-zero temperatures, but at the same time possessing far superior corrosion resistance,” metallurgist Dr Ces Roscoe says in a note sent to Kallanish. “The [trademarked] N’GENIUS Series advanced technology has also been applied to develop an extensive range of corrosion resistant alloy line pipe grades.”
The world currently produces over 50 million tonnes/year of stainless steel, of which austenitic grades account for more than 70%. But aside from a limited number of higher-alloyed and niche grades, the majority of available materials have not changed significantly since the 1960s, GENIUS says. Demand is however increasing for stronger, more durable and environmentally-friendly material.
The new series will enable engineers to design products with reduced wall thicknesses, using less material and making products easier to handle and transport to site. This can also lead to weight savings and an overall reduction in construction and project costs, and ultimately contribute to lower carbon emissions, GENIUS adds. Buyers can also select alloy types that are less sensitive to alloy surcharge, relative to higher alloyed grades, leading to savings in overall project costs.
Adam Smith Germany

Turkish steel producers expect EU to remove safeguards following WTO report
The Turkish Steel Producers’ Association expects the European Commission to remove safeguard measures on steel products as a World Trade Organization panel supported the thesis that these are contrary to international trade rules.
The removal of EU safeguards will contribute to the re-establishment of free and fair trade globally, as well as improve trade relations between Turkey and the EU, the TCUD said in a statement.
In an April 29 panel report shared with all WTO members, the organization called on the EU to bring its measure into conformity with the Agreement on Safeguards and the GATT 1994.
The WTO, however, declined to make a suggestion under Article 19.1 of the dispute settlement understanding.
“Removal of safeguard measures will also be an example for similar practices worldwide,” TCUD said, saying that if they were not removed, it expected Turkey to answer the measures according to the reciprocity principle.
The Turkish trade ministry, which launched an anti-dumping investigation into hot-rolled coil imports from the EU and South Korea earlier in 2022, on March 11 determined rates of 14.08%-49.84% to be applied to deliveries from a series of foreign producers.
The Board of Evaluation of Unfair Competition is expected to announce its final decision about the investigation within the second quarter of 2022.
The EU is traditionally one of Turkey’s largest steel export destinations, while the region is also one of Turkey’s largest steel suppliers.
Despite the decline seen in Turkey’s steel exports to the EU in the first quarter amid safeguard measures, TCUD said Turkey’s overall steel exports rose 4% in Q1 to 4.3 million mt as Turkish mills successfully diversified their export destinations.
The revenue generated from these exports jumped in Q1 to $4 billion amid globally higher steel prices.
Turkish exported rebar was at $960/mt FOB on April 1, reflecting a $220/mt jump since Feb. 23, the day before Russia invaded Ukraine, according to Platts assessments from S&P Global Commodity Insights.
Turkish mills’ rebar prices, however, have declined gradually since amid slowing demand and lower imported scrap prices.
The Platts Turkish exported rebar assessment was at $820/mt FOB on May 12, down $10/mt day on day.
Turkey’s overall steel imports also increased 0.6% on the year in Q1 to 4 million mt, while the cost of these imports jumped by 46.6% on the year to 4.2 billion, despite steel consumption dropping 6.5% ton the year o 8.5 million, TCUD data showed.
— Cenk Can

Swedish dockworkers call off Russian ships blockade, may reinstate it
The Swedish Dockworkers Union (SDU) is calling off the blockade on Russian ships, some of which were carrying pig iron and aluminum, to avoid conflict with port authorities contesting its legitimacy, but intends to reinstate it before the end of May, a union official told S&P Global Commodity Insights May 13.
SDU has been blocking Russian ships, ships with Russian goods and generally ships on their way to or from Russia since March 28 in sympathy with Ukrainian dockworkers, and trade union activists.
A month later, the employers’ organization Ports of Sweden (Sveriges Hamnar) filed suit with the labor court to request the blockade be lifted and to claim damages, according to the information on the SDU website.
“Our blockade was meant to finish at the end of May, but we agreed to shorten it in exchange for the plaintiff dropping the lawsuit,” SDU vice president Erik Helgeson said.
The union intends to give notice of another blockade of Russian ships in the week of May 16, which should then come into force before the end of May.
Its fellow association, the Swedish Transport Workers’ Union, had initiated its own blockade on May 1 and no longer assists shipments to or from Russia, but before it started, a few ships had managed to pass through as the dockworkers’ union does not have members in every port.
Those ships carried mostly oil and metals, predominantly pig iron and aluminum, according to Helgeson.
The blockades are meant to compensate for the lack of initiative from the Swedish government to cease all seaborne commercial exchanges with Russia, he said.
There are over 40 active ports in Sweden, most of which respected the blockade, but about half a dozen continued servicing Russian ships or those of their intermediaries.
These ships constitute only a small share of Sweden’s seaborne trade, but some Swedish companies still prefer to buy certain raw materials in Russia, including pig iron and aluminum, because of their low price. For them, the issue is not in substituting with commodities from different regions, but with commodities at similarly cheap prices, according to Helgeson.
The LME aluminum cash settlement rose $35 to $2,723/mt May 13, having lost $50 May 12. S&P Global assessed pig iron at $565 FOB Black Sea on May 13, down $62.50 from May 5.
— Ekaterina Bouckley

Hydrogen below $3/kg needed for breakeven green steel in Europe
Delivered hydrogen prices of below Eur3/kg ($3.10/kg) would be needed for breakeven green steel production in Europe in the current high energy price environment, industry group Hydrogen Europe said in a new report.
The cost of producing renewable hydrogen via alkaline electrolysis in Europe was assessed at Eur10.70/kg ($11.18/kg) May 11 (Netherlands, including capex), based on month-ahead power prices, as per S&P Global Commodity Insights data.
Hydrogen prices would need to fall to below Eur1.50/kg in an “adjusted prices scenario,” which assumed prices falling to reflect potential future fossil fuel price drops, Hydrogen Europe said in its “Steel from Solar Energy” report, published May 11.
The estimated breakeven CO2 price in both scenarios is Eur140/mt, it said.
European carbon allowance prices for December 2022 delivery under the emissions trading scheme settled at Eur88.83/mtCO2e on May 11, according to a Platts assessment published by S&P Global.
The report models the costs for hydrogen-based direct reduction of iron ore coupled with an electric arc furnace, versus a base case of blast furnace steel production.
Blast furnace steel production typically produces around 1.6-2.0 mt of CO2 per ton of crude steel.
With current renewable hydrogen production and delivery costs, the higher costs of the DRI route with hydrogen would add around Eur100-170 per vehicle for a typical internal combustion engine car.
Hydrogen Europe noted that its estimates were based on current electrolyzer and solar photovoltaic costs.
“It is expected that a further decrease of the solar PV technology costs, coupled with a reduction in electrolyzer capex, resulting from scaling-up and automation of the manufacturing process, should lead to a significant fall in renewable hydrogen production costs in the coming decade,” it said.
Electrolyzer capex costs alone were expected to fall by around three quarters compared to current levels in that period.
In the meantime, Hydrogen Europe said, “significant financial support would be needed” if consumers are not willing to pay a green premium.
Scaling up
A second challenge was scale, the association said. There was around 103 million mt/year of hot metal blast furnace capacity across the EU, it said.
Switching all of that capacity to hydrogen-based DRI could save up to 196 million mt/year of greenhouse gas emissions, but would need up to 5.3 million mt/year of renewable hydrogen, and 370 TWh of additional renewable electricity generation.
Europe added 31 GW of new solar capacity in 2021 with annual growth forecast to double to 75 GW by 2026, Solar Power Europe said in a report May 10.
Germany was forecast to lead Europe’s 2022 additions with 7.4 GW of the predicted 39 GW total across Europe in 2022, it said.
The EU is targeting 10 million mt/year of renewable hydrogen production by 2030, with an additional 10 million mt/year of imports by that date.
Hydrogen Europe said converting a single steel plant with a capacity of 4 million mt/year of crude steel would need 1.2-1.3 GW of electrolysis running at full capacity.
It estimated this could require Eur3.3 billion of capital investment.
And to guarantee a steady supply of renewable hydrogen from intermittent renewables, significant hydrogen storage would also be needed.
Hydrogen Europe said a relaxing of proposed strict temporal correlation rules for renewable power and hydrogen production under the EU’s revised renewable energy directive would help increase the renewable energy share in hydrogen production.
It suggested a 24-hour period in which operators could balance renewable energy production with its consumption for hydrogen output.
— James Burgess

Stalprofil ups shipments, sees risks to economic growth
Stalprofil’s steel product sales rose 12% on-year in 2021 to 207,721 tonnes, with steel structures sales up 9% to 2,216t. The infrastructure segment however saw insulated pipe sales drop 30% to 1.36 million m2, due to the completion of two large contracts during the year.
The Polish distributor’s steel segment saw revenue surge 64% on-year in 2021 to PLN 924.6 million ($206.4m), thanks mainly to a continued price uptrend until the third quarter, but infrastructure segment revenue fell 27% to PLN 723.7m. Consolidated net profit surged over 350% to PLN 123.3m.
Consolidated domestic revenue rose 12% to PLN 1.48 billion but export sales dropped 27% to PLN 171.3m due to the completion of an insulated pipe supply contract to Lithuania. The main export markets were neighbouring countries, although non-EU European countries generated 60% more revenue than in 2020. Sales to Russia, Ukraine and Belarus comprised 1.6% of revenue and 1.5% of volumes.
A major risk factor going forwards is the war in Ukraine and consequent sanctions on Russia and Belarus, which have impacted supply chains for steel and raw materials, Stalprofil says. In 2021, supply from Russia, Ukraine and Belarus comprised 25% of overall Polish steel imports. The current situation could lead to price fluctuations; slowing economic growth, especially public and private sector investment; the weakening of the zloty; higher inflation; and higher interest rates that hamper investment.
“The domestic market expects a continuation of investments financed from EU funds in gas transmission networks, and road and rail infrastructure,” Stalprofil chief executive Henryk Orczykowski says in a note seen by Kallanish. “Their implementation should have a positive effect on demand and prices in the steel market. A threat to the nation’s investment plans could be the potential suspension by the EU of previously anticipated payments from EU funds due to the escalation of the conflict with Polish authorities over the rule of law.”
Adam Smith Germany

Zaporizhstal eyes Polish demand amid disrupted supply
Ukraine’s Zaporizhstal, a flat steel mill partially owned by Metinvest, has started the production of a new type of hot rolled coil for Polish customers.
Clients from Poland have ordered HRC in coils each weighing at least 9 tonnes, according to Ukrainian media reports.
Previously, two coils were welded together to fulfil such an order. Thanks to new production lines, this is no longer necessary and saves on packaging and transportation. the enterprise claims.
The firm is thus looking to capitalise on Polish demand for HRC, the supply of which has been disrupted by much-reduced Ukrainian production and the EU’s ban on Russian steel, Kallanish notes. Russia, Ukraine and Belarus together accounted for 25% of overall Polish steel imports in 2021, meaning the war in Ukraine has forced buyers there to seek alternative suppliers.
Zaporizhstal produced less steel on-year in April, owing to Russia’s invasion of Ukraine, with year-to-date output correspondingly down (see Kallanish passim). The plant produced just 68,900 tonnes of pig iron in April, down 81% on-year, 73,600t of crude steel, down 78%, and 65,700t of finished products, down 76.7%.
January-April output of pig iron fell by 45.1% on-year to 830,200t, of crude steel by 45.8% to 721,000t and of finished products by 44.1% to 630,100t.
At the end of March, the mill partially resumed output at its cold-rolling operations – after previously entering hot conservation mode – for subsequent product dispatch to the European market. Early April saw the blowing in of blast furnaces No.3 and No.4. Consequently, April saw Zaporizhstal working at around 50% capacity utilisation.
Metinvest suspended all production at the mill on 2 March due to the intensification of fighting following the Russian invasion, also idling its Zaporizhya-based coke plant Zaporizhkoks (see Kallanish passim).
Last year, Zaporizhstal produced 4.5 million tonnes of pig iron, 3.8mt of crude and 3.2mt of finished steel, all roughly flat on-year.
Svetoslav Abrossimov Bulgaria