


Czech automotive output downtrend softens further
Czech automotive output declined -3.7% on-year in the first quarter – versus -7.7% in January-February – to 364,826 units, according to the latest Czech Automotive Industry Association (AIA) data seen by Kallanish.
The Czech Republic is Central and Eastern Europe (CEE)’s largest car manufacturer, sourcing automotive steel from US Steel Kosice (USSK) and ArcelorMittal among other suppliers, and producing most cars for export.
Production mainly consists of passenger and light commercial vehicles (M1+N1), whose output declined -3.8% in Q1 to 363,052 vehicles. Skoda comprised 63.7% of output, Hyundai 20.11% and Toyota, Peugeot, Citroen (TPCA) 16.19%.
Passenger car exports in Q1 fell -3.1% to 338,812 units and local sales slumped -12.1% to 25,274 vehicles.
Czech production of buses, however, rose 6.7% in Q1 to 1,185 units.
Stalprofil foresees continued demand from infrastructure investment
Stalprofil foresees the continuation of investment into Polish gas pipelines, and road and rail infrastructure in 2019, which should help maintain demand and a positive price trend.
As a factor that will benefit its infrastructure segment Stalprofil cites the third investment round by Polish gas pipeline operator Gaz-System, which is scheduled for launch in the second half of 2019. This will cover around 2,000km of insulated pipe.
Stalprofil’s steel product sales rose 3% on-year in 2018 to 218,337 tonnes, while steel structures sales increased 17% to 3,164t. In the infrastructure segment, anti-corrosion pipe coating sales soared 137% to 2.12 million m2 thanks to tenders by Gaz System. Stalprofil participated in these as a consortium partner with subsidiary Izostal.
In 2018 Polish steel consumption rose 9.5% on-year to 14.9 million tonnes, which supported an upward price trend, further boosted by EU trade defence measures, Stalprofil president Jerzy Bernhard says in a report seen by Kallanish.
Revenue increased 30% on-year in 2018 to PLN 1.45 billion ($379.3 million), driven by a 56% surge in the infrastructure segment to PLN 837.86m, while the steel segment rose 7% to PLN 616.9m. Net profit attributable to majority shareholders was up 39% to PLN 28.93m.
Domestic revenue surged 32%, representing 91.6% of 2018 sales, while exports increased 18%, representing 8.4% of sales. This came despite high competition, steel oversupply in the EU and the influx into the EU of cheap steel from the Far East and CIS, Stalprofil says. Exports went mainly to the other Visegrad countries, the Baltic States and Germany. Non-EU European countries, such Ukraine, Russia, Turkey and Norway, represented 11.2% of exports.
ArcelorMittal, meanwhile, supplied 28.9% of Stalprofil’s procurement in 2018, while Corinth Pipeworks represented 13.5%. Gaz-System was Stalprofil’s largest customer, representing 37.6% of sales.
SSAB’s Tibnor completes Danish distributor acquisition
SSAB subsidiary Tibnor has completed the acquisition of the steel distribution business of Denmark’s second-largest steel distributor, Sanistål, Kallanish learns from the Swedish steelmaker.
The acquisition was initially announced last November (see Kallanish passim). The move supports SSAB’s strategic target to strengthen its Nordic home market position. The acquired distribution business recorded sales of around SEK 1.9 billion ($204.4 million) in 2018.
“The acquisition of Sanistål’s steel distribution business completes Tibnor’s Nordic footprint by increasing our market presence in Denmark, where we had not been so visible,” Tibnor Mikael Nyquist said in November. “The product offering of Tibnor and Sanistål complement each other well, and we see substantial synergy potential.”
Based on the acquisition, SSAB and Tibnor expect annual synergies of approximately SEK 50m to be realized within three years.

Globale Stahlnachfrage wächst weiter

Die World Steel Association (worldsteel) hat ihren Short Range Outlook (SRO) für April 2019 veröffentlicht. Darin wird prognostiziert, dass die globale Stahlnachfrage 2019 1.735 Mio. t erreichen wird, was einem Anstieg von 1,3% gegenüber 2018 entspricht. Im Jahr 2020 soll die Nachfrage um 1,0% auf 1.752 Mt. wachsen.
Al Remeithi, Vorsitzender des Weltstahlwirtschaftsausschusses, kommentierte die Aussichten wie folgt: “Für 2019 und 2020 wird erwartet, dass die globale Stahlnachfrage weiter wächst, aber die Wachstumsraten werden sich in Verbindung mit einer sich abschwächenden Weltwirtschaft abschwächen. Die Unsicherheit über das Handelsumfeld und die Volatilität an den Finanzmärkten haben sich noch nicht verringert und könnten zu Abwärtsrisiken für diese Prognose führen.”
Wachstum der Stahlnachfrage bleibt positiv
Im Jahr 2018 stieg die globale Stahlnachfrage um 2,1% und wuchs damit etwas langsamer als 2017. Für 2019 und 2020 wird noch mit einem Wachstum gerechnet, allerdings in einem weniger günstigen wirtschaftlichen Umfeld. Chinas Verlangsamung, eine sich verlangsamende Weltwirtschaft, die Unsicherheit über die Handelspolitik und die politische Situation in vielen Regionen deuten auf eine mögliche Abschwächung des Vertrauens und der Investitionen der Unternehmen hin.
Chinesische Stahlnachfrage bleibt aufgrund staatlicher Impulse robust
Die chinesische Stahlnachfrage verlangsamt sich weiter, da der kombinierte Effekt von wirtschaftlichem Ausgleich und Handelsspannung zu einer Verlangsamung der Investitionen und einer schleppenden Produktionsleistung führt. Staatliche Impulse dämpften die Konjunkturabkühlung im Jahr 2018. Im Jahr 2019 dürfte die Regierung das Niveau der Impulse erhöhen, was die Stahlnachfrage ankurbeln dürfte. Für 2020 wird ein leichter Rückgang der chinesischen Stahlnachfrage prognostiziert, da die Impulseffekte voraussichtlich nachlassen werden.
Die Stahlnachfrage in den Industrieländern reagiert auf ein schwächeres Handelsumfeld. In den Jahren 2017-18 profitierte die Stahlnachfrage in den USA vom starken Wirtschaftswachstum, das von staatlich gelenkten Konjunkturprogrammen getragen wurde, was zu hohem Vertrauen und einem robusten Arbeitsmarkt führte. Im Jahr 2019 dürfte sich das Wachstumsmuster der USA verlangsamen, da die fiskalischen Impulse und eine geldpolitische Normalisierung nachlassen. Daher wird erwartet, dass sich sowohl das Bau- als auch das Produktionswachstum moderat entwickeln werden. Auch die Investitionen in die Öl- und Gasexploration dürften sich verlangsamen, während ein Anstieg der Infrastrukturausgaben nicht zu erwarten ist.
Die Volkswirtschaften der EU sind auch mit dem sich verschlechternden Handelsumfeld und der Unsicherheit über Brexit konfrontiert. Für 2019 wird in den großen EU-Ländern (insbesondere in den exportabhängigeren Ländern) ein langsameres Wachstum der Stahlnachfrage erwartet. Außerdem sollte sich das Wachstum der Stahlnachfrage im Jahr 2020 verbessern, was von einem Abbau der Handelshemmnisse abhängt.

Quelle und Grafik: World Steel Association / Autor: von Alfons Woelfing
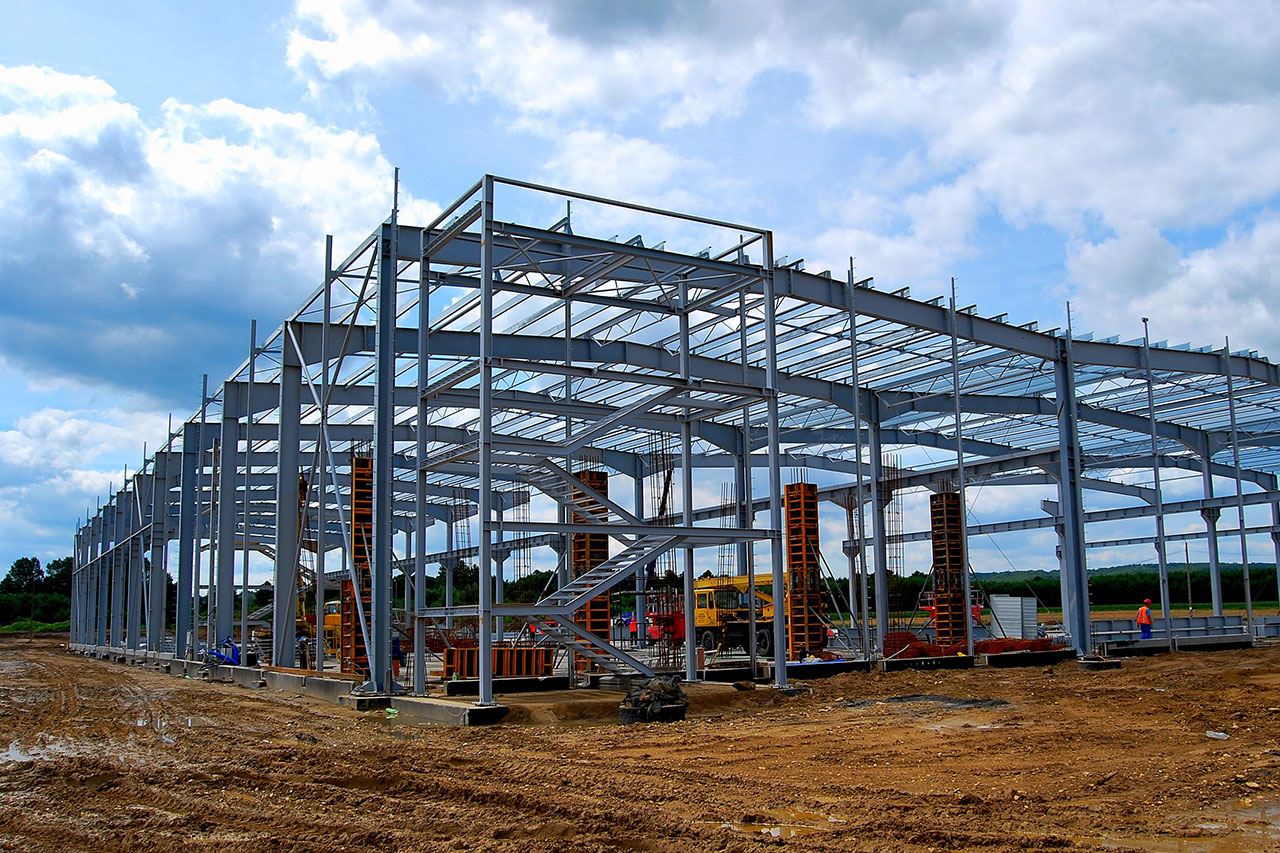
Polish distributor foresees continued demand from construction

Polish distributor Bowim expects domestic construction activity to continue spurring steel demand after hiking its shipments in 2018.
In recent years the launch of numerous previously-delayed investments has revived construction sector activity. The most significant of these are in the rail, road, manufacturing and residential housing sectors. Steel demand from these investments is expected to continue. A large number of these investments do, however, depend on EU funding and could therefore be delayed, Bowim says.
Poland requires an estimated PLN 310 billion ($81.45 billion) of investment into infrastructure by 2020, while €25.8 billion ($29 billion) of the latest €82.5 billion round of EU funding has been allocated to infrastructure.
“In 2019 and the following years Bowim Group’s sales network is expected to expand further, including the opening of a local warehouse network in Poland’s main cities,” the distributor says in a report seen by Kallanish. “The creation of a retail distribution network is to take place through the acquisition of entities, leasing of infrastructure (e.g. warehouses), or construction of new branches.”
Bowim increased consolidated sales 12% on-year in 2018 to 508,012 tonnes. Sheet sales rose 10% to 166,599t, pipe and profile shipments were also up 10% to 106,887t and rebar sales surged 38% to 95,925t. Sales to the steel structures sector retained a 22% share in overall sales, the construction sector’s share rose 2 percentage points to 20% and the trade segment saw share drop 1pp to 18%.
Bowim’s revenue rose 21% on-year in 2018 to PLN 1.37 billion ($359.95 million) but net profit fell -39% to PLN 11.4m due mainly to higher cost of goods sold.
Celsa Huta Ostrowiec took a 12% share in Bowim’s steel procurement in 2018 versus 13% in 2017. Intake from other major supplier CMC Poland fell below 10% and did not therefore require to be reported.
Thyssenkrupp receives funding to test hydrogen in Duisburg
Thyseenkrupp has received a grant from local authorities to test the use of hydrogen in steelmaking, in order to advance the Duisburg site’s transformation into a climate-friendly plant.
In line with similar targets by other European steelmakers, thyssenkrupp is planning to reduce by some 80% its CO2 production by 2050. As part of this process it plans to test the replacement of some of the coal dust used as a reducing agent in the blast furnace by the injection of hydrogen.
“With the use of hydrogen at our blast furnace 9, we continue to work consistently on the conversion of our production processes,” explains Arnd Köfler, production director of thyssenkrupp Steel Europe. “Our goal is almost CO2-neutral steel production. This will be a long and costly process, and we will take another step today. In the first months of this project, we will first test the use of hydrogen in one of 28 blow moulds in a blast furnace. This is an innovation and has not been implemented so far in the industry. We will analyse the results of this test phase to then convert the entire blast furnace in this way in a second phase.”
To confirm its attention to the climate, thyssenkrupp also launched last year its Carbon2Chem project, converting emissions into chemical products used as valuable raw materials.

Network Steel advances with new HDG plant

Network Steel, the Spanish trading and industrial group, has advanced with its plan to start a new galvanising mill for coil in northern Spain. This week the local government recognised the company’s industrial plan as “…strategic”, thereby helping to speed up the investment process.
Thanks to this support local sources believe the mill could be operational as soon as October this year, Kallanish notes.
The new mill will be located in a former wind-power unit purchased from Vestas. It is expected to have a capacity of 520,000 tonnes/year of galvanised coil when it reaches its full potential at the end of 2020. With an investment of €130 million ($146.6m) the new plant will have a pickling line, two cold rolling lines and two galvanising lines.
Network Steel currently controls three production units, Aranda Coated, Santander Coated and Todoaceros, dedicated to the output of coil. The group is also one of the largest traders of steel products in Spain and recently acquired the service centre company Plafesa.

TK moves forward with Duisburg decarbonization plans
ThyssenKrupp has received a grant statement from the North-Rhine Westphalia state government to start decarbonization of steel production at the Duisberg-located producer
The company reconfirmed to Platts its intention to switch to carbon-free steelmaking by 2050, but said the success would still be dependent on various factors.
“With the use of hydrogen at our blast furnace 9, we continue to work consistently on the conversion of our production processes. Our goal is almost CO2-neutral steel production. This will be a long and costly process, and we will take another step today,” said Arnd Köfler, production director of thyssenkrupp Steel Europe.
“In the first months of this project, we will first test the use of hydrogen in one of 28 blow moulds in a blast furnace. This is an innovation and has not been implemented so far in the industry. We will analyze the results of this test phase precisely and then want to convert the entire blast furnace in this way in a second project phase,” adds Köfler. “Theoretically, a savings potential of around 20% CO2 at this point in the production process is possible.”
Gilles Le Van, CEO of Air Liquide Germany, who will provide the hydrogen for the project, said, “Here in Duisburg, a major chapter in industrial development is opening up: the gradual and sustainable de-carbonization of steel production. We are very pleased to be involved in this project.”
The hydrogen project at Duisberg is in cooperation with Air Liquide, In4Climate -– a North-Rhine WestPhalia state government initiative, and BFI -– a non-profit research institute at the Association of German Steel Manufacturers.
ThyssenKrupp Steel Europe announced in January it also plans to invest Eur10 billion in the modernization of its equipment to replace coking coal-based steel production by 2050.
Steelmakers Voestalpine, SSAB and Salzgitter also have schemes in place to go into hydrogen. Voestalpine said previously however it would take at least two decades before the processes can be used on an industrial scale.
— Len Griffin

SSAB supplies plate for record UAE bridge

SSAB Poland-based customer ViaCon has produced the corrugated steel plate used to build a bridge in Ras Al Khaimah, United Arab Emirates. The bridge span, measuring 32.39m, has been designated by the Guinness World Records book as “…the largest metal buried bridge span.”
SSAB’s S500MC steel was used as the basic material to make the corrugated plate at the ViaCon factory in Rydzyna, Poland. The bridge was completed in half the time it would have taken to build a similar bridge made of concrete and will last more than a 100 years, SSAB says.
The Swedish steelmaker recently launched a new grade of hot-rolled high strength flat steel, the so-called Strenx 1100 Plus strip steel.
SSAB’s crude steel production in 2018 increased by 0.4% on-year to 8.028 million tonnes. Shipments were flat at 6.899mt. Annual sales improved by 13.4% to SEK 74,941 million ($8,288m).
Source: Kallanish
Polish distributor expects demand growth despite economic slowdown
Top-three Polish distributor Konsorcjum Stali (KS) expects continued steel demand growth in 2019, despite the forecasted slowdown in economic growth.
Following very strong, 5.1% growth in 2018, Polish economic growth is forecast to slow to 3.6% in 2019 and 3% in 2020. The main factors behind this are falling external demand resulting from global economic uncertainty. Worsening sentiment among entrepreneurs and investors is translating into delayed investment and buying decisions.
2018 saw Polish steel consumption reach 14.8 million tonnes, the highest since 1989, while the Polish Steel Association estimates 2-3% on-year growth in the coming years.
Steel demand in 2019 will also be generated by large investments in the energy sector, the modernisation of the railway network, and infrastructure projects. Also significant will be investments into new rolling stock and shipbuilding.
Overcapacity, however, remains an issue that could depress prices. EU safeguards, introduced in response to US Section 232 measures, “…will unfortunately not fully prevent increased imports and additional steel product supply, which will unfavourably impact the EU and Polish markets,” KS says in a report seen by Kallanish.
KS increased sales 7% on-year in 2018 to 682,000 tonnes. Rebar sales rose 20% to 201,000t and sheet sales were up 7% to 74,000t. Z and G sections sales were flat at 60,000t. Sales of KS-produced or processed products, meanwhile, fell -2% to 236,000t.
KS’s revenue was up 19% in 2018 to PLN 1.83 billion ($483.98 million) but net profit rose only 3% to PLN 43m due to higher cost of goods sold. Domestic sales accounted for 99.45% of revenue, unchanged from 2017.
Celsa Huta Ostrowiec and CMC Poland accounted for 22.04% and 17.5% respectively of KS’ procurement in 2018, each down on-year, with Riva Stahl accounting for 10.04%.