


France’s steel product trade declines in 2025 as exports and imports both fall
According to statistics released by the French Ministry of Economy, Finance and Industry, France’s trade in basic steel products and ferroalloys declined in value terms in 2025 for both exports and imports compared to the previous year.
France’s exports of basic steel products and ferroalloys reached €9.32 billion in 2025, down 3.3 percent year on year. During the same period, exports of steel pipes and tubes amounted to €1.27 billion, decreasing by 0.5 percent compared to 2024. Exports of cold rolled steel bars totaled €428.61 million, remaining stable year on year, while cold rolled steel strip exports reached €652.16 million, falling by 6.6 percent. Cold drawn wire exports stood at €289.36 million, decreasing by 12.2 percent, whereas exports of metal structures and parts increased slightly by 0.5 percent to €908.57 million.
Meanwhile, France’s imports of basic steel products and ferroalloys totaled €8.72 billion in 2025, representing a year-on-year decrease of 8.4 percent. Imports of steel pipes and tubes amounted to €2.03 billion, rising by 1.6 percent compared to the previous year. Cold rolled steel bar imports reached €491.95 million, increasing by 3.1 percent, while imports of cold rolled steel strip totaled €638.29 million, declining by 6.7 percent. Cold drawn wire imports stood at €472.37 million, down by 1.3 percent year on year, and imports of metal structures and parts amounted to €2.5 billion, decreasing by 5.8 percent compared to 2024.


German service centre SSW expands production, storage facilities
German steel service centre Stahl-Service Westerhoff (SSW) is building a new production and storage hall which will triple the size of its operational area.
SSW, located in Ense in the Sauerland region of German state North Rhine-Westphalia, specialises in coated sheet, from basic galvanized to coloured, aluminium-zinc, zinc-magnesium, and other types of layers.
In the zinc-magnesium category, it uses ArvelorMittal’s Magnelis, “which we adopted right when it was launched,” a spokesman says.
The company currently operates a 5,000m² hall with a large cutting facility, a decoiling line, and a precision cutting line by Japanese equipment supplier Amada for bespoke requests. The input material is stored in a 2,500m² hall next door.
The new hall with 15 additional employees will measure 15,000m² to offer a storage and working capacity for 30,000 tonnes of material, a large slitting line and a multi-blanking line.
The start of operations is planned for spring 2027. “A healthy growth over the past years has enabled this investment,” the company says, and adds that it is also streamlining processes, shortening storage and throughput times.
According to the spokesman, this also means a consolidation of contractors it works with. “Our coated strip is normally in thinner gauges, so in case of thicknesses 5mm and up, we have them processed by contractors,” he explains to Kallanish.
SSW handles around 100,000 t/year of sheet. According to local press reports, the investment in the new hall amounts to €35 million ($41m).


Klöckner & Co’s operating income increased in 2025


EU examines short-term measures to reduce industrial energy costs
The European Commission is examining potential short-term measures aimed at reducing energy costs for industry, according to an internal document seen by Reuters.
The analysis focuses on several cost components of industrial electricity prices, including energy taxes, network charges and carbon-related costs, as policymakers seek ways to improve the competitiveness of European manufacturers.
High energy prices weigh on industrial competitiveness
European manufacturers have repeatedly warned that elevated energy prices are undermining their ability to compete with producers in major industrial economies such as China and the US.
The issue has become more pressing following a recent increase in oil and gas prices linked to the conflict involving the US, Israel and Iran, which has added further pressure to global energy markets.
Policy proposals expected before March EU summit
European Commission President Ursula von der Leyen has pledged to present potential policy options ahead of a European Council summit scheduled for March 19.
Discussions among EU leaders are expected to focus on balancing immediate industrial support measures with the bloc’s long-term climate objectives.
Network charges and carbon costs under review
According to the briefing prepared for EU commissioners, Brussels is evaluating various components of industrial electricity bills. Network charges account for approximately 18 percent of industrial electricity costs, while national taxes, levies and carbon costs together represent roughly 11 percent of power expenses. Officials believe targeted adjustments in these areas could help ease cost pressures on energy-intensive industries in the short term.
The Commission also noted that EU member states are not fully utilizing existing mechanisms that could reduce energy costs for companies. These include state aid schemes designed to compensate firms for indirect carbon costs under the EU Emissions Trading System, as well as long-term electricity supply arrangements such as contracts for difference that can provide price stability for industrial consumers.
Demand reduction measures remain a possible option
In addition, policymakers may consider demand-reduction measures if energy supply disruptions intensify. Similar policies were introduced in 2022 when Russian gas deliveries to Europe declined sharply, encouraging both industry and households to reduce energy consumption in response to the supply crisis.

European HRC prices edge higher, with import constraints continuing to drive sentiment
European hot-rolled coil steel prices were slightly higher on Tuesday, with import constraints seen as a major driver behind the uptrend, sources told Fastmarkets on March 10.
Integrated HRC producers in Northern Europe have mainly been offering May delivery coil, Fastmarkets understands. And, amid rising HRC prices, suppliers have started to be more cautious about volume allocations, aiming to avoid over-committing to tonnages and potentially missing out on further price increases, Fastmarkets understands.
In Germany, offers were reported at a base price of €730 ($844) per tonne delivered (equivalent to about €715 per tonne ex-works) from one supplier and at €720 per tonne delivered (around €705 per tonne ex-works) from another.
A third mill was heard offering HRC at €700 per tonne ex-works, in line with recent sales. However, one source told Fastmarkets that the producer had withdrawn the offers on Monday.
In the Benelux region, one local mill was also offering HRC at €700 per tonne ex-works, Fastmarkets understands.
Indications of achievable prices from buyers in the region were heard at €700-710 per tonne ex-works, however, steel-service centers (SSCs) indicated that there were issues with passing on their higher costs to downstream users.
“Our customers need [the HRC price to be] €650-660 [per tonne ex-works]. That’s based on offers for [HR] sheet from people who have cheap material [in stock that] they are now selling, a service center source in the region told Fastmarkets.
“The problem now is that my clients tell me they cannot buy new coil at the current market prices,” the source added.
And a trader source in the region said: “Uncertainty regarding energy has paralyzed everyone. The moves are so sharp; all you can do is watch and see where the dust settles.”
A second trader source said the situation in the Middle East – following the US/Israel attacks on Iran and its wide-ranging response – meant that “trading seems presently to be more dominated by speculation and not driven by demand.”
In the secondary market, meanwhile, 4 mm HR sheet was heard changing hands at €740-750 per tonne CPT in Germany, with new offers heard at €800 per tonne CPT – reflecting the higher feedstock costs. The newer have not been accepted by the market so far, however.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €704.38 per tonne on March 10, up by €2.92 per tonne from €701.46 on Monday.
The index was up by €10.07 per tonne week on week and by €50.21 per tonne month on month.
In Southern Europe, meanwhile, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €687.50 per tonne ex-works on March 10, up by €2.50 per tonne from €685.00 per tonne on March 9.
The index was also up by €7.50 per tonne week on week and by €42.50 per tonne month on month.
Italian steelmakers were maintaining target offers for May delivery HRC at around €700 per tonne ex-works, Fastmarkets understands. One source, however reported an offer at a base price of €700 per tonne delivered, which nets back to around €685 per tonne ex-works.
“We are offering HRC at around €700 per tonne ex-works [because] there are currently no strong grounds to push for higher prices,” a supplier source told Fastmarkets.
Market participants estimated achievable price was around €680-690 per tonne ex-works on Tuesday.
Import activity remained subdued, with market participants reporting only limited fresh offers.
The slowdown was largely attributed to uncertainty surrounding the EU’s revised safeguard measures and the allocation of country-specific quotas. In addition, the unclear cost implications of the Carbon Border Adjustment Mechanism (CBAM) have encouraged buyers to adopt a more cautious approach.
Logistics have also complicated the situation. Due to security risks in the Middle East, many vessels transporting material from Asia to Europe have been forced to reroute via the Cape of Good Hope in South Africa, extending transit times by around two weeks and tightening prompt supplies.
“This week has been very quiet so far in terms on new [HRC] offers,” a trader source in Italy said.
On Tuesday, HRC from Algeria was on offer to Italy at €620 per tonne CFR, sources said.


European Commission confirms CBAM certificate price publishing schedule
The European Commission plans to publish on 7 April the price of Carbon Border Adjustment Mechanism (CBAM) certificates for the first quarter of 2026, Kallanish notes.
Importers of CBAM goods will have to buy CBAM certificates from February 2027 to cover their 2026 imports. For imports from 2027, the Commission will calculate a weekly price for certificates. For imports made in 2026, CBAM certificates will be calculated as the quarterly average of the EU ETS auction clearing prices of allowances.
The price of a quarter will be calculated during the first calendar week of the following quarter, and published on the first working day of the calendar week following the calculation week. Publication will take place both on the European Commission’s CBAM webpage and in the CBAM Registry.
Certificate prices for Q2, Q3 and Q4 2026 will be published on 6 July 2026, 5 October 2026 and 4 January 2027 respectively.
Meanwhile, the call for tenders for the Common Central Platform, which will manage the sale and repurchase of CBAM certificates, is currently open. Interested parties have until 20 March at 12pm to submit their offers.

German steel groups criticise IAA proposals
Germany’s steel association Wirtschaftsvereinigung (WV) Stahl and workers union IG Metall have criticised the Industrial Accelerator Act (IAA) proposal presented by the European Commission last week for failing to implement a general “Buy European” rule.
In contrast to other materials, namely aluminium and concrete, the Commission’s 25%-quota for carbon-reduced materials in public tenders stops short of seeking mandatory European origin for steel as well.
“War and protectionist moves have made Europe’s dependency in strategic regards painfully visible,” says managing director of WV Stahl, Kerstin-Maria Rippel, and IG Metall’s deputy chairman Jurgen Kerner. “Resilience of Europe’s economy is becoming a necessity for security,” they are reported as saying in a guest article in Welt.
The failure of linking the green steel quota to domestic sourcing “means a surrendering of Europe as a producer region,” which ultimately is “a political error of historic dimensions,” they conclude. They clarify that their claim “is not about raising walls, it’s about self-assertion.”
Pointing at the policies of the USA and India, they note that “only a naïve continent refrains voluntarily from linking demand to domestic production, to support its own strength.”
The country’s largest steelmaker, thyssenkrupp Steel, finds that the IAA helps imports more than it helps domestic steel. In its current draft, the proposal greenlights procurement from any overseas region. “That way, we support investment outside of Europe, rather than within,” the company’s ceo, Ilse Jaroni, says in a statement sent to Kallanish.
Meanwhile, the economy minister of state Saarland, Jürgen Brake, has called on the federal government to push the Commission for amendments of the proposal. Federal economy minister Katharina Reiche, too, has expressed criticism of the IAA, but mainly about the bureaucracy it causes. “This is the 50th proposal on domestic content, that comes on top of 49 others, which nobody can oversee anymore,” she is quoted as saying in Welt. She is reserved about requirement of buying European over concerns that it could drive away trusted international trade partners.
The additional bureaucracy that could come with European measures such as the IAA is also of concern to some steel using industries like the German mechanical engineering industry. Its association VDMA also questions local content requirements and warns that these could be an additional burden for its mostly medium-sized machinery builders (see Kallanish 5 March).

Italy scrap weakens amid uncertainty: Assofermet
March is expected to be a weak month for scrap purchasing in Italy. However, the new war scenario in the Middle East, continued weakness in finished steel sales and limited availability of quality scrap are preventing any clear forecast for March, according to a recent note by Italian trade association Assofermet.
The association notes that it will be necessary to closely monitor developments in finished product sales and, above all, production levels amid the prospect of rising energy costs linked to the new US-Iran conflict, for which repercussions remain highly uncertain.
In February, the market started off strong before stabilising later in the month. The first part of the month saw average price increases of around €15/tonne ($17.60/t), confirming the upward trend already observed in January. This pushed domestic scrap sales to high levels, allowing steel mills to cover their raw material requirements.
“Towards the end of the month, limited production schedules, the stagnation of the Turkish market and the further deterioration of the situation in the Middle East partly cooled the market and triggered the risk of further price reductions, which for now have not materialised,” the note states.
In the pig iron segment, there is increasing concern about the lack of alternative supply sources to Russia and Ukraine, which also face very high CBAM costs. At the same time, Brazilian producers are seeking higher prices in the first days of March.
These increases reflect a rapidly evolving geopolitical situation that is inevitably pushing up both energy and insurance costs, Kallanish notes.
“The entry into force of the CBAM regulation, difficulties in understanding the cost calculation mechanism, which varies depending on the origin of the material, and the fact that most steelmakers are already well stocked have weighed on new negotiations. This comes despite some signs of buying interest, particularly for Brazilian pig iron, for which CBAM cost is expected to be lower than that of other sources,” Assofermet concludes.
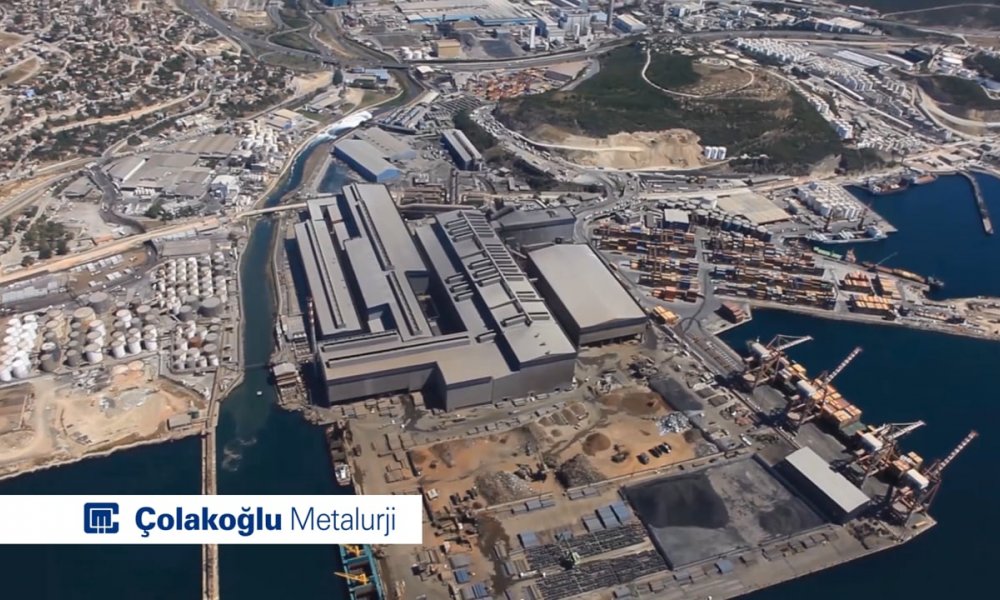
Primetals Technologies modernized Çolakoğlu Metalurji’s electric arc furnace
