


US export bureaucracy hurts German mechanical engineering
The export-driven German machinery manufacturing and mechanical engineering industry is suffering badly from US import restrictions, its association VDMA reports in its latest annual review.
The punitive US tariffs on steel and aluminium will likely affect around 56% of German machinery exports to the US in the near future, Kallanish hears from the federation. According to a new VDMA survey of nearly 400 member companies, 47% of companies report a decline in orders from the US since last April. Two-thirds of respondents expect a drop in sales due to the tariffs.
“What’s more, it’s not just about the absolute level of the tariffs, but also about the associated bureaucratic burden, such as correctly declaring the value of steel and aluminium,” says VDMA president Bertram Kawlath. “Only around a quarter of our companies believe they can meet the American requirements. The tariffs are absolutely counterproductive for both sides!”
In September 2025, German machinery exports amounted to €16.3 billion ($19 billion), marking a 3.4% decline compared to the previous year. Adjusted for price changes, this corresponds to a real decrease of 4.7%. To the USA, exports fell by 10.8% in September. The USA accounts for more than 12% of German exports, rendering it still the largest single foreign market for German mechanical engineering, followed by China with 8% and France with 6%.
As a gentle compensation for the trade issues with the USA, exports to other EU members turned out more favourable than previously assumed. These were still down by 2.2% y-o-y in the first three quarters but have recently gained momentum. To the eurozone, especially, the decline was only 1.1%, VDMA notes.

EU TRQs closing rapidly for Turkish flats, pipe
Turkish flat steel exports to the EU are approaching effective closure for the remainder of the first quarter, with most Q1 volumes already tied up in awaiting allocation.
Pipe product quotas were meanwhile effectively used up within the first working days of the year, Kallanish notes.
By contrast, long products and stainless steel still retain some trading opportunities, according to EU customs portal data.
More than 312,000 tonnes of hot-rolled sheet and strip are currently awaiting allocation, leaving just 81,127 tonnes available, equivalent to 21% of the 393,978t quarterly quota for Türkiye’s largest flat steel category.
Cold-rolled sheet and coated flat products are even tighter, with availability limited to 7% for CR sheet, 9% for metallic-coated sheet and 6% for organic-coated sheet.
Tin mill products are already heavily oversubscribed, with bookings exceeding the quarterly quota by nearly 4,000t.
A similar situation is evident for Turkish pipes and tubes, with gas pipes, hollow sections and large welded tubes all exceeding their quarterly allocations and showing negative availability.
By contrast, long products retain greater availability, with merchant bars and light sections showing 66% quota availability, angles and sections 59%, rebar 40% and wire rod 32%.
Stainless cold-rolled sheet and strip stand out as largely untouched, with 96% of the quarterly quota still available, while railway material remains almost fully open at 99%.
| Product | TRQ volume | Avaliable balance | Awaiting allocation | Avaliable TRQ tonnes | Available TRQ % |
| HR sheets, strips | 393,978 | 393,978 | 312,851 | 81,127 | 21 |
| CR sheets | 43,033 | 43,033 | 39,995 | 3,039 | 7 |
| Metallic coated sheets | 116,832 | 116,832 | 106,183 | 10,649 | 9 |
| Organic coated sheets | 15,559 | 15,559 | 14,669 | 890 | 6 |
| Tin mill products | 7,347 | 7,347 | 11,318 | -3,970 | -54 |
| Stainless CR sheets, strips | 20,620 | 20,620 | 722 | 19,898 | 96 |
| Merchant bars, light section | 104,916 | 104,916 | 35,841 | 69,075 | 66 |
| Rebars | 93,455 | 93,455 | 56,518 | 36,937 | 40 |
| Wire rod | 97,074 | 97,074 | 66,418 | 30,657 | 32 |
| Angles, shapes, sections | 22,395 | 22,395 | 9,251 | 13,143 | 59 |
| Railway material | 1,541 | 1,541 | 23 | 1,518 | 99 |
| Gas pipes | 48,939 | 48,939 | 54,716 | -5,778 | -12 |
| Hollow sections | 83,110 | 83,110 | 111,529 | -28,419 | -34 |
| Large welded tubes | 14,782 | 14,782 | 19,553 | -4,771 | -32 |
| Other welded Pipes | 37,698 | 37,698 | 21,916 | 15,782 | 42 |
Source: EU TARIC, as of 6 January. Complied by Kallanish
Author: Elina Virchenko

Damstahl sees 2026 price surge for Stainless Longs amid CBAM shift
European producers’ stainless steel long products prices could see a boost in 2026, given import restrictions and extra fees caused by the Carbon Border Adjustment Mechanism (CBAM), German distributor Damstahl believes.
The new trade regime projected to take effect from 1 July will see an increase in duty on Asian-origin imports above the quota from 25% to 50%. “This announcement has already caused European importers to turn more to domestic producers, which towards the end of 2025 reported higher order intake and longer lead times,” Damstahl writes in its latest market report.
Under pressure from Asian-origin imported material, European special bar qualities (SBQ) saw a long period of prices at a low level, with little change throughout 2025, Damstahl’s authors write. They expect European mills to push prices up in the second quarter at the latest, and note that some increase has already occurred. For imported material, the firm expects a price increase by 15-20%.
An additional factor possibly causing a shortage for certain bar products this year is that European mills need to ramp up production to meet the redirected demand. This will need a longer period, which Damstahl expects to take 6-8 months, following several years of reduced utilisation.
“The ramp up of the European mills has been assumed in this range since they have reduced their capacities throughout the last two years significantly,” the authors explain to Kallanish.

Pittini revamps southern Italian plant
Italian long steel producer Pittini is investing in revamping its SiderPotenza rolling mill in the south of the country.
With hot start-up scheduled for 2027, the project will improve production efficiency while reducing billet reheating gas consumption and overall CO2 emissions, in line with Pittini Group’s sustainability strategy, Kallanish notes.
Italian equipment maker Danieli was awarded the contract. It explains that the revamp will include a new rolling mill featuring 20 SHS cartridge stands, enabling a billet size increase to 165mm. This configuration is designed to prepare the plant for the installation of a spooler line, initially producing coils of 2.5 tonnes, with provisions for a future upgrade to 5t coils through the addition of a horizontal billet welder (HBW).
The upgraded mill will supply the existing bar line, producing sizes from 2x8mm up to 40mm, as well as a future spooler line for coils ranging from 10mm to 25mm. Safety and working conditions will be improved through advanced design solutions, Danieli notes.
One of the main challenges is carrying out the project within a 45-day shutdown, achieved through customised engineering and extensive pre-assembly to minimise on-site installation and commissioning time, it adds.
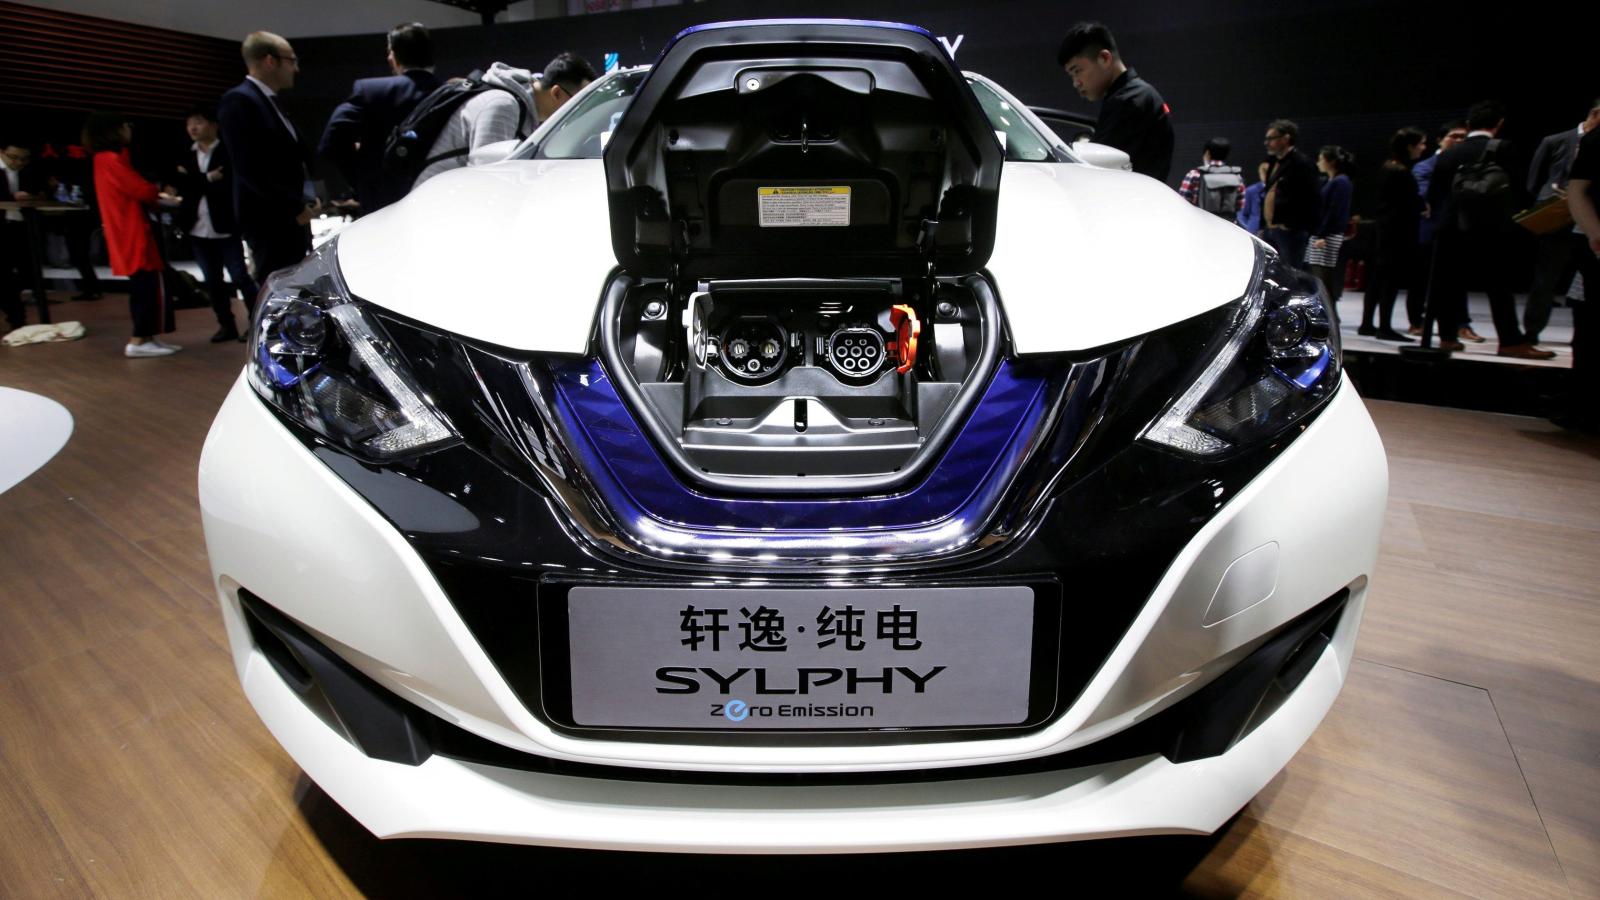
Automakers face Chinese competition, AI integration: Gartner
China’s pace of innovation, simultaneously managing the integration of artificial intelligence (AI), cybersecurity risks, and the complex transition to electric vehicles (EVs), will be major challenges for global carmakers in 2026, says consultancy Gartner, Inc.
The global automotive industry has entered 2026 in an environment of increasing uncertainty, with long-term predictability giving way to volatility. “Beyond 2025, marked by profit warnings, tariff shocks, and slower-than-expected adoption of EVs, the scale and long-term planning are becoming irrelevant due to geopolitical tensions, supply chain instability, and rapid technological change,” the organisation notes.
While many manufacturers see AI as a path to greater agility, Gartner warns of a looming reality check as companies realise their current AI capabilities offer less of a competitive advantage than expected, Kallanish notes.
“The automotive sector is going through a period of euphoria regarding AI, where many companies want to achieve disruptive value even before building solid foundations in artificial intelligence,” says Gartner vice president Pedro Pacheco. “This euphoria will eventually turn into disappointment, as these organisations will not be able to achieve the ambitious goals they have set for AI.”
“China will remain the most complex and crucial market, with experts arguing that success there increasingly determines global leadership,” the consultancy observes. “Strategies such as ‘Made in China, for China’, adopted by groups like Volkswagen and Audi, could become a model for others. Electric vehicles are expected to confidently enter the mainstream in Europe as battery costs fall and smaller, more affordable models emerge, supported by renewed incentives in markets like Germany.”
At the same time, most automakers will reconsider their supply chain reliance on China, even if deep technological interdependence makes complete decoupling unrealistic. Under these circumstances, Gartner concludes that the winners in 2026 will not be large companies, but rather those with agility, speed, and organisational adaptability.
EU’s new steel import quota period makes strong start
Within the first seven days of January, within the new EU quota period between January 1 and March 31 some of the import quotas for certain steel products allocated for India, China, Turkey, and certain countries under the “other countries” category have been exceeded, while over 70 percent of quotas for some steel products have been used up.
Looking at the exceeded quotas, India has exceeded the quotas of 222,829 mt for HRC (1A) and 31,416 mt for stainless bars and light sections, with 289,320 mt and 49,361 mt of the given products respectively waiting at EU ports. The country has also exceeded the quotas of 7,347 mt for tin mill products and 5,955 mt for other welded pipes, with 18,569 mt and 8,206 mt of the given products respectively waiting for customs clearance. China has exhausted its quotas of 126,937 mt for metallic coated sheets (4B), 138,863 mt for merchant bars and light sections, 34,005 mt for other seamless pipes, and 6,929 mt for sheet piling, with 192,566 mt, 192,643 mt, 36,837 mt and 7,123 mt of the given products respectively waiting at EU ports. In addition, the country has also exceeded its quota of 5,504 mt for hollow sections allocated under “other countries”.
Regarding the quotas allocated for Turkey, the country has exceeded its quotas of 83,109 mt for hollow sections, 48,938 mt for gas pipes, and 14,782 mt for large welded tubes (25B), with 111,528 mt, 54,716 mt and 19,553 mt of the given products respectively waiting for customs clearance.
The countries’ EU steel import quota usage over 70 percent can be seen in the table below.
| Product | Country | Quota tonnage (mt) | Used (%) |
|
HRC (1A) |
Turkey | 393,977 | 79.41 |
| Taiwan (under “other countries”) | 110,266 | 71,38 | |
|
CRC |
Turkey (under “other countries”) | 43,033 | 92.94 |
| Vietnam (under “other countries”) | 43,033 | 75.43 | |
| Taiwan (under “other countries”) | 43,033 | 113.22 | |
|
Metallic coated sheets (4A) |
Turkey (under “other countries”) | 116,832 | 90.88 |
| Vietnam (under “other countries”) | 116,832 | 111.21 | |
| Taiwan (under “other countries”) | 116,832 | 74.03 | |
|
Organic coated sheets |
India | 77,805 | 74.7 |
| South Korea | 70,318 | 72.89 | |
| Taiwan | 22,536 | 99.06 | |
| Turkey | 15,559 | 94.28 | |
| Vietnam (under “other countries”) | 10,608 | 156.02 | |
|
Tin mill products |
Taiwan | 13,256 | 96.25 |
| Turkey (under “other countries”) | 7,347 | 154.04 | |
|
Angles and sections |
China (under “other countries”) | 4,912 | 132.39 |
| UAE (under “other countries”) | 4,912 | 89.64 | |
|
Gas pipes |
India | 18,833 | 73.49 |
| UAE (under “other countries”) | 3,298 | 147.76 | |
| Other welded pipes | China | 7,992 | 74.46 |


European domestic HRC market still mostly quiet but mood remains positive
“There is no change in the market as people are coming back,” a trader said, adding that they expect changes in the future with the rollout of new trade regulations.
The EU’s Carbon Border Adjustment Mechanism (CBAM) came into full effect on January 1. This is expected to increase the cost of imported steel products while supporting domestic production.
In Northern Europe, offers for HRC varied within the range of €630-650 ($738-761) per tonne ex-works, depending on the month of delivery and the supplier. The upper end of the range reflected offers for March delivery.
Meanwhile, estimates of workable prices were heard at €630 per tonne ex-works.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was €631 per tonne on Wednesday, up by €1 per tonne since Tuesday January 6.
The index was up by €3.50 per tonne week on week and by €8.50 per tonne month on month.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €624 per tonne on Wednesday, up by €0.88 per tonne since Tuesday.
The index was up by €0.88 per tonne week on week and by €10.67 per tonne month on month.
Estimates of workable levels were heard within the range of €610-620 per tonne ex-works, while offers were reported within the range of €630-640 per tonne ex-works.


New EU Steel Quota period kicks off with several products already full
The new quota period in the EU has started as of January 1. Although the volumes awaiting at the ports are not cleared through customs yet, given the high volumes of imports waiting at the ports, for some products, the quota volumes have already been exhausted.
In the table below, you can see the products for which quotas have already been exhausted and also those for which more than 70 percent of quotas have been used up.


Austria supports machine learning research at steelmakers
Johannes-Keppler-Universität Linz is launching a research series on machine learning and signal processing in steelmaking, together with voestalpine Stahl, Kallanish notes.
The project at the University’s Christian Doppler Laboratory for Signal Processing and Machine Learning in the Steel Industry (CD) institute will run until 2032. It has been endowed with €2.7 million ($3.2m) by Austria’s Federal Ministry of Economy, Energy and Tourism.
The laboratory will work on the development of theoretical principles and algorithms to improve signal processing for monitoring steel manufacturing processes for the next few years.
“Production processes – such as those at voestalpine Stahl GmbH – are monitored by sensors whose signals are processed by specialised algorithms,” says project head Oliver Lang. He explains there are various kinds of signals. “One type of signal that occurs frequently are so-called approximate periodic signals,” he identifies as one example. “There has been very little research on these signals in the past and we only have very few algorithms that are able to process them.”
The reason these occur rather often at strip mills is because of the many continuous processes involved, Kallanish understands. “The rotations and oscillations create these almost periodic signals, but they also cause a lot of critical interfering signals,” Lang concludes.

UK’s TRA removes Vietnam’s rebar quota exemption
The UK’s Trade Remedies Authority (TRA) has removed Vietnam’s exemption from the tariff-rate quota (TRQ) for rebar imports following a review, Kallanish learns from a published government notice.
The category 13 steel products are defined by commodity codes 72142000 and 72149910. The review was initiated on 10 November 2025 after an application was lodged by UK steel producer 7 STEEL UK on the grounds of a substantial change in circumstances. The application indicated that imports from Vietnam of rebar may have surpassed the threshold for exceptions for developing countries.
According to UK regulations, imports from developing country members of the World Trade Organisation (WTO) that account for 3% or less of total imports into the UK should be exempt from TRQs.
The period of investigation (POI) for the review to assess the change in circumstances was 1 October 2024 to 30 September 2025. It found Vietnam had shipped 21,184 tonnes during this period, accounting for 5.535% of imports. The representative period for assessing traditional trade flows was 2017 to 2019.
The TRA recommended to the Secretary of State of Business and Trade that the TRQ should be altered so that rebar imports from Vietnam are no longer excepted from the application of the safeguard measure, and should now have access to the residual quota.
The updated tariff-rate quota applies from 1 January 2026 to 30 June 2026. The residual quota will have 23,514t available for the current quarter, with the 20% cap for any individual exporting country set at 4,703t.
The update also confirms that Ukraine continues to be suspended from the safeguarding measure.
Author: Carrie Bone UK
