

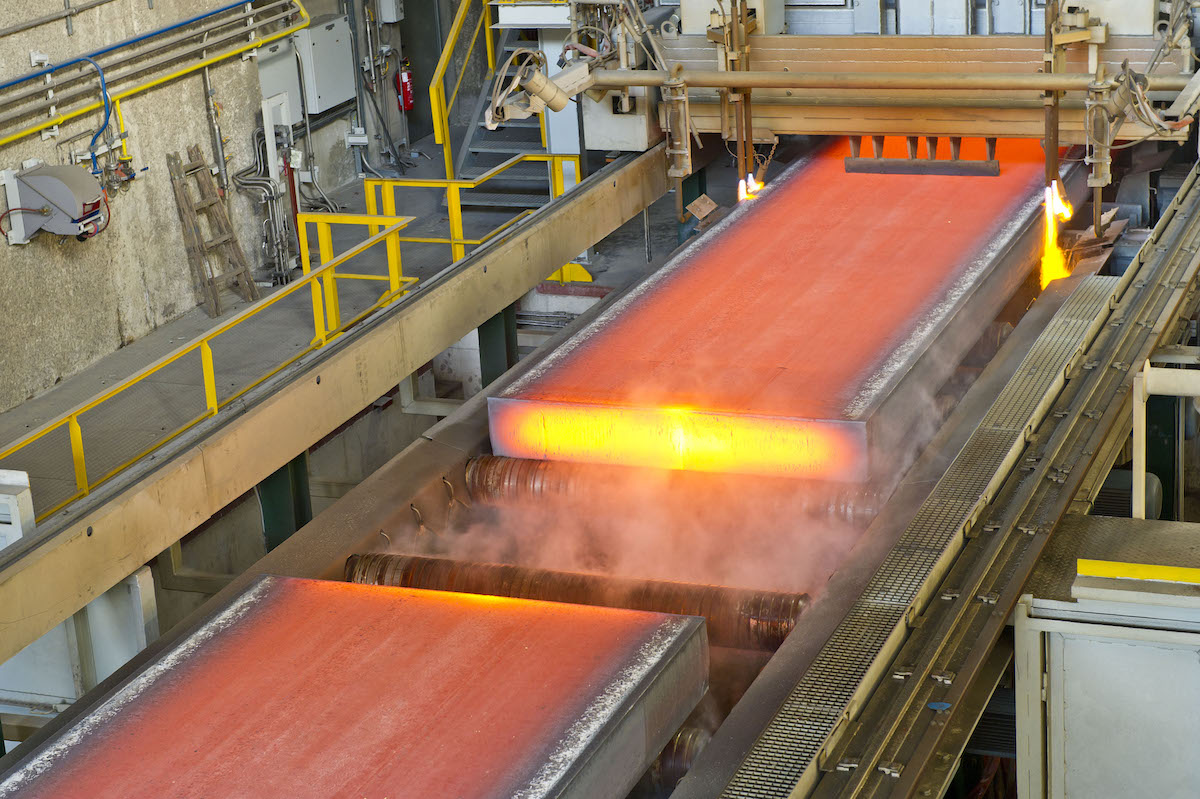
3 things that will change for global steel markets next year & 3 that won’t
1) Adoption of green steel will pick up pace
Demand for green steel in Europe and Asia is expected to increase and even accelerate following commitments made by governments and steelmakers to decarbonize the sector.
One area of growing focus is the development of low-carbon technologies, which have been backed by strong support from public and private stakeholders through investments. The expected shift will include further capital available from banks/lenders, as people search for standard lending practices and more definitive methods of quantifying and testing a company’s drive toward lower-emission steel.
Such investments have already allowed steelmakers to explore commercially viable technologies and reliable sources of clean energy, such as scrap steel or natural gas-based direct reduced iron, and shift to electric-arc furnace steelmaking, which is less carbon intensive compared with the blast furnace route.
Meanwhile, the EU’s Carbon Border Adjustment Mechanism’s (CBAM) January 31, 2024 deadline for reporting is looming over the markets.
2) China’s steel consumption patterns to continue shifting
The traditional industries that consume steel in China are likely to continue changing, reducing the industry’s previously huge reliance on property and focusing on manufacturing and new infrastructure.
Output of medium-thick and wide steel strip, coated plate, welded pipe, hot-rolled narrow strip, heavy plate, seamless pipe, large-scale steel structure, electrical steel and other types of steel products had seen rapid growth in 2023 thanks to growing demand from new infrastructure, new energy and manufacturing industries such as automobiles, shipbuilding and home appliances. This has offset the demand loss from the ailing property sector, the China Iron & Steel Association said.
Steel consumption in the traditional construction sector is unlikely to maintain as high growth as previous years, while demand from new infrastructure and high-end manufacturing is set to see strong growth, market participants said.
Official data shows that investment in China’s property development dropped by 9.3% year on year in the first 10 months of 2023, while new housing starts measured by floor area tumbled by 23.2%.
During the same period, China’s completed investments in power supply projects jumped by 41.5% in terms of nuclear power, 42.5% for wind power and 71.2% for solar power. The country’s production and sales of new energy vehicles increased by 34.5% and 36.7% year on year respectively in January-November 2023.
3) Turkey HRC import volumes could decrease
Turkey’s hot-rolled coil imports are expected to decrease because of the anti-dumping investigation for HRC imports from China, India, Japan and Russia that started on October 31.
Turkish holders of the inward processing regime certificate are not subject to the duties on the condition that they export their end products. Most flat steel re-rollers used to use their certification for imports of HRC. But because demand has been weak at export markets and export tonnages have been very low, most companies cannot meet the targets to be eligible to get the certificates, market participants told Fastmarkets.
Three things that won’t change:
1) China’s bearish outlook on property market
Market participants expect the Chinese real estate market to continue weighing on steel demand in 2024, especially for rebar, amid continued concerns over property developers’ debt ratio and the eroding investment value of houses.
“The slow recovery of new house sales, sharp reduction in land transactions in the past two years, and high house inventory may continue to slow the start of new construction projects in 2024,” an industry analyst said.
Property developers’ investments into new projects totaled 9.59 trillion yuan ($1.35 trillion) in the first 10 months of 2023, down by 9.3% year on year, according to China’s National Bureau of Statistics.
Market participants do not expect property developers to increase their investment values in 2024.
Steel mills that can produce both flat steel and long steel will restrict the production of long steel but raise that of flat steel, as some of them did in 2023, sources said.
Despite various cities in China having loosened their housing policies, it takes time for investors and house buyers to regain confidence in the property market, acquiring new land for construction and eventually boosting steel demand, market sources said.
2) Uncertainty around downstream demand for ferro-alloys
Concerns about uncertain downstream demand will likely continue to dominate ferro-alloys markets, even as steel producers face their own ongoing uncertainty around their input costs, against a challenging macroeconomic backdrop.
Market participants expect the economic downturn to persist at least into the first quarter of 2024, and likely beyond, with areas such as construction and the automotive continuing to face contraction.
Hand-to-mouth buying by steelmakers will continue to restrict opportunities for small and medium-sized ferro-alloys traders who have been left reliant on back-to-back business due to high trade finance costs amid high interest rates.
3) GCC likely to continue as a net importer of flat steel
Gulf Co-operation Council (GCC) countries will likely continue to be net importers of flat steel next year.
Although the group of countries is mostly likely to have excess steelmaking capacity by 2025 onwards, with huge investment already pumped into future green steel capacity, new capacities are unlikely to start production in 2024. This will leave them still relying mainly on its traditional sources: China, India, Japan, South Korea and Taiwan for the time being.


Tubos Reunidos names Josu Calvo president
Spanish special seamless tube supplier Tubos Reunidos (TR) has appointed a new president, Kallanish learns from the company.
Josu Calvo Moreira becomes a non-executive president. He will replace Francisco Irazusta, who leaves the company after three years at the position.
“Moreira will not have executive functions at TR and will maintain his current position as ceo of Gonvarri Industries, combining this responsibility with the leadership of the board of the group as non-executive president, ” TR confirms.
Carlos López de las Heras becomes the company’s the new chief executive.
Todor Kirkov Bulgaria

Biden administration pledges to scrutinise USS sale
The director of the US National Economic Council, Lael Brainard, says President Joe Biden’s administration will review the proposed sale of US Steel to Nippon Steel, Kallanish learns.
“The purchase of this iconic American-owned company by a foreign entity—even one from a close ally—appears to deserve serious scrutiny in terms of its potential impact on national security and supply chain reliability,” states Brainard.
The United Steelworkers union is expressing its support for a review by federal authorities.
“The USW welcomes Brainard’s statement and the administration’s assessment that the announced sale of US Steel to Japanese-owned Nippon Steel deserves ’serious scrutiny’ to determine its larger implications for our national security and critical supply chains,” says David McCall, USW’s international president, in the union’s official statement.
Brainard highlights Biden’s efforts to thwart unfair practices in the international steel trade on behalf of US producers. She credits the USW with helping to support these measures.
“President Biden has taken action to protect the US steel companies against unfair and market-distorting trade practices in China and other countries. The USW has been a leader in all of these efforts, and are an example of why union leadership is critical in building the economy from the middle out and bottom up,” notes Brainard.
The USW statement applauds the White House’s support for the USW workers.
“Brainard also rightly highlighted the continuing role that the steel industry and its workforce play in safeguarding our nation, and we agree that our nation’s security interests must remain paramount. The USW appreciates that the White House is taking a larger view, demonstrating once again the president’s unwavering commitment to domestic workers and industries,” McCall emphasises.
Kristen DiLandro USA
Klöckner & Co intends to sell 4 EU country organizations to strengthen focus on higher value-added business and streamline portfolio
- Company has received an irrevocable offer by Hierros Añon S.A. regarding the acquisition of the country organizations in France, the United Kingdom, the Netherlands, and Belgium
- Strengthening focus on higher value-added business while reducing exposure to volatile and low-margin commodity distribution business
- Regional focus on North America and DACH region going forward
Klöckner & Co intends to sell parts of its European commodity distribution business. In this regard, the company has received an irrevocable offer by the Spanish Hierros Añon S.A. today that comprises all relevant terms and conditions regarding an acquisition of the country organizations in France, the United Kingdom, the Netherlands, and Belgium.
With the proposed transaction, the Management Board of Klöckner & Co would continue to prioritize businesses with higher value-added products and services along the value chain of its customers like processing and fabrication services. These offers have higher profitability and more stable demand due to the long-term contractual relationships and strong customization associated with the higher value-added business. The proposed sale would significantly reduce the company’s dependence on volatile commodity markets. Going forward, Klöckner & Co will continue to concentrate on the growth of its biggest market in North America and its attractive European activities in Germany, Austria, and Switzerland (DACH).
Guido Kerkhoff, CEO of Klöckner & Co SE: “Selling parts of our European commodity distribution business would be a major milestone to focus on the less volatile higher value-added business. This is in line with previous achievements such as our recent acquisitions which significantly contribute to this business model and portfolio optimization. In addition, the proposed sale would instantly and sustainably improve our profitability and thus enable further growth in the future.”
The country organizations in France, the United Kingdom, the Netherlands, and Belgium employ around 1,500 people as of September 30, 2023. In the first nine months of 2023, these businesses collectively contributed €621 million in sales, representing about 10% of Klöckner & Co’s total sales volume. In the same reporting period, EBITDA before material special effects reached a negative €19 million and total assets of around €552 million.
The proposed transaction is expected to have a considerably positive impact on the Group EBITDA before material special effects from the financial year 2024 onwards. In addition, the company expects a one-time negative effect on the Group equity of around €210 million based on the current equity of the organizations and further deconsolidation effects. However, the equity ratio of the remaining Group is expected to increase to approximately 51%. In addition, Klöckner & Co would generate over 50% of its sales in North America after a closing.
The proposed transaction is subject to information and consultation procedures with the relevant employee representative bodies, as well as the customary regulatory approvals and closing conditions. Closing, after an acceptance of the irrevocable offer, is expected to take place in the first half of 2024.
Klöckner & Co is one of the largest producer-independent distributors of steel and metal products and one of the leading steel service companies worldwide. Based on its distribution and service network of around 160 sites in 13 countries, Klöckner & Co supplies more than 90,000 customers. Currently, the Group has around 7,800 employees. Klöckner & Co had sales of some €9.4 billion in fiscal year 2022. With the expansion of its portfolio of CO2-reduced materials, services and logistics options under the Nexigen® umbrella brand, the company is underscoring its role as a pioneer of a sustainable steel industry. At the same time, Klöckner & Co leads the way in the steel industry’s digital transformation and has set itself the target of digitalizing and largely automating its supply and service chain. In this way, the Company aims to develop into the leading one-stop shop for steel, other materials, equipment and processing services in Europe and the Americas.
The shares of Klöckner & Co SE are admitted to trading on the regulated market segment (Regulierter Markt) of the Frankfurt Stock Exchange (Frankfurter Wertpapierbörse) with further post-admission obligations (Prime Standard). Klöckner & Co shares are listed in the SDAX® index of Deutsche Börse.
Source: kloeckner.com

Acciaierie Venete to buy Ascometal’s French facilities
Italian longs producer Acciaierie Venete has agreed to acquire three facilities in France from special steel producer Ascometal, part of Swiss Steel, the companies reveal.
The Italian steelmakers started negotiations to buy the plants of Hagondange in the department of Moselle, Custines in Meurthe-et-Moselle, Le Marais in the Loire region, and the Ascometal research centre Creas. The move is in line with Acciaierie Venete’s ambition to boost its presence in Europe.
“The French project will allow Acciaierie Venete to consolidate its position and increase its production capacity outside Italy. The move will give the sites a stable future with the support of a shareholder with a sound balance sheet and strong industrial experience. The group, with an ambitious investment plan for the acquired facilities, will allow several synergies, particularly in the field of purchases,” the steelmaker says in a note obtained by Kallanish.
The firm will submit its growth plan to the unions and other stakeholders in the coming months, Kallanish understands. The completion of the merger is expected in the spring of 2024.
“Swiss Steel Group is pleased that Ascometal France Holding has found a reliable and experienced partner in Acciaierie Venete, with industrial synergies, boasting an ambitious plan to strengthen the Asco-metal plants of Hagondange, Custines and Le Marais,” Swiss Steel says. It adds that the divestment is in line with its strategy to focus on core business activities.
“The transaction would allow Swiss Steel Group to strategically channel its investments into areas that promise sustained growth in alignment with its long-term vision and strengthening other production assets such as the French Ugitech,” the company adds.
The remaining two Ascometal plants, Les Dunes in Dunkirk and Fos-sur-Mer, are not included in the merger.
Ascometal produces blooms and billets as well as cold and hot rolled bars and wire rod. Acciaierie Venete produces merchant bar, round bars, billets across three production facilities in Padua, Sarezzo and Borgo Valsugana. it is expanding its product portfolio at its plant in Sarezzo where it will start manufacturing wire rod.
Natalia Capra France

Buhlmann acquires pipe support systems supplier
German pipe distribution and processing group Buhlmann says it will take over Ligesa, specialist in industrial pipe support systems, with effect from 1 January 2024.
Founded in 1964 and headquartered in Zeven in northern Germany, family-owned Ligesa is a leading supplier of industrial pipe support systems and vibration control technology, Kallanish hears from Buhlmann.
It highlights the acquisition as “a special milestone for us because we are expanding our portfolio in the best possible way and entering the field of in-house production”. With a staff of around 1,000, Ligesa operates seven production sites and is active in 80 countries.
Buhlmann Group describes itself as an internationally active trading company for steel pipe, pipe connections, fittings and other accessories, family-owned since its foundation in 1945. Its 65,000-tonne product range includes welded and seamless steel pipe, fittings, flanges and valves for use in demanding environments such as chemical and plant engineering, the oil and gas industry and offshore applications. It employs over 750 people in 16 countries and in the last financial year posted revenue of €457 million ($501m).
Christian Koehl Germany
Acerinox joins AI technology development project in Spain
Acerinox has joined Spanish data economy and artificial intelligence consortium IndesIA, the stainless steel producer tells Kallanish.
Its participation shows the company’s interest in leading digitalisation in industrial processes and promoting the use of data and artificial intelligence to improve and transition to new business models, Acerinox says. It also confirms its commitment to AI technology to improve its process optimisation, energy efficiency, predictive maintenance and new product creation, it adds.
“This alliance will help improve competitiveness through automation and optimisation of industrial processes while offering us scalability in terms of data use and AI,” says Acerinox chief executive Bernardo Velazquez. “Thanks to this technology, we will continue to advance in the identification of sustainable models for efficient resource use and in reinforcing the circular economy, an area in which we serve as a role model.”
Members of IndesIA include Gestamp, Navantia, Técnicas Reunidas, Repsol, Telefónica, Microsoft, Airbus, Ferrovial, and Inditex, among other companies.
Todor Kirkov Bulgaria

Italian coil trade goes quiet amid high prices
Italian cold rolled and hot-dipped galvanised coil prices are flattening this week amid slowing trade as the market approaches winter holiday stoppages at the end of this week. Despite the short month, demand has been dynamic, particularly until last week, market sources tell Kallanish.
HDG and CRC asking prices are now at €800/tonne ($875) base ex-works. Italian HDG is fetching €780-800/t base ex-works and some €10-20/t less for CRC, sources suggest. Italian suppliers have sold good volumes on the export market this month at €830-850/t delivered in France and Germany.
There is uncertainty that prices will remain high for second-quarter delivery. A seller says it is quite difficult to shift volumes at the current high values. European producers’ intention is to continue to push up values in January considering the lack of imports. A trader believes that if steelmakers increase prices too much in the new year, the market will stall and buyers will turn to imports. Demand downstream continues to be limited.
CRC supply has been strongly reduced after one local steelmaker stopped producing it. The void is being filled by Asian offers into Europe. Some import transactions from Asian countries took place this month at €710-720/t cfr Italy, Kallanish notes.
Meanwhile, ArcelorMittal is further increasing its quotes for hot rolled coil across Europe (see Kallanish 20 December newsletter). This week, sources in the market are reporting that the mill is offering HRC for the German market at €750/t ex-works. In the Italian market, offers are at €740/t ex works.
The latest quotes indicate an increase of some €20-30/t from the previous levels tabled at the beginning of December. However, transaction prices were lagging €20-30/t behind offer levels before the latest hike.
Natalia Capra France

ArcelorMittal starts using bio-coal converted from wood in Ghent blast furnace
ArcelorMittal has commissioned its Torero plant converting waste wood into bio-coal for use in the blast furnace at its Ghent steelmaking site, the company said Dec. 20.
The first bio-coal made in the Torero plant, through a process called torrefaction, was used in a blast furnace in Ghent Dec. 18 for the first time.
According to ArcelorMittal, the project will reduce annual carbon emissions from the plant by 112,500 mt, reducing the use of fossil coal in the blast furnace.
The Torero plant was expected to convert 88,000 mt of waste wood into 37,500 mt of bio-coal annually.
The produced bio-gas during the blast furnace process is being transformed into ethanol. The ethanol can then be used as a building block to produce a variety of chemical products.
The European Commission approved Eur280 million ($308 million) under EU State aid rules in June to support ArcelorMittal Belgium partially decarbonizing its steel production in Ghent, where it operates two blast furnaces.
The aid, which will take the form of a direct grant and a soft loan, will support the construction of a direct reduction iron plant and of a new electric arc furnace that will substitute one of the two existing blast furnaces.
Natural gas, initially used in the energy mix, will be gradually phased out with the plant that will ultimately be operated using renewable hydrogen.
Platts, part of S&P Global Commodity Insights, assessed North European hot-rolled coil at Eur690/mt EXW Ruhr Dec. 19, up Eur30/mt month on month. The carbon-accounted steel premium for lower carbon emission hot-rolled coil produced in Europe was assessed at Eur110/mt, up Eur10/mt on the month.
Author Laura Varriale


European HRC producers aim for substantial rises in Q1 2024, subdued demand seen as major concern
European hot-rolled coil producers are seeking substantial price increases for the first quarter of 2024, but slow consumption remains the biggest concern, sources told Fastmarkets on Wednesday December 20.
Integrated steelmakers in Northern Europe are targeting €720-750 ($788-821) per tonne ex-works for February-March delivery HRC, Fastmarkets heard.
But those values are yet to be sealed in deals because tradeable values indicated by buyers are around €680-700 per tonne ex-works, with transactions reported within that range in December.
Sources reported several bookings during the week within the range of €680-700 per tonne ex-works for February delivery, but largely for small tonnages.
Northern European integrated mills were said to be largely sold out for February-delivery material, but sources suggested they might still have free volumes for the spot market.
“Mills claim they are booked, taking into consideration tonnages they reserved for automotive industry. In the case that the automotive industry books less, some [HRC] tonnages will be released for spot trading in January-February,” a distributor in the region told Fastmarkets.
Fastmarkets calculated its daily steel HRC index domestic, exw Northern Europe at €695.13 per tonne on Wednesday, up by €4.71 per tonne from €690.42 per tonne on Tuesday.
The index was up by €7.00 per tonne week on week and by €40.13 per tonne month on month.
In Southern Europe, Fastmarkets calculated its corresponding daily steel HRC index domestic, exw Italy at €688.33 per tonne on Wednesday, increasing by €2.08 per tonne from €686.25 per tonne on Tuesday.
The Italian index was up by €13.75 per tonne week on week and up by €53.33 per tonne month on month.
During the second half of December, €700 per tonne delivered (€680-690 ex-works) was largely achieved in deals for HRC in the nation, sources said.
New offers from Italian steelmakers for February-March delivery HRC stood at €720-730 per tonne delivered, while one European steelmaker was offering coil to the nation at €740 per tonne delivered.
On Wednesday, trading was close to zero in Italy due to the seasonal slowdown, but most sources suggested that new target prices for HRC will be achieved in Italy after the Christmas break.
“We don’t have that many buying options given all limitations in place for imports. And output is reduced at the EU mills so buyers will have to pay,” a trading source in Italy told Fastmarkets.
“Slow consumption remains the major concern for the market. We expect end-user demand in 2024 to be 10-15% below the 2023 levels,” he added.
In the secondary market, HR sheet was traded around €770-780 per tonne CPT during the week to Wednesday, but steel service centers said they need to increase downstream prices by “at least €50 per tonne” due to mounting costs.
Import HRC offers to Europe have been very limited recently.
Several sources reported a booking of a large HRC tonnage of India origin to Italy around €640-645 per tonne CFR for February shipment. The booking was reportedly done at the end of the previous week.
On Wednesday, offers from Indian mills to Europe were heard at €650 per tonne CFR minimum.
Turkey-origin HRC with February shipment was offered to Italy at €695 per tonne CFR, including the anti-dumping duty. This level was deemed too high by EU buyers.
