

Polish demand falters, alternative origins replace Russian imports
Polish steel consumption saw a big drop in 2022. Although imports from Russia fell significantly amid sanctions, intake from countries that have not sanctioned Russia rose sharply, Polish Steel Association (HIPH) chief executive Mirosław Motyka pointed out at an industry event on Wednesday.
Poland, which for many years stood out with steel production and consumption growth while other EU countries reported declines, has now also joined the downtrend. Crude steel output and apparent steel consumption fell 14% and 12% respectively on-year in 2022. The latter was at 13.3 million tonnes after record use of 15.3mt in 2021.
Despite non-EU-origin imports falling 27% on-year in 2022 to 3.06mt, imports took a larger share in demand, resulting in the loss of $6 billion of local steel production, enough to invest in a small modular reactor, Motyka said at the European Economic Congress in Katowice attended by Kallanish.
Although Russia-origin steel imports fell to 467,000t in 2022 from 1.63mt in 2021, intake increased from China, Turkey, India and Indonesia. These countries still import steel from Russia, resulting in a form of EU sanctions circumvention, Motyka suggested. Interestingly, Serbia, which also does not levy Russia sanctions, became Poland’s fourth-largest non-EU steel supplier last year with 194,000t.
At the same time, Polish steel demand is dropping amid a “crisis” in the residential housing industry, Motyka observed. The construction sector overall accounted for 42% of Polish apparent steel consumption in 2022.
Polish steel distributor association PUDS’s ceo Iwona Dybał meanwhile said steel inventories have been at low levels since last July and there are no signs of restocking, meaning her sector does not expect a demand rebound. Last December, Polish consumption fell to a record monthly low below 700,000t.
However, asked if the war has seen Ukraine increase steel supply to Poland, Dybał said Ukraine’s steel production was only 6.3mt last year, with around 600,000t of exports to Poland versus 1.2mt a year earlier. EU safeguards on Ukraine are suspended, but imports have anyway been nowhere close to reaching the thresholds. “If there were safeguards and no war, there would probably be more Ukrainian steel coming to Poland – so Ukrainian steel is not flooding the Polish market,” she commented.
Stalprofil ceo Henryk Orczykowski agreed demand has dropped since last July amid a lack of public and private investment. He foresees the second and third quarters remaining difficult and said distributors are counting on the unblocking of EU funds to spur demand from investment projects.
Adam Smith Poland

Ayhan Uçar: New capacity investments may halve Turkey’s flats imports
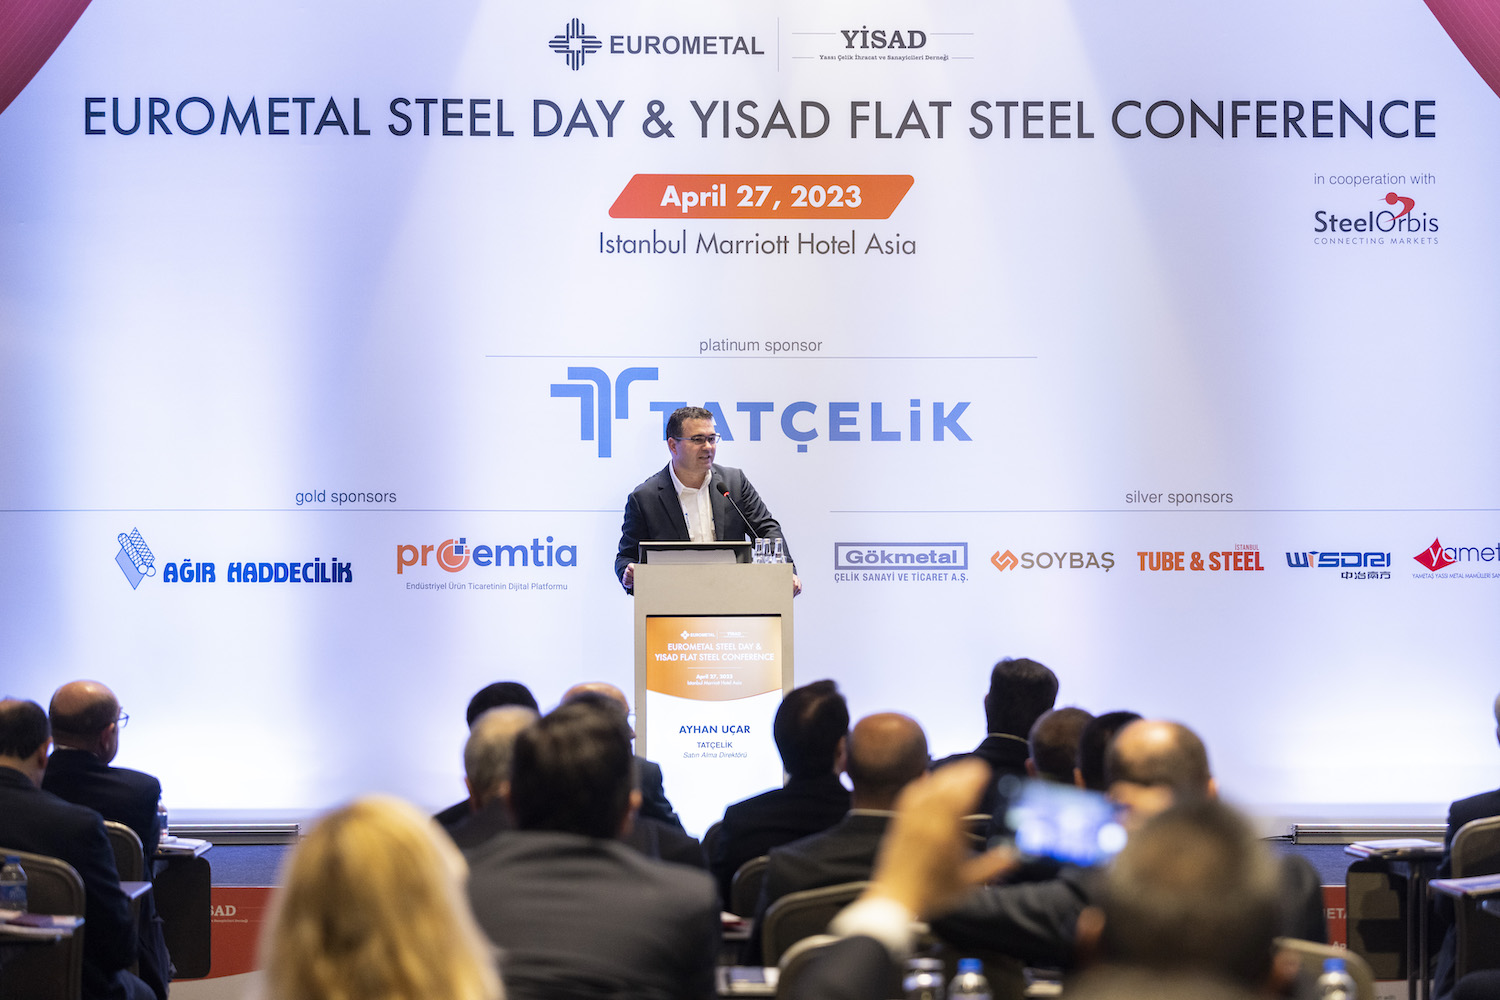
According to Mr. Uçar, speaking at the EUROMETAL Steel Day & YISAD Flat Steel Conference held at Istanbul, having increased its capacity by between two- and three-fold in the last five years, Tatçelik now has a total annual rolling capacity of 1.5 million mt at its three plants. He stated that, in line with the company’s goal of increasing value-added product investments, its capacity will increase by 650,000 mt with its new galvanizing line investment. He added that Tatçelik exports to more than 70 countries, primarily to Europe and North Africa, and that they will continue to expand their export markets. In addition, Mr. Uçar added that, based on the result of the antidumping duty review for galvanized steel in Europe, Tatçelik is subject to the lowest duty rate among Turkish producers, with a 2.4 percent rate.
Recalling that the Turkish steel industry ranked eighth in the world steel production in 2022, Uçar stated that the steel production capacity in Turkey is unable to compete with the Asian market in the current market conditions, though the country can regain its competitiveness when flat steel investments are implemented and when the pressure from energy costs eases. While the Turkish steel industry has sufficient capacity for long products, Uçar said that Turkey may halve its steel flat steel imports in the coming years with new flat product investments. Pointing out that the gap between domestic and import HRC prices is currently wide, he said that the price gap in question may increase slightly when the new import tax comes into effect in May. In addition, noting that the duty rates to be applied on HRC and coated steel are same, he stated that the duty for coated steel must be higher in regards to added-value.
Meanwhile, the Tatçelik official stated that global steel consumption is expected to increase by approximately 150 million mt in the next 25 years as the world’s population increases, especially in Asia and Africa, and that new investments are needed to meet the higher demand.

Steel industry representatives meet at EUROMETAL & YISAD Steel Conference in Istanbul

At the EUROMETAL Steel Day & YISAD Flat Steel Conference, which held at Istanbul Marriott Hotel Asia on Thursday, April 27, in cooperation with SteelOrbis and with nearly 300 participants, Metin Tayfun İşeri, chairman of Turkey’s Association of Flat Steel Exporters and Manufacturers (YISAD), and EUROMETAL board member Alexander Julius made the opening speeches.
Tayfun İşeri stated that for the last four to five years efforts have been made to raise the international standing of this annual conference, which is this year being held for the eighth time, and that this year marks the conference’s first collaboration with EUROMETAL.

In his presentation, Alexander Julius informed the participants about EUROMETAL’s services. Stating that 18 European national federations of steel distributors, 50 individual distributors and service centers, and 25 steel trading companies come together under the umbrella of EUROMETAL, he said that the company represents approximately 3,500 companies and 100,000 employees.
Mr. Julius also said that, while Turkey is becoming an increasingly important player for the global steel industry with its imports, it should also be active in exports due to its increasing production capacities.

In this context, he stated that they are working to develop cooperation between European manufacturers and Turkish manufacturers, and that these two regions cannot be considered separately from each other in terms of commerce due to Turkey’s geographical location.
Julius added that, as EUROMETAL, they cover the entire supply chain and have drawn a clear framework for the steel industry as a result of sharing information with their members.

Turkish flat steel market seeks solutions amid lackluster demand
During the panel moderated by SteelOrbis general manager Murat Eryılmaz at the EUROMETAL Steel Day & YISAD Flat Steel Conference held at Istanbul Marriott Hotel Asia on Thursday, April 27, the current situation and future expectations for the Turkish flat steel market were discussed.
In his speech, Kerem Çakır, chairman of the Association of Cold Rolled, Galvanized and Coated Coil Manufacturers (SOGAD) in Turkey and general manager of Borçelik, stated that regional protectionism, energy prices and the supply-demand balance have triggered fluctuations in the market, while Turkey has remained outside of the EU and the US markets. According to Mr. Çakır, Turkey must reach an agreement with the EU and the US within the scope of the EU quotas and US Section 232 measures as these are the most important markets for Turkey in terms of competition. Regarding galvanized steel capacity in Turkey, Çakır said that the current capacity of 5.3 million mt will increase to 6.5-7 million mt with new investments, but, as local demand is insufficient, it would be better to divert these capacities to the export markets. On the subject of green transformation, the Borçelik general manager stated that transformation cannot be considered without government support. Saying that Turkey should establish its own emissions trading system, he underlined that tax revenues should be transferred in a transparent manner to transition projects.
Sharing his views on the Turkish pipe market, Vedat Yalçın, chairman of the Turkish Steel Pipe Manufacturers Association (ÇEBID) and executive board member of Noksel Çelik Boru Sanayi, stated that the capacity utilization rates of large diameter pipe producers in Turkey decreased as exports declined after the imposition of Section 232 measures by the US. As regards small diameter pipes, Mr. Yalçın said that the flat steel investments that will come into play when the problem in semi-finished supplies is resolved will make a great contribution to the sector. Stating that the main problems in the market are unpredictable energy prices and exchange rates, Yalçın said that the fact that input costs are in dollars and that sales realizations are in Turkish liras is also a big problem. He added that logistics costs in foreign markets should also be taken into account and that the Turkish steel industry should make investments not only in domestic production, but also for on-site production in other countries, finding ways to open up to new markets.
Ahmet Özkan, vice chairman of Turkey’s Association of Flat Steel Exporters and Manufacturers (YISAD) and chairman of Dempaş Demir, stated that the biggest problems faced by the Turkish steel industry are exchange rates and price fluctuations. Pointing out that Turkish companies have started to withdraw from the market due to the approaching elections, Mr. Özkan stated that business in the domestic market will be active through 2024 with the revival of construction activities in the earthquake-hit zone after the elections. Saying that Turkey’s biggest option in response to the EU’s import quotas is its manufacturing sector, Özkan stated that the domestic manufacturing industry should be developed and that prices should be in line with global prices.
Commenting that the efforts of developed countries to slow down the economy amid the high inflation caused by the war between Russia and Ukraine have begun to be felt, Mehmet Çakmur, deputy chairman of Turkey’s Foreign Steel Trade Association (CDTD) and general manager of M Steel Dış Ticaret, said that market activity and demand have gradually slowed down. Mr. Çakmur said he thinks that the outlooks for the second and third quarters of the year seem to be negative for Turkey’s foreign trade due to the price pressures from aggressive steel offers from Far Eastern countries, which have not been hit so much by the increase in energy costs. He went on to state that the Far Eastern countries should reduce their capacities or stabilize their prices in order for the market to recover. Çakmur said that growth may be seen in Africa on the back of new investments, however, African market cannot absorbe the export volumes shipped to the EU and the US and that competitiveness would be achieved by establishing marketing networks.
Polish rail, road construction impress, EU funds concern
Rail and road construction investment outlays are at record levels in Poland, but there is some concern over receiving EU funding and the longer-term outlook for projects in these sectors. Residential construction has meanwhile slowed notably, but the development of the nascent private rented sector in Poland may support a recovery, panellists said at an industry event on Tuesday.
General Directorate for National Roads and Motorways (GDDKiA) head Tomasz Żuchowski admitted many people think more work could be done on the roads, but Poland is at the limit of its capability with PLN 15 billion ($3.6 billion) of investments each year. This makes it the largest construction site in Europe.
Polish rail operator PKP has meanwhile issued a host of tenders but cannot complete many projects as it does not yet have the certainty of receiving funds in the next EU funding round, its investment director Arnold Brensch said at the European Economic Congress in Katowice attended by Kallanish. The firm has PLN 40 billion of active orders in hand, the “apogee of the largest Polish rail investment period in history”, he added.
Residential construction is meanwhile dragging. The market has seen multiple Black Swan events in the last three years that have hampered activity, observed Wojciech Caruk, chief executive of PFR Nieruchomości, the housing development arm of the state-owned Polish Development Fund (PFR). Building permit issuance is falling, while existing projects are being completed. Financing is meanwhile an issue, with residential mortgages becoming significantly more costly.
Cezary Łysenko, board member at construction contractor Budimex, added that firms are looking at opportunities in the energy infrastructure sector, with economies undergoing the energy transition. However, he added that while the rail project portfolio looks good today, they need the certainty of having projects 5-10 years in advance, which is not the case at present.
Anna Glanowska-Szpor of ING Bank Śląski agreed that green energy investments will play a significant role in construction going forward, while the private rented sector could be an antidote for the ailing residential construction sector. Housing ownership for the purpose of renting out is a relatively new concept in Poland.
When pressed on concerns over EU funds, Polish member of parliament Jerzy Polaczek said: “I cannot imagine that these funds will not materialise. There is continuous dialogue between the government and EU Commission.”
Łysenko concluded by pointing out that although construction material prices, including steel, have stabilised after surging last year, that does not mean they are favourable for contractors. They are 3-4 times higher than they were when construction project contracts were signed 2-3 years ago, he observed. Moreover, the construction project approval backlog has grown considerably in the last six months.
Adam Smith, Poland

Dillinger banks on future in wind parks
German plate maker Dillinger Hütte has reported record figures for the 2022 financial year, which it will use as a foundation for the alignment of the company’s future product portfolio.
While automotive, machinery and steel construction are in a downturn, the wind sector is experiencing a massive boom, Dillinger observes in its annual report. The company announces a clear strategy for profiting from expansion of wind energy with thick plate for construction of offshore wind farms.
Of the company’s total plate production of 1.84 million tonnes in 2022, more than 1mt were thick plate. This is the first time 1m t/year was surpassed in this segment, which the company defines with a thickness starting at 45mm, meaning too thick to be cut with shears. Offshore wind towers require thick plate in principle, and it is also widely used in boilers and mechanical engineering, chief executive Karl-Ulrich Köhler explained at the press conference of parent Stahl-Holding Saar (SHS) monitored by Kallanish.
Dillinger last year in fact lifted its output, from 1.78mt in 2021. High price levels helped the company boost revenue to €3.39 billion ($3.71 billion), up from €2.28 billion in 2021. Operating profit (Ebitda) rose from €201 million to €513m.
Commenting on the larger plate market, Köhler observed weaknesses in the segment of commodities and flame-cutting, “which on the whole does not affect us, as we are expanding in the higher-grade segment”.
He noted that last year’s intensifying Ukraine war also gave rise to demand for vehicle plating, for which Dillinger produces particularly thin but hard grades. “Compared with our overall output, the tonnages are very minor in that segment, though,” the ceo concluded.
Christian Koehl, Germany

Polish steel rebar prices dip, some mills halt operations on low demand
Steel rebar prices in Poland have gone down again on weak demand, with some mills stopping production, sources told Fastmarkets on Friday April 21.
Rebar offers from mills in Poland were reported this week around 3,300 zloty ($785) per tonne CPT (equivalent to about 3,270-3,280 zloty per tonne ex-works) for 12mm rebar, compared with 3,350 zloty per tonne CPT last week.
For tonnages of 1,000 tonnes or more, however, producers were ready to accept lower prices – around 3,200 zloty per tonne ex-works, sources said.
Transactions were reported during the week around 3,200-3,250 per tonne ex-works, sources said. But, in general, trading activity remained poor, and buyers expected prices to go lower in May.
During the assessment week, one rebar producer in southeastern Poland stopped production, citing weak demand.
“On April 18, [the rebar producer] said that it was stopping production because of a lack of demand [and] good stocks [of rebar],” a trading source said.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, exw Poland, fell to 3,200-3,250 zloty per tonne on April 21, down by 50 zloty per tonne from 3,250-3,300 zloty per tonne on April 14.
In the secondary market, rebar was on offer and was traded around 3,320-3,350 zloty per tonne CPT, slightly down week-on-week.
Imports were largely absent from the market during the assessment week. The only offer heard was for rebar in coils at €715 ($784) per tonne from Italy in the first half of the week.
Published by: Julia Bolotova


EUROMETAL at Siderúrgica Balboa and Galvacolor Jerez
The President of EUROMETAL, Fernando Espada, visited this week Siderúrgica Balboa and Galvacolor Jerez, companies of the steel division of CL Grupo Industrial in Jerez de los Caballeros, Badajoz.
Fernando Espada was received by new CEO, Miguel Ángel Leal, Carlos Hernandez and team, well known attendants of UAHE & EUROMETAL events.
Siderúrgica Balboa began its journey in 2008 with a production capacity of 1.2 Mt of steel per year, diversified in structural profile, angles, flat bars, wire rod, corrugated bar and spooler.
Highlighting its commitment to the environment and the principles of the circular economy, Siderúrgica Balboa annually recycles 1 million tons of iron scrap.
Galvacolor manufactures 3 types of flat products: pickled and oiled; cold rolled and galvanized. Currently, it is one of the most modern plants in Europe and has the most advanced systems ensuring production of the highest quality.


EUROMETAL at the Green Steel Expo in Essen
 EUROMETAL was present at the Green Steel World Expo & Conference which took place in Essen on the 4th and 5th of April 2023.
With the objective of bringing together green steel experts from the global market place in one place at one time, this event by KCI Media Group provided an opportunity to meet with both manufacturers and users involved in the decarbonization journey for the steel industry.
EUROMETAL’s participation in this event allowed, in addition to meeting our members, to connect with the important decision makers of the steel industry at the heart of the German Ruhr industrial area.

ArcelorMittal confirms delays to European flats deliveries
ArcelorMittal is communicating to customers this week that delays are expected to deliveries across Europe due to the fires that impacted one blast furnace in northern Spain and another in northern France during the last two weeks.
In a letter to customers, the company says: “We must acknowledge that delays in execution of the existing orderbook are likely to be unavoidable and that allocations for fresh orderbook may also be reduced.”
Currently, blast furnace A at Gijon as well as the main blast furnace at Dunkirk are idled following the accidents on 22 March and 30 March respectively. “We are assessing the damages and the time needed to make the necessary repairs as well as the impact on our production plans. At this stage, given the severity of the incidents, it appears that several weeks will be needed to get back to standard production levels,” the company says in the letter seen by Kallanish.
The letter was sent by the Flat Carbon Europe unit of ArcelorMittal, as the accidents have impacted furnaces mainly producing pig iron for slab and flat steel production.
Emanuele Norsa, Italy