


French stainless scrap prices increase
Stainless steel scrap prices in France are increasing by some €50/tonne ($53) month-on-month, less than initially expected. The hike is due to low material availability but also skyrocketing prices of molybdenum and volatile nickel values, market participants tell Kallanish.
Activity in France will be at normal levels in January. Mills are paying for grade 304 at €1,480-1,580/t delivered this month. The wide range is due to some producers’ refusal to pay the significant increases expected in other European markets amid the high energy and production costs French steelmakers are facing this month. Some are resorting to producing only at night when energy is less expensive.
Grade 316 remains more expensive due to shortages and high molybdenum values. This grade currently fetches around €2,780-2,800/t delivered on average.
While molybdenum prices keep rising due to global production cuts, nickel prices for cash buyers were extremely volatile in December. They reached over $30,000/t last month and fell to $29,750/t on 4 January.
Natalia Capra France


Coil buyers deal easier with SSCs than imports
Northwestern European coil buyers anticipate an interruption in import offers, while some tell of favourable offers to be had from local steel service centres.
Observers tell Kallanish the big foreign suppliers into Europe have seemingly left the market, and “returned” recently-placed orders. “From what I heard, they stopped issuing offers simultaneously just before Christmas, to come back in January, to ask for a three-figure increase,” one source says. This applies to the large Korean, Japanese, Benelux, and other international players. “I heard their customers anticipate €100/tonne ($106) on top, which could mean €750/tonne for hot rolled coil,” he adds.
A manager at a trading company does not necessarily see a sudden leap, but confirms that prices rose prior to year-end, and keep on rising. Whether fast or slowly, any increase in import prices could be a push factor for domestic European prices. In the weeks towards the end of 2022, many import offers had already surpassed €600/t and encouraged EU mills to lift their offers towards €700/t.
Currently, annual contracts with mills have either been signed or are still under negotiation. According to the buyer of a big automotive supplier, some such contracts have worked out better with service centres than with mills. “They have secured spot contracts with the mills into the second quarter at the previously low prices, and are more flexible,” he says. While annual contracts with mills were €200 under last year’s, those with the service centres were €240 lower.
Going into January, deals are expected to work more in favour of sellers, with a year-on-year difference now of probably €150/t.
Christian Koehl Germany

European scrap prices to increase
The trend in January for European scrap prices is for “strong increases”, sources in southern, northern and Eastern Europe tell Kallanish.
Due to short supply of the most demanded grades, such as shredded E40 and E1, and increasing Turkish values, German and Austrian sellers believe values may increase by €30-40/tonne ($31-42). This will include freight rate hikes by German and Austrian rail operators, which should be in the range of €10-15/t versus 2022.
Eastern European sellers are convinced prices will increase €30-50/t. Last month, they went to the extent of retaining material to sell at a higher price in January. One source in Poland says the market is under extreme pressure, similar to that seen in January and February last year.
Exporters from Poland, Czech Republic, Slovenia and Slovakia see prices continuing to increase in Asia and Turkey, caused by shortages and improved demand for rebar.
French sellers also believe this month’s values will go up. However, negotiations have yet to start and French mills are not willing to pay €30-40/t increases considering the high costs of energy and lower demand for finished product.
Italian mills are aware of the international uptrend but they are still shut for the holiday and will resume producing on 9 January. Their intention is to grant some moderate price increases but they are looking to buy large tonnages of imported material from Germany, France and Eastern Europe, while also enquiring about domestic scrap availability and prices.
Despite sellers’ and buyers’ many calls and enquiries, this week remains quiet in most European countries due to the end of the holiday season.
Meanwhile, most Turkish mills have increased their domestic scrap buying prices since last week amid firm imported scrap values and strong domestic rebar demand. Two EU-origin deals have been heard this week (see Kallanish 5 January newsletter).
Natalia Capra France

Volvo EV sales rise more than twofold in Dec as supply chain issues ease
Volvo Cars reported a 205.9% year-on-year increase in electric vehicle sales in December to 14,588 units, while full-year sales rose 159.5% to 66,749 units, it said in a statement Jan. 5.
Volvo’s total rechargeable vehicle sales for December totaled 31,826 units, up 33.5% year on year, with full-year 2022 electric vehicle sales or EVs sales rising and plug-in hybrid sales down 9.6% at 17,238 units.
Monthly rechargeable vehicle sales rose 37.2% year on year to 22,661 units, 7.6% to 3,202 units and 15.8% to 1,933 units in Europe, the US and China, respectively.
Meanwhile, Volvo’s total vehicle sales for December reached 72,633 units, up 12.8% year on year.
The latest monthly sales data from Volvo indicates that the supply chain issues that have hindered global car production through 2022 are continuing to improve despite high inflation and a dull economic outlook weighing on sales expectations.
Total vehicle shipments fall 12% in 2022 despite surge in EV sales
Sales growth across the rechargeable vehicle segment was outweighed by weaker sales of internal combustion vehicle, resulting in full-year 2022 total vehicle sales falling 12% year on year to 615,121 units.
Total vehicle sales for full-year 2022 fell 15.7% to 247,413 units, 5.4% to 162,322 units and 16.5% to 102,038 units in Europe, China and the US, respectively.
“Volvo Cars’ full year sales performance was affected by challenges across the supply chain, as well as production restraints caused by component shortages and covid-related lockdowns in China,” Volvo said. “Despite this, demand for Volvo Cars remained robust,” it added.
The latest monthly figures suggested that the company’s full-year 2022 rechargeable vehicle sales were up 8.5% year on year to 205,302 units, of which EVs increased 159.5% to 66,749 units but plug-in hybrid declined 15.2% to 138,603 units.
In Europe — Volvo’s largest market — 135,714 rechargeable vehicles were sold over the 12-month period, up 3.9% year on year. This included 45,690 EVs, up 175.7% year on year, and 90,024 plug-in hybrid vehicles, down 21% over the same period.
In China, rechargeable vehicles sales for the period rose 4.4% year on year to 12,215 units, of which EV sales were up 231.4% to 2,999 units and hybrids were down 14.6% to 9,216 units.
Volvo’s rechargeable vehicle sales in the US also climbed 22.3% year on year to 27,909 units, including 7,308 EVs, down 14.3%, and 20,061 hybrids, up 25.4%.
Rising demand for EVs has supported higher battery metal prices, with Platts seaborne lithium carbonate and lithium hydroxide assessments up 121% and 156.2%, respectively, since the start of 2022 at $74,700/mt CIF North Asia and $81,200/mt CIF North Asia as of Jan. 5, S&P Global Commodity Insights data showed.
— Euan Sadden


UK DATA: car sales fall 2% in 2022;EVs up 40.1% to record high: SMMT
New car registrations in the UK were up 18.3% year on year to 128,462 units in December, bringing the full-year 2022 total to 1.614 million units, 2% lower than 2021’s total, according to data released Jan. 5 by the Society of Motor Manufacturers and Traders.
The December total was the fifth year-on-year increase since February, according to the data, although the volume was 10.1% lower than November.
While the second half of the year saw improved performance, this was not enough to offset the declines seen in the first half of 2022, with full-year sales around 700,000 units below pre-COVID levels, the SMMT said
“The automotive market remains adrift of its pre-pandemic performance but could well buck wider economic trends by delivering significant growth in 2023,” SMMT CEO Mike Hawes said.
To secure car sales growth, which is increasingly zero-emission growth, Hawes called on the government to help all drivers go electric and to back more rapid investment in nationwide charging infrastructure.
“Manufacturers’ innovation and commitment have helped EVs become the second most popular car type. However, for a nation aiming for electric mobility leadership, that must be matched with policies and investment that remove consumer uncertainty over switching, not least over where drivers can charge their vehicles,” he said.
The SMMT said that ensuring all drivers could buy zero emission-capable vehicles during 2023 depended on broader policies to encourage uptake.
Charge point provision also remained a barrier to EV uptake, with the SMMT noting that meeting the UK government’s EV Infrastructure Strategy goal of 300,000-720,000 charge points by 2030 would require more than 100 new chargers to be installed every day, with the current rate only around 23 a day.
2022 BEV sales up 40.1% on year
Battery electric vehicles sales rose 52.6% year on year in December to 42,284 units, which was also up 44.0% from November and at a record high, the data showed.
This brought full-year BEV sales to a record 267,203 units, up 40.1% year on year and at a 16.6% share of total car sales, up from an 11.6% share in 2021.
Higher EV demand has been one factor boosting battery raw material prices. Platts, part of S&P Global Commodity Insights, assessed seaborne lithium carbonate and lithium hydroxide at $74,700/mt CIF North Asia and $81,200/mt CIF North Asia Jan. 5, up 121% and 156.2%, respectively, since the start of 2022.
The volume of hybrid EVs sold in December climbed 58.1% year on year, but fell 14.5% on the month to 13,743 units, bringing the full-year total to 187,948 units, rising 27.6% year on year and increasing the share of total sales to 11.6%, up from 8.9% in 2021.
December sales of plug-in hybrid EVs edged up 0.4% on the year but fell 17.9% on the month to 8,367 units. However, the full-year 2022 total slipped 11.5% to 101,414 units, taking a 6.3% share, down from a 7.0% share in 2021.
ICE vehicles at 47.4% share in 2022
The combined market share of petrol and diesel internal combustion engine vehicles fell to 47.4% in 2022, down from a 58.2% share in 2021.
In December alone, the combined share was 35.9%, the lowest monthly share since January 2021.
Petrol car sales for the year dropped 10.4% year on year to 682,473 units, continuing to hold the largest market share in 2022 at 42.3%, which was down from a 46.3% share in 2021.
At 82,981 units, diesel vehicles’ market share for the year was 5.1%, down from 8.2% a year ago.
The diesel volume was also down 38.9% year on year, the data showed.
— Jacqueline Holman

GERMAN DATA: EV sales rise 22% in 2022: VDA
Sales of passenger electric vehicles in Germany more than doubled on the year in December, bringing the full-year 2022 total to 833,500 units, up 22% from 2021, according to the latest data from auto industry association VDA released Jan. 5.
December EV sales were also up 70% from November and at a 55.4% market share, up from 35.6% a year ago and the highest monthly share on record.
The VDA said the record high suggested that purchases were being brought forward, as state subsidies for plug-in hybrids, or PHEVs, expired at the end of 2022, and those for purely battery-electric vehicles, or BEV, were reduced.
Of the December volume, 104,330 units were battery EVs, up 115% on the year, while 69,800 were plug-in hybrid EVs, up 113%, the data showed.
The full-year 2022 market share for EVs was 31.4%, up from 26.1% in 2021.
Of the 2022 total, BEVS were 470,600 units, up 32% on the year, while PHEV sales climbed 11% to 362,100 units, according to the VDA.
With demand for EVs generally moving higher, battery raw material prices have been strong. Platts, part of S&P Global Commodity Insights, assessed seaborne lithium carbonate and lithium hydroxide at $74,700/mt CIF North Asia and $81,200/mt CIF North Asia Jan. 5, up 121% and 156.2%, respectively, since the start of 2022.
Meanwhile, overall new vehicle registrations climbed 38% on the year in December to 314,300 units, which was up 21% from the previous month.
Of the monthly total, 190,100 units, or 60.5%, were German brands and the remaining 124,200 were foreign brands.
Full-year sales totaled 2.65 million units, up 1% on the year, with German brands making up 1.8 million units, steady year on year, and foreign brands rising 3% from 2021 to 874,100 units.
“The lack of primary and intermediate products, the high energy and raw material prices and the general uncertainty due to the war in Ukraine had dampened the market and production considerably throughout the year – but especially in the first half of the year – so that especially in spring and significant declines were recorded in the summer of 2022,” the VDA said.
It noted that, compared to 2019, sales were down 26% in 2022.
The data showed that 202,500 vehicles were exported from Germany during December, up 1% from a year ago, but falling 28% from November.
Total exports for 2022 jumped 10% year on year to 2.6 million units.
According to the VDA, 253,700 passenger cars were produced in December, up 2% on the year and the eighth consecutive months of year-on-year gains, although this was 34% lower than the previous month.
In the whole of 2022, 3.4 million passenger vehicles were produced in Germany, up 11% on the year, the VDA said, although it added that the production volume was still at a comparatively low level and was around 26% lower than pre-pandemic levels.
According to S&P Global, plug-in light duty EV sales in Germany are expected to be 771,990 units in 2022 then reach 1.1 million units in 2025 and 1.9 million units in 2030.
— Jacqueline Holman
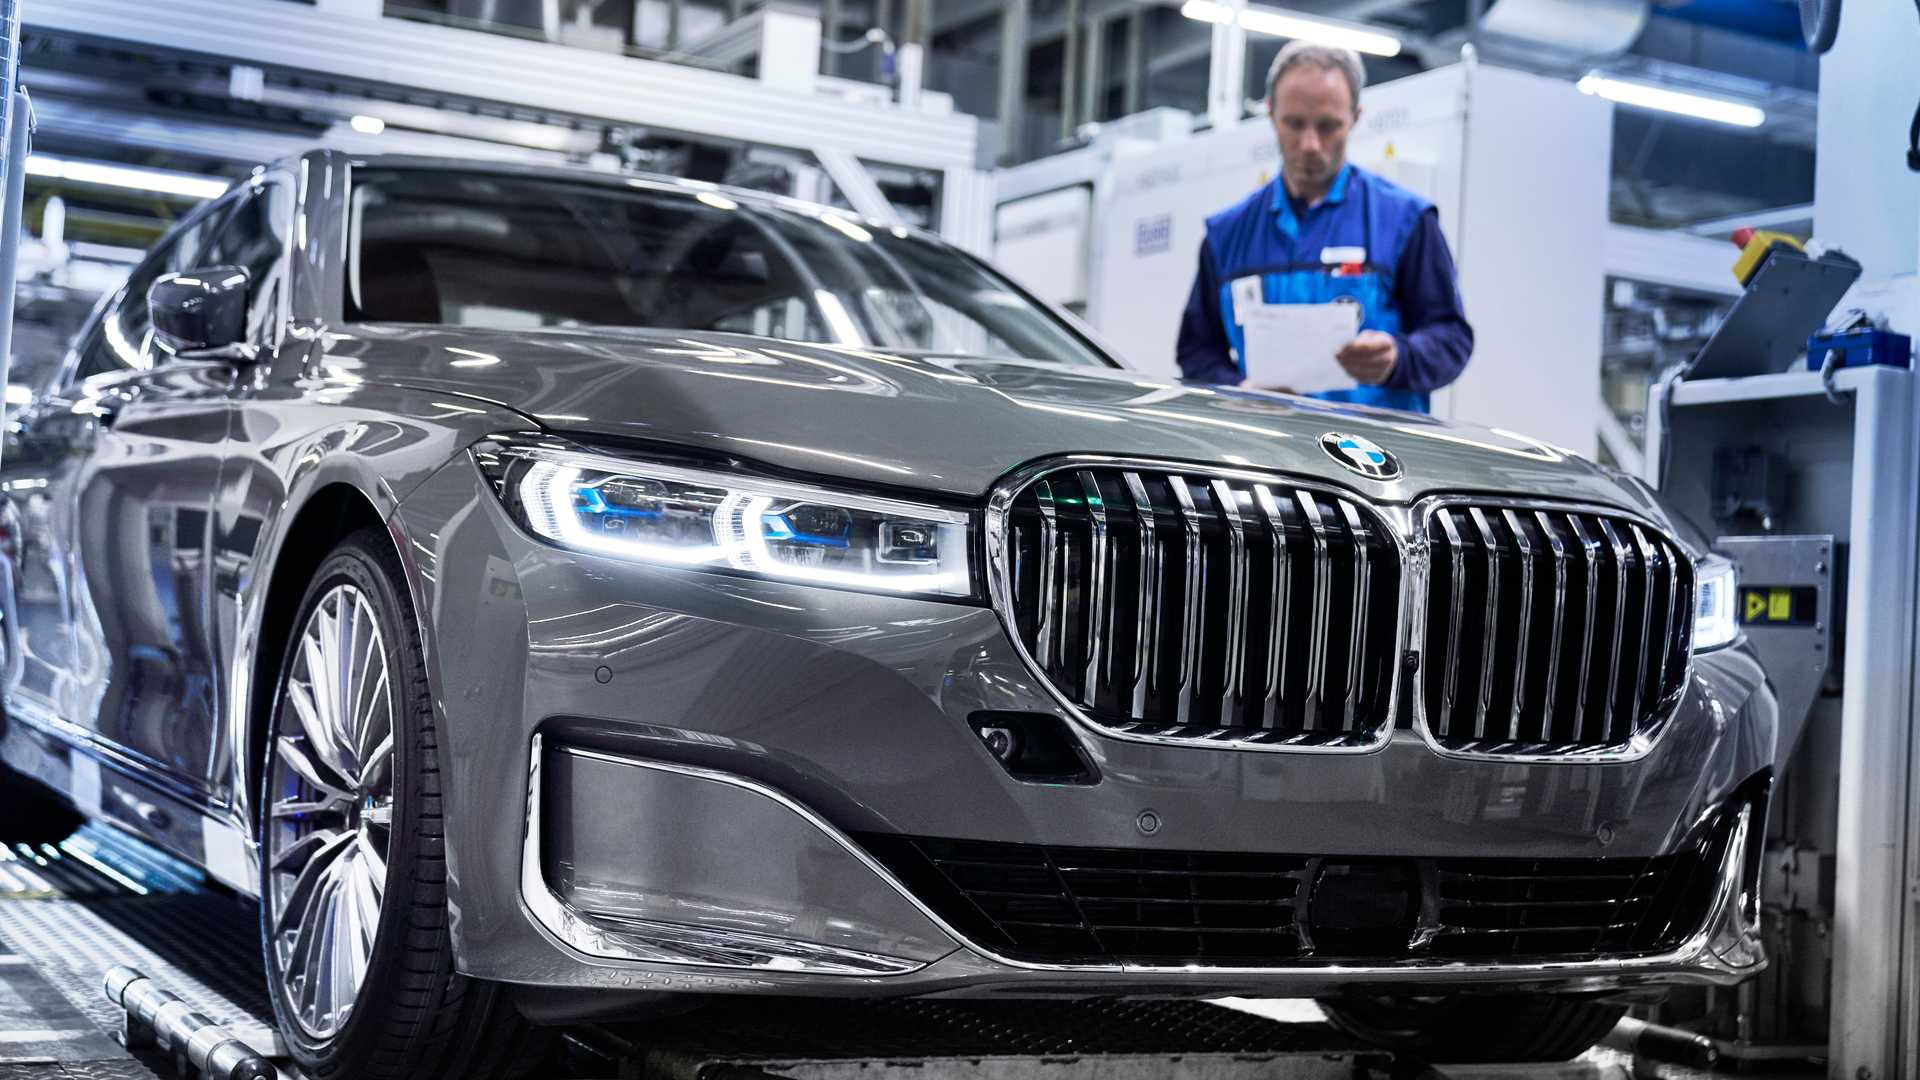
Turkey’s Kardemir to undertake steel manufacturing, installation of BMW’s Hungary factory
Turkish steelmaker Kardemir said Jan. 5 its subsidiary Karcel will carry out steel manufacturing and installation works for German automaker BMW’s new Debrecen plant in Hungary which will use 10,000 mt of structural steel.
BMW’s new plant will have a capacity of 150,000 vehicles/year, according to reports.
Karcel will also continue to focus on new projects in the Balkans and the European region, which will increase Kardemir’s steel export volumes, Kardemir said.
Kardemir, which has 3.5 million mt/year liquid steel capacity, has expanded its product range to include rails, railway wheels, thick wire rods and heavy sections.
Platts, part of S&P Global Commodity Insights, assessed Turkish exported rebar at $682.50/mt FOB on Jan. 4.
— Cenk Can

European HRC traders watch for emergence of new import offers as domestic lead times extend
Prices were stable for European hot-rolled coil Jan. 5, with market participants continuing to wait and see amid a scarcity of domestic or import offers.
Platts assessed North European HRC stable on the day, at Eur700/mt ex-works Ruhr.
Distribution sources generally had Eur700/mt ex-works in mind as a minimum price level for January trading, though mills are reportedly considering higher prices given strong restocking activity in December. However, concerns remain on buy-side that increases are not fundamentally supported.
“It’s fine to be bullish but the one thing I would say is that this price increase was stimulated by restocking unrelated to end-user demand,” said a distributor. “That said, with lead times extending, people will need to buy soon for April, so it’s probable the increase will last the month at least.”
Trader sources were awaiting new import offers, with only a few foreign mills advertising material.
“A lot of mills aren’t offering yet,” said one Northern trader. “Most are waiting to see who moves first in the market and where prices will land – we’ve received a few offers from India but are still awaiting prices from the far-east on hot-rolled.”
While offers are indeed sparse, indications were received for import material at $670/mt CIF Spain ex-India, and at $660-$670/mt CIF Italy ex-Egypt.
Prices were anticipated to increase to Eur700/mt CIF in the Italian market, as reported by a mill source, with traders somewhat positive on near-term activity given longer European mill lead-times as compared to the second half of last year.
Import offers have been heard for as late as June delivery, with aforementioned European mill lead times extending into March.
Platts is part of S&P Global Commodity Insights.
— Benjamin Steven

UK HRC stockholders see strong activity at start of year, expect price increases
Stockholders in the UK hot-rolled coil market reported strong activity to start the year Jan. 5, though uncertainties remain as to the longevity of expected increases.
“So far we’ve been very busy, but it’s only the first couple of days,” said one stockholder. “Distributors restocked which is adding fire to bullish sentiments, but that had little to do with end-user demand.”
Another stockholder clarified further, pinning much of the drive in end-user activity on logistical factors rather than real demand.
“We have been busy this week but that was always going to happen with the traditional restocking process,” said the source. “People don’t want material in December when books are closing on credit and storage factors. There’s no real surprise in the increased activity – it’s still too early to celebrate.”
That said, sources expected prices to be supported in January due to longer mill lead times both domestically and in Europe, with material heard booked on the day for March delivery.
Deals were heard for larger, more representative tonnages at GBP610-615/mt DDP West Midlands, with minimal volumes traded higher in the mid-GBP600s.
How long the circa GBP610/mt DDP price level will be sustained is doubted however, with price increases expected for week beginning January 9.
Sources anticipate the tradable level to advance to the mid-to-late GBP600s from domestic and European mills, reinforced by tighter supply post-production cuts last year.
“When it comes time to buy, production cuts do bite,” said a stockholder. “Lead times are a lot longer than they were in October, higher prices will theoretically have more support.”
Platts is part of S&P Global Commodity Insights.
— Benjamin Steven

European metal consumers switch to short-term buying due to uncertainty: 2023 preview
Growing uncertainty about end-user demand and input costs through 2022 has driven a change in consumer habits in Europe’s aluminium and steel markets, with traders foreseeing a continuation of hand-to-mouth buying going into 2023.
Changing consumer habits
The energy crisis in Europe – exacerbated by Russia’s invasion of Ukraine – as well as rising interest rates, material shortages and a negative economic outlook have combined to force production costs higher for all metals producers in the region. These same factors have also put a strain on the key metal consumer sectors – automotive and construction.
Initial overstocking after the war in Ukraine erupted in February, coupled with shrinking end-user demand, pushed prices down for steel and aluminium products in the ensuing months. European mills then had to significantly cut production to balance supply and demand.
The uncertainty over future consumption has made longer term forecasting difficult, traders have said, and this has led to limited, short-term buying.
“Everyone is [trading] on a weekly basis, mostly because things are very unsure,” a steel-beam producer source in Southern Europe told Fastmarkets.
Growth in the construction sector is predicted to drop to 0.2% in 2023 from 3% in 2022. It is expected to flatten later, to 0% in 2024, with no recovery anticipated until 2025, according to construction market forecasting network Euroconstruct.
Independent global economic forecaster Oxford Economics forecasts a 0.3% quarterly drop in eurozone construction output in the first quarter of next year.
And automotive output is expected to have dropped by 1.7% overall in 2022 due to the “severe repercussions of ongoing supply-chain disruptions and the war in Ukraine,” Eurofer said in its 2022-2023 fourth quarter economic report, in which it also said that these downside factors are expected to persist “at least until the second quarter of 2023.”
In the first nine months of 2022, car registrations in the European Union fell by 9.9% to 6.8 million units, according to the European Automobile Manufacturers’ Association (ACEA).
“The last [several] years have been marked by major events like Brexit, the coronavirus pandemic, semiconductor supply bottlenecks, and the war in Ukraine with its impact on prices and availability of energy,” ACEA president and CEO of BMW Oliver Zipse said in October.
“All of these things underline how quickly, how profoundly, and how unpredictably our world is changing,” Zipse said. “This applies not least in the geopolitical context – where there are direct consequences for our globally interconnected industry and its close-knit value chains.”
The hand-to-mouth purchasing trend will likely carry on into 2023, until rising costs are eased, and end-user demand and confidence are strengthened, trader sources told Fastmarkets.
Several distributors intend to keep their level of stock low in January-February 2023, they said, due to high levels of volatility in the market.
“We currently book only what’s strictly necessary,” a distributor source in Northern Europe said. “There is no clarity on whether the uptrend that has recently begun in the flat-steel markets will actually last in early 2023.”
Higher production costs and sluggish steel demand had also led to several European producers either stopping steelmaking capacities or trimming output to balance supply and demand, during the third and fourth quarter of 2022.
Loss of consumer confidence in construction sector
A gloomy outlook for the construction sector in 2023 has for several months put downward pressure on long-steel product markets including rebar, wire rod, beams and hollow sections.
“As long as the energy cost problem is not solved, I don’t think a lot of construction companies will make investments for the near future,” a sections trader source in Germany said.
In Italy, the price of electricity rose to above €420 per mwh in the week to December 14, more than four times the average one-month cost in November of €87.84 per mwh, according to Italy’s exchange for electricity and natural gas spot trading, Gestore Mercati Energetici.
In Germany, traders pegged energy costs at around €440 per mwh in the same week.
Long-steel prices have now flattened in major markets in the region, with traders expecting long-steel demand to pick up by early next year due to companies needing to restock.
Mills pushed for higher prices in December, but market participant’s opinions were mixed on whether those higher prices would be tradeable in 2023 given the anticipated weak construction consumption – even if the high price of energy and scrap raw material costs support upward price movements.
“At this moment there are so many concerns about uncertainty in the economy that demand is disappearing, and construction projects are being postponed because nobody knows what is going to happen,” a distributor source in Northern Europe said.
“If Europe finds a solution for the energy issue and energy prices drop to more normal, pre-war levels, then the situation is solved,” the distributor source added. “It can’t happen overnight, but it can happen in a quarter of a year.”
But while uncertainty looms over construction-sector prospects in early 2023, some aluminium market participants were optimistic about activity picking up in spring when the weather is milder and energy costs ease.
“I’m expecting the construction business to get stronger in spring,” an aluminium seller said.” It’s very seasonal work, and while the automotive sector looks fine, you can’t rely on that sector; they are pretty fast at cancelling orders.”
Other factors affecting construction-sector activity include rising construction material prices, a growing scarcity of materials, and a construction-worker shortage, according to the European Steel Association Eurofer.
Automotive industry
A move away from forward-looking trading has also been observed in flat-steel and aluminium products due to uncertainty about future end-user demand in the automotive sector.
Automotive industry buyers, meanwhile, have been reportedly seeking shorter-term contracts – preferring quarterly versus half-year contracts – due to the high degree of volatility in the market, several sources said.
Mill sources, on the other hand, expressed doubts about the effectiveness of such a move.
“It would be difficult to achieve from an administrative point of view: renegotiating prices every three months would be complicated and time-consuming,” one mill source said. “Using floating indices and making [contracts] more instrumental could be a solution.”
Automotive demand is expected to recover in 2023, market participants told Fastmarkets, although it is unlikely to rebound to pre-Covid levels, they said.
After an 18.7% slump in 2020 due to the Covid-19 pandemic, automotive output in 2021 rebounded, but only by 3.3%, Eurofer said in its most recent market outlook on October 26.
Output from the automotive industry was expected to show a 1.7% decline in 2022. This would mean that the automotive industry’s output would remain below pre-pandemic levels.
The association expects output by the automotive sector to rebound by only 1.1% in 2023 – but only if supply-chain issues and global uncertainty ease substantially.
“We should definitely see a better demand scenario for 2023,” one automotive consumer source said, adding that it would “likely not [be] until the end of [the first quarter] and leading into the second half of the year, but it should definitely be better, subject to no further let-downs on the semiconductor side.”
The automotive industry was significantly affected by supply-chain issues over the course of 2022, which caused postponements of material and a significant backlog in orders.
As such, purchasing managers have been more reluctant to conclude long-term deals for large tonnages given the uncertain demand outlook for 2023, market participants said.
“There’s been roughly a 10-11% demand drop from the impact of semiconductor shortages in 2022, but we should see a rebound into next year,” the consumer source said.
Demand in the “recession-proof” aluminium packaging and aerospace sectors has, however, stayed robust.
Impact on prices
Limited hand-to-mouth purchases as a consequence of low consumption could increase price volatility in Europe’s steel and aluminium markets in 2023, with low stocks leaving traders more vulnerable to price swings during periods of tight supply if supply chain logistics issues arise, Fastmarkets understands.
Aluminium premiums have seen extreme volatility over the past twelve months, with many consumers reportedly purchasing additional quantities earlier in the year when premiums were rising to record highs over fears of being able to secure enough supply.
This has since led to high inventories and limited spot demand as Europe continues to face an ongoing energy crisis.
“There’s been a particular interest in destocking and consumers running down expensive inventory rather than entering the spot market,” one European aluminium trader source said.
Fastmarkets assessed the aluminium P1020A premium, in-whs dp Rotterdam at $255-270 per tonne on Tuesday January 3, rising from $250-270 per tonne on December 30, but remaining 57% lower than the record high of $600-630 per tonne in May.
Participants in the aluminium billet industry also said that typical first quarter contract negotiations had been postponed, with some still waiting to conclude and consumers drawing on existing stocks.
Similarly, negotiation periods had been shortened, with consumers unwilling to lock in a fixed premium for extended periods due to ongoing volatility and recent swings in the premium.
Fastmarkets assessed the aluminium 6063 extrusion billet premium, ddp North Europe (Ruhr region) at $650-700 per tonne on December 30, lower than the $650-750 per tonne on December 16 and falling from record highs of $1,500-1,570 per tonne in February.
“[Consumers] are booking the bare minimum of their needs, perhaps just 20-25% of their needs, and then in case demand picks up, they will get back to us with spot tonne requests,” a second aluminium seller said. “Our production volumes for January are down 60%, as we still have quantities that were postponed.”
It was a similar story for steel market participants.
“European buyers learned their lesson – we all remember what happened in spring 2022 onwards, when everyone ended up having massive stocks of overpriced HRC,” a stockholder in Italy said.
The war in Ukraine flustered the European steel market, causing a wave of a panic buying in February and March, with prices for flat and long steel surging dramatically, breaking the records set in summer 2021.
For example, Fastmarkets’ calculation of its daily steel hot-rolled coil index, domestic, exw Northern Europe averaged at €1,278.50 per tonne in March 2022, up by €326.49 per tonne month on month from €952.01 per tonne in February and up by €489.60 per tonne year on year from €788.90 per tonne.
Market sentiment, however, has soured due to slowing automotive demand and competitive import offers.
Since April 2022, poor demand has led to an oversupply of material, especially in the flat-steel market, leading to older stock material undercutting freshly produced products and supporting lower prices, sources said.
European flat-steel prices have tumbled since April. Only in December did European steel producers start to attempt price increases. They did so gradually, in response to a slight improvement in trading, output cuts announced by several steelmakers, and anticipated end-user demand recovery.
And despite mills pushing for higher prices for coil with delivery in February 2023, traders said that anticipated contractions in Europe’s automotive and construction sectors will make achieving the higher prices difficult – even considering increased input costs and production cuts, sources told Fastmarkets.
“For now European mills are firmly offering a minimum €650 per tonne EXW for HRC,” a German trader source said. “We will see if they manage to fill their order books with these prices. When the market restarts after holidays in mid-January 2023, it will be clearer.”
Production cuts will, however, have a visible effect on the steel market in Europe early in 2023, mill sources said, and coil supply might fall short of demand.
“We do expect end-user demand to pick up. When everyone is back for material early next year, we might see a shortage of [HRC], given all the capacities that have been brought down in the fourth quarter 2022,” one mill source said.
Published by: Julia Bolotova, Carrie Bone, Imogen Dudman, Holly Chant
