


Polish rebar market enters quiet period, price rises expected early nex year
Polish rebar market slows for holidays, with price rises likely in January, sources told Fastmarkets on December 23.
Fastmarkets’ price assessment for steel reinforcing bar (rebar), domestic, exw Poland was 3,400-3,450 ($776-787) zloty per tonne on Friday, up by 50 zloty per tonne from 3,350-3,400 zloty per tonne the previous week.
The assessment was based on a few deals, the lower end of offers and buyer estimations of achievable prices.
One producer in Poland was firmly offering rebar at 3,700 zloty per tonne CPT. This equates to about 3,650-3,670 zloty per tonne ex-works. No bookings have been reported at this price level so far.
Another Polish producer was reportedly selling rebar in the local market at 3,400 zloty per tonne CPT (3,350 zloty per tonne EXW).
Buyer indications of achievable prices, meanwhile, were heard at 3,350-3,450 zloty per tonne EXW.
Trading was slow in the nation during the assessment week due to approaching holidays.
Sentiment was cautiously optimistic for January, with higher offers expected to be at least partially accepted in deals due to a moderate pick-up in end-user demand and tighter supplies.
Local electric-arc furnace-based mill, Cognor, has been out of the market since mid-December to modernize its equipment and is only expected to be back in the market with offers early in the second quarter of 2023.
“There has not been much demand [in the week to December 23] but buyers are [beginning to believe] that price increases [for rebar] are inevitable,” the trading source said.
Published by: Julia Bolotova


European HRC prices edge higher, mills eye further increases for 2023
Hot-rolled coil prices edged higher in Northern Europe on increased offers, with mills also expecting to seal deals at higher prices early next year because of short supplies and the potential for a pick-up in demand, sources told Fastmarkets on Friday December 23.
European steel makers have gradually pushed their HRC offer prices for January above €700 per tonne EXW, up from €650-680 per tonne EXW in December several sources added.
One integrated mill in Germany was testing the market with an offer price of €740 per tonne EXW.
And even though the higher levels have not yet been sealed in deals, steel mills said they were optimistic because they have good order books, while production cuts and the potential pick-up in end-user demand were also supportive.
During the third and the fourth quarter of 2022, a number of European producers have either stopped steelmaking or trimmed output to balance supply and demand.
An integrated mill in the Benelux area claimed to be nearly sold out for first quarter 2023 rolling HRC volumes.
Transaction levels and buyer estimates of achievable prices in Northern Europe in the week to December 23 were reported at €650-670 per tonne EXW, with some sources indicating that even €680 per tonne EXW was an achievable level.
As a result, Fastmarkets calculated its daily steel hot-rolled coil index domestic, exw Northern Europe at €668.75 ($709.93) per tonne on Friday, up by €11.50 from €657.25 per tonne on Thursday.
The latest calculation of the index is up by €23.96 per tonne week on week and up by €47.14 per tonne month on month.
Mills and automotive industry end users have been making progress with long-term contract negotiations at higher prices than initially targeted, sources said.
“In early November [long-term contracts] prices were discussed [at around] €700-750 per tonne EXW, now we are talking €800-850 per tonne EXW,” the trading source said.
Fastmarkets’ calculation of its daily steel hot-rolled coil index domestic, exw Italy meanwhile, was €652.50 per tonne on Friday, unchanged from Thursday.
The latest calculation of the Italian index is up by €14.17 per tonne week on week and up by €64.77 per tonne month on month.
Italy’s mills were largely out of the market and are not expected to come back until January 9, but mill indications for the new year were reported at around €670-680 per tonne EXW.
Overseas suppliers were mostly not offering coil to Europe in the pre-holiday lull, but import offers for coil from Southeast Asia were heard at €630-640 per tonne CFR Italy – although, so far, the price has been considered too high by local buyers.
India-origin coil was reportedly offered at €620 per tonne CFR Italy earlier this week.
Sources said that overseas suppliers from Southeast Asia were cautious about the possibility that the EU authorities might start an anti-dumping investigation, particularly into imported HRC and in November and early December they were very aggressive, offering material at €570-600 per tonne CFR.
Published by: Julia Bolotova

TURKEY DATA: Jan-Oct steel CRC exports fall 24% on year on lower southern EU demand
Turkey’s cold-rolled coil exports in the first 10 months of 2022 fell 24% year on year to 416,800 mt, hit by lower demand from its traditionally main export market of Southern Europe, the latest data from the Turkish Statistical Institute showed.
Italy remained the top buyer despite a 38% year-on-year decline to 102,500 mt, while shipments to Spain slumped 58% to 29,500 mt.
Exports to the US, however, rose 17% to 48,000 mt, while shipments to Belgium dropped 20% to 41,200 mt.
Turkey’s other CRC export markets in the 10-month period were Bulgaria (34,200 mt), Egypt (22,600 mt), Romania (20,200 mt), Greece (18,800 mt) and Canada (14,000 mt).
The revenue generated from overall CRC exports in the period declined 20% year on year to $439 million, TUIK data showed.
Turkish CRC prices exceeded $1,400/mt in mid-March although they have declined since. Platts, part of S&P Global Commodity Insights, last assessed Turkish CRC at $760/mt ex-works Dec. 16.
— Cenk Can


EU HRC prices flat ahead of Christmas; outlook bullish
Domestic prices for hot-rolled coil were unchanged in Europe on Dec. 23 due to market slowdown ahead of Christmas holidays.
The outlook has been largely bullish due to anticipated demand recovery in January, reduced availability from the domestic mills due to production cuts and rise of import offers.
“Market is very quiet now,” a trader said. “But I think that both domestic and impot prices will rise in January.”
A German mill has already tested the market with higher offers this week, asking Eur740/mt ex-works Ruhr.
While tradable values have been reported at Eur650-700/mt ex-works Ruhr.
Platts assessed North European hot-rolled coil unchanged on the day at Eur680/mt ex-works Ruhr on Dec. 23.
The assessment for domestic HRC in south of Europe has also been stable day on day at Eur670/mt ex-works Italy.
Market participants reported tradable value at Eur650-670/mt ex-works Italy.
Platts is part of S&P Global Commodity Insights.
— Maria Tanatar

EU plate producers aim for higher prices on demand recovery
European steelmakers have been targeting higher prices for heavy plate in the week to Dec. 23 citing anticipated demand recovery and higher costs.
A German steelmaker has been offering plate at minimum Eur900/mt ex-works Ruhr. Market sources estimated tradable values at the same level.
Another mill from Germany, traditionally less involved in the spot market activity, has been offering the material at prices above Eur1,000/mt ex-works Ruhr.
A Northern European mill has been trading plate at Eur900/mt ex-works.
Platts assessed heavy plate in Northern Europe up Eur50/mt week on week at Eur900/mt ex-works Ruhr on Dec. 23.
Situation has been similar in Italy, where the re-rollers are more exposed to rising slab and high energy costs.
“If you want to get slab from Asia now, you can get prices of about $640-$650/mt CIF Italy,” an Italian re-roller said. “With such slab prices, you cannot sell plate below Eur800/mt ex-works, it would simply be below the production costs.”
Platts assessed import slab prices in Italy at $640/mt CIF Italy Dec. 23, up $65/mt week on week.
Offers of heavy plate from Italian mills have been heard at Eur800-850/mt ex-works Italy. Tradable values have been reported at Eur790-800/mt ex-works Italy, but the mills are expected to insist on achieving prices of Eur850/mt ex-works Italy in the start of January.
Platts assessed Italian heavy plate up Eur50/mt week on week at Eur800/mt ex-works Italy on Dec. 23.
Platts is part of S&P Global Commodity Insights.
— Maria Tanatar, Benjamin Steven

Klöckner & Co bolsters North American footprint via $340mln purchase of Mexico steel distributor
German steel group Klöckner & Co is increasing its presence in North America via the acquisition of Mexican steel distributor and service center National Material of Mexico (NMM), it said.
This is the latest example of steelmakers in North America restoring supply chains to their country of origin – a trend particularly apparent in the automotive sector – to counter disruptions caused by the Covid-19 pandemic and to take advantage of government policies to stimulate domestic production.
The acquisition – costing $340 million – is a part of Klöckner & Co’s strategy to expand its product and service portfolio out to 2025, it said late on Monday December 19.
The additions to its portfolio resulting from this transaction will allow the company to supply carbon and electrical steel, aluminium and stainless steel directly in Mexico, it also said.
Subsidiary Klöckner Metals has been investing in Mexico to supply the country’s automotive industry. Last year, it started construction of its second steel processing facility in the country.
NMM is a leading steel service center in Mexico, headquartered in northeastern Monterrey city and with 10 operations in the country. It supplies automotive, home appliances, motor and transformer manufacturers. The company offers processing capabilities that include slitting, cut-to-length, leveling, multi-blanking, configured blanking and core processing.
After the acquisition is completed – the company expects to do so by summer next year, pending approval from antitrust authorities – NMM will come under the Klöckner Metals brand, it said.
The combined company will have presence in the United States and Mexico with 55 sites and around 2,600 employees. NMM, which employs around 500 people, generated sales of $610 million in fiscal 2021.
Steel prices in North America have been recovering in recent weeks, led by price increases and higher demand in the US.
Fastmarkets’ daily steel hot-rolled coil index, fob mill US was calculated at $35.92 per cwt ($718.40 per ton) on Monday December 19, up by 0.64% from $35.69 per cwt on Friday December 16 and up by 4.88% from $34.25 per cwt a week earlier.
Published by: Felipe Peroni

Acciaierie d’Italia to receive EU funds to decarbonise
Italy will receive €1 billion ($1.06 billion) from the European Commission (EC) within the framework of the Just Transition Fund (JTF) scheme that supports the energy transition of contaminated and degraded areas caused by industrial exploitation. Part of the funds will go to the decarbonisation of the troubled steelmaker Acciaierie d’Italia’s main facility in Taranto, the largest and most obsolete steel plant in Europe and one of the most polluting, Kallanish learns from the EC.
The funds will support economic diversification, accelerate renewable energy and green hydrogen investment, and retrain employees in Taranto to convert the steelmaking process to green production. Some 4,300 workers will be retrained to develop new skills in green steelmaking. JTF will finance new wind farm projects in the area, green hydrogen production plants and geothermal ventures for both the Taranto facility and residential buildings. Local SMEs will be able to access part of the grant to boost economic diversification, develop skills related to the energy transition and accelerate the development of technology for decarbonisation, the EC explains in a note and adds that a green area of parks and reforestation around Taranto is also planned to restore degraded land.
A chunk of the €1 billion funds will also support the green conversion of the coal mine of Sulcis Iglesiente, in Sardinia and boost the area’s economic diversification, agriculture and tourism including retraining 2,250 workers in the energy transition, Kallanish notes.
The Just Transition Mechanism invests in areas degraded by carbon emissions. Funds are dedicated to workers’ reskilling, research and development, SME’s clean energy projects and the conversion of carbon-intensive plants.
Acciaierie d’Italia, the joint venture formerly known as Ilva between ArcelorMittal and state financial body Invitalia, is going through “strong financial trouble and a serious production situation,” Made in Italy minister Adolfo Urso said earlier last week during a Q&A session at the Senate in Rome. The company has piled up several million in debt to some of its main suppliers, including large Italian energy companies Snam and Eni. The steelmakers’ output has collapsed from 10 million tonnes in 2005 to approximately 3mt this year, when the target of the industrial plan was to reach 6mt, Urso said. He pointed to the lack of a clear industrial plan to stop the company’s decline.
The Italian government may inject between €500 million and €1 billion into the troubled steelmaker. The funds however have not yet been released, which is causing unrest, strikes and fear of bankruptcy (see Kallanish passim).
Natalia Capra France

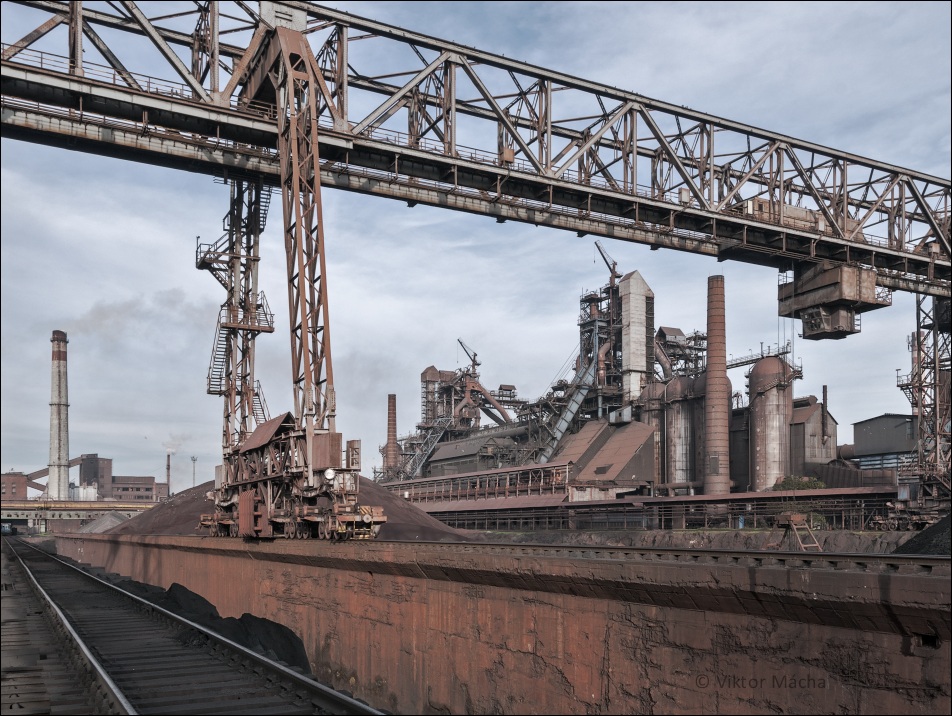
Hungarian flat steel producer Dunaferr has gone into administration: mayor’s office
Hungarian integrated flat steel producer Dunaferr has gone into administration, with the mayor of Dunaujvaros, the industrial town where the mill is located, appealing to the national government to take it over, with the emergence of a private investor, he said, remaining “very uncertain.”
The court ordered the liquidation of Dunaferr and appointed a temporary administrator. The moves follow the announcement published this week on the Dunaujvaros municipal website.
Plant management did not respond to the request from S&P Global Commodity Insights for comment, but the information was confirmed by a source there.
The mill is under administration, faces a court ordered liquidation, several top managers were fired, an ex-Dunaferr employee also told S&P Global, adding that Dunaferr’s electricity supply has been shut off because of prior arrears.
“For many years we listened to the state saying that it would buy the steelworks, but the owner was not willing to sell it,” Mayor Tamas Pinter said in a statement. The steelworks should now be taken over by the state, he added.
“In 2020, the [Hungary’s] bankruptcy law was amended so that in case of strategically important companies, the state has the right of preemption, even then we thought and trusted that this amendment was made because of Dunaferr,” Pinter said.
According to the mayor, the intervention by private investors was unlikely, as in the last two-three years there have been several parties interested in Dunaferr, but without any resulting deal.
The local government has put forward two principles it wants the plant’s future owner to guarantee.
“There are two important things, one is that the plant continues to operate in such a way that the entire production spectrum remains,” Pinter said. “The so-called liquid [steelmaking] phase has been around for a long time. I do believe that it is needed and should not be abandoned during the liquidation.”
Another important thing is that all workers continue to receive their full wages, the mayor requested.
If a private investor is not found and the state does not nationalize the plant either, the outcome would be a tragedy for Dunaujvaros and the whole of Hungary, according to Pinter.
Dunaferr has been idled since the third quarter: the mill suspended its two blast furnaces, with combined capacity of 1.2 million mt/year, in August and September due to disruptions to its coke supplies.
Dunaferr still legally belongs to Russian bank Mezhekonombank, which holds 51%, with the remaining 49% shared between two Ukrainian businessmen.
“The owners, the Russian bank and the Ukrainian investors, did not want to invest or even manage the asset, and the change of ownership will be good news for this steelworks,” said the source, adding though that a future owner should be prepared to lose a lot of money.
“To run the mill properly, it should be ramped up to 80,000-100,000 mt/month minimum, and the cost of iron ore, coke, electricity and other consumables would equal several million dollars, if not tens of millions of dollars a month, according to the source.
On top of that, according to several sources, the mill has amassed over half a billion dollars in debt comprised of unpaid carbon quotas and feedstock and some outstanding shareholder loans.
Traders and industry sources S&P Global spoke named several candidates for Dunaferr: steel production, processing and trading group Duferco; Liberty Steel Group; Ukrainian mining and steel company Metinvest; and Chinese steel company Hesteel, the owner of the Zelezara Smederevo mill in Serbia.
— Ekaterina Bouckley, Maria Tanatar, Diana Kinch

World crude steel November output falls 2.6% on year as slide continues: worldsteel
World crude steel production for the 64 countries reporting to the World Steel Association was 139.1 million mt in November 2022, a 2.6% decrease compared with November 2021.
The month’s crude steel output was hit by cutbacks due to high energy costs, particularly in the European Union; by the impact of war in Ukraine, Russia and other Commonwealth of Independent States nations; and by slowing economic growth in many nations, curbing demand.
World output has been declining since this year’s production high of 169.9 million mt in May, the worldsteel data showed. Long-term expectations are nonetheless for steel consumption to rise in coming years on population growth, which will boost demand for housing, vehicles and infrastructure.
EU output down 17.9% on year
By region, the EU (27) produced 10.5 million mt of crude steel in November, down 17.9% year on year, worldsteel said in a Dec. 22 bulletin. Other nations in Europe produced 3.2 million mt, down 25.1%. Russia, other CIS and Ukraine produced 6.5 million mt, down 24.6%. Africa produced 1.3 million mt, down 11.4%.
Asia and Oceania produced 101.4 million mt, up 2.7%. The Middle East produced 4 million mt, up 11.6%.
North America produced 8.9 million mt, down 6.3%. South America produced 3.4 million mt, down 14.3%, according to worldsteel.
The world’s top two crude steel producers both registered an increase in the month: China’s November output at 74.5 million mt was 7.3% higher than in the same month in 2021, while India’s output at 10.4% was 5.7% up year on year.
11-month total down 3.7%
Global crude steel output for the 64 countries monitored also fell in the January-November period, by 3.7% year on year, to 1.69 billion mt, worldsteel said.
The 64 countries accounted for an estimated 98% of total world output in 2021.
All of the top 10 steel producing nations recorded a fall in crude steel production in the 11-month period compared with the same period a year earlier, except for India and Iran, which are both proceeding with major steel capacity expansion programs.
China’s crude steel output in Jan-Nov, at 935.1 million mt, was 1.4% lower than in the same 2021 period, while Turkey, also in the top producers’ list, saw output slide 12.3% from a year earlier to 32.5 million mt.
India’s crude steel output in the 11-month period grew 6% year on year to 114.2 million mt, while Iran’s was up 8.5% to 27.9 million mt, worldsteel said.
Asian hot-rolled steel coil prices were unchanged Dec. 22 as liquidity dried up. Offers and bids were described as scant, with several market participants away for the year-end holidays.
Platts, part of S&P Global Commodity Insights, assessed SS400 HRC 3 mm thick up $2/mt on the day at $587/mt FOB China. On a CFR Southeast Asia basis, the same grade of coil was assessed unchanged over the same period at $583/mt.
— Diana Kinch

EU steel coil mill NLMK La Louviere aims to restart hot rolling operations early January
Belgian flat rolled steel producer NLMK La Louviere aims to resume hot rolling operations at its 1.7 million mt/year hot strip mill at the beginning of January, the plant’s parent company NLMK told S&P Global Commodity Insights Dec. 22, confirming that operations had been halted.
“We are dedicating all available resources and efforts, including winter maintenance shutdown period planned as of Dec. 16, to resuming the hot strip mill production,” said a spokesperson for Russian mining and steel company NLMK.
“We believe that restart of the production for most of our dimensions is possible in the beginning of January,” the spokesperson added.
NLMK did not specify the reason for the unplanned shutdown or when it started, but market sources said the plant had suffered “issues with their hot-strip mill and a fire.”
In its annual report for 2021, NLMK said the hot strip mill upgrade at NLMK La Louvière was ongoing with the first phase completed in 2021 and a second phase due to be completed in H2 2022 that would expand rolling capacity to 2 million mt/year.
The company declined to specify whether that project was nearing completion saying only that the hot strip mill’s capacity remained unchanged for now at 1.7 million mt/year.
NLMK La Louviere also has a 600,000 mt/year cold rolling mill, which has been temporarily offline since mid-December for planned year-end maintenance. It is due be restarted in early January, according to NLMK.
NLMK La Louviere last declared force majeure following a fire in July 2021.
The Belgium mill, a supplier of coils to the auto, machinery and construction industries, is part of NLMK Belgium Holdings, or NBH – a joint venture primarily between Belgium investment fund SOGEPA and NLMK. Apart from La Louviere, NBH owns strip mills NLMK Strasbourg (France) and NLMK Manage Steel Center (Belgium), and plate producers NLMK Clabecq (Belgium), NLMK DanSteel (Denmark) and NLMK Verona (Italy).
All the plants process slab that NLMK delivers from its Novolipetsk Iron and Steel Works in west Russia.
In January-September, NBH made 1.4 million mt of steel products, 31% more than in the same nine months of 2021.
— Ekaterina Bouckley, Benjamin Steven