

Steelmaker Salzgitter ramps up new hot dip galvanizing line
Salzgitter’s new hot dip galvanizing line no. 3 project (FV3) was ramping up after reaching operational readiness in October, the German steelmaker said Nov. 10.
The group invested around Eur200 million ($199 million) in subsidiary Salzgitter Flachstahl’s new plant, which has a planned capacity of 500,000 mt/year and will supplement the company’s two existing hot dip galvanizing lines to expand Salzgitter Flachstahl’s share in the premium flat rolled steel products segment, it said.
The plant will use an annealing furnace, which can heat and cool material faster than existing hot dip galvanizing lines and reach a higher annealing temperature, Salzgitter said.
That will support the production of high- and ultra-high-strength steel grades for use in vehicle body and chassis applications and also supply the domestic appliances sector in applications such as sophisticated surface components.
It will produce hot dip galvanized sheet with thicknesses between 0.7 mm and 2.5 mm and widths from 900-1,700 mm, with the coils of strip to have a maximum weight of 32 mt, Salzgitter said.
The plant was Salzgitter’s largest single investment of the past 10 years, it said, adding it had partnered with plant manufacturer SMS group on the project.
“The new line will further strengthen the group’s position as a leading manufacturer of premium products for national and international customers in the automobile industry and the domestic appliance sector,” it said.
“The new hot dip galvanizing line is an essential element in safeguarding the future competitiveness of Salzgitter as a center of steelmaking and the jobs that go with it, because this investment will enable us to further expand our existing high-quality product portfolio,” Salzgitter Group Management Member and Salzgitter Flachstahl CEO Ulrich Grethe said.
“In this way we can support our customers’ own ongoing development by offering the material concepts they need as well as the associated service,” Grethe said.
“Despite the adverse conditions imposed by the COVID-19 pandemic, we have remained on schedule,” Salzgitter Flachstahl Operations Director, cold rolled products Michael Bruhl said, adding that while the planning and construction stages had progressed, the company had already engaged in discussions with customers about material concepts.
“The ramp-up phase is now in full swing, and we are confident that we will very quickly be delivering the desired qualities,” Bruhl said.
Platts, part of S&P Global Commodity Insights last assessed hot-dipped galvanized coil prices in Northwest Europe at Eur765/mt ex-works Ruhr Nov. 9, down 29% since the start of 2022.
— Jacqueline Holman


EU HRC market demand remains weak, prices stabilize
Domestic prices for hot-rolled coil in the European market remained unchanged Nov. 10 as trading activity remained muted.
Platts assessed hot-rolled coil in northwest Europe stable on the day at Eur640/mt ex-works Ruhr.
A service center source reported deals and offers at the equivalent of Eur630-640/mt ex-works northern Europe.
A German distributor reported deals for smaller tonnages of coil at Eur630-650/mt ex-works Ruhr.
A steelmaker said that transactions have been made at Eur630-670/mt ex-works northern Europe. Two producers reported tradable value at Eur650/mt ex-works northern Europe each.
And a service center source estimated achievable prices at Eur630-650/mt ex-works Ruhr.
European steelmakers have continued to offer December production coil, indicating empty order books, sources said.
Distributors have been focused on reducing inventories ahead of the year end and have been showing little interest in making new deals. Some sources, however, believe that by the end of November the buyers would book some volumes for first quarter delivery to restock some specifications.
Demand from end users, including automotive industry, has also remained reduced.
“Deals are done sporadically, there is no restocking or activity rise from end users,” a producer said.
“The mills are still able to give short delivery time,” a northern European distributor said. “And some optimists believe that the first quarter will bring better demand, but I think that the outlook is still unclear and I do not believe in miracles.”
Production cuts introduced by European buyers are expected to provide some support to domestic prices.
Platts assessed southern European HRC stable on day at Eur635/mt ex-works Italy.
The assessment was based on tradable values reported at Eur630-650/mt ex-works southern Europe.
Platts is part of S&P Global Commodity Insights.
— Maria Tanatar

ArcelorMittal Q3 steel output, income falls on year; short-term outlook ‘uncertain’
Major steelmaker ArcelorMittal’s crude steel output and sales fell on-year in Q3 as prices slumped and market conditions deteriorated, forcing the company to cut higher-cost capacity, the company reported Nov. 10.
Shipments were impacted by the ongoing war in Ukraine and soaring energy costs, leaving the short term outlook uncertain and calling for caution, it said in a results release.
Crude steel production fell to 14.9 million mt in Q3, from 17.2 million mt a year earlier, while shipments fell 7.1% year on year to 13.6 million mt , mainly as a result of disruptions at ArcelorMittal Kryvyi Rih in Ukraine, impacted by the war.
The lower steel shipments largely reflected weaker demand in Europe (down 6.2%) and the war in Ukraine (down 29.2%) offset in part by NAFTA (up 2.6%), ArcelorMittal said. Excluding the impact of Ukraine, steel shipments in Q3 declined by 1% on the year, it said.
Lower steel prices, coupled with the lower shipments, brought sales down 6.2% on the year to $18.97 billion and from $22.23 billion in Q2, when prices had spiked on fears of supply shortages in the weeks following Russia’s Feb. 24 invasion of Ukraine.
Iron ore prices were 36.5% lower than in the same period last year, also contributing to the lower revenues.
Total group iron ore production fell to 10.6 million mt from 13 million mt in the same period a year earlier, although shipments from the company’s AMMC and Liberia operations remained stable at 6.9 million mt.
Q3 EBITDA slumped to $2.66 billion, from $6.06 billion a year previously. However, this came in above market expectations: a consensus of 15 brokers published Oct. 31 forecast the steelmaker would report EBITDA of $2.34 billion.
The steelmaker reported a Q3 slump in operating income per mt of product to $122/mt, from $366/mt a year ago.
Platts, part of S&P Global Commodity Insights, assessed benchmark hot-rolled coil in northwest Europe stable on the day at Eur640/mt ($643.01/mt) ex-works Ruhr Nov. 9. The price is 30.59% lower than at the beginning of the year.
“The strong market conditions enjoyed for much of the past two years deteriorated in the third quarter as seasonally lower shipments, a reduction in exceptional price levels, destocking and higher energy costs combined to put profits under pressure,” said Aditya Mittal, ArcelorMittal CEO. “The business responded quickly to the changing environment, cutting higher cost capacity to manage addressable demand and reduce fixed costs, and reducing European gas consumption by 30%”.
“The short-term outlook for the industry remains uncertain and caution is appropriate.”
Outlook
ArcelorMittal added that it has adapted its capacity for Q4 to address the weak apparent demand environment and higher energy costs, particularly in Europe.
“Apparent demand conditions are expected to improve once the current destocking phase reaches maturity,” it said. “The company is adapting its cost base during this period of low capacity utilization, optimizing energy consumption and reducing fixed costs of unproductive capacity.”
The group’s decarbonization goals remain a central part of its strategy moving forward, Mittal emphasized. In October, the group broke ground for a new direct reduced iron/electric arc furnace low-carbon emissions steelmaking plant at its Dofasco works in Ontario, Canada, supported by the regional and federal governments and which is now “hydrogen-ready”, he said.
The steelmaker also hopes to “scale up” on renewable energy, which is critical both for the decarbonization of steelmaking and for enhanced energy security, the CEO said.
AMNS India has meanwhile embarked on a growth strategy to expand its market share and play a leading role in development of the Indian steel industry, ArcelorMittal’s statement said. Expansion of the Hazira plant to around 15 million mt capacity by early 2026 is underway including automotive downstream and enhancements to iron ore operations, with capex of around $7.4 billion, it said.
— Diana Kinch

Turkish wire rod export prices fail to stick amid aggressive prices from other regions
Turkish exported mesh quality wire rod exports struggled to find buyers as competitors from other regions were undercutting prices, sources said Nov. 11.
The asking prices from Turkish mills were $650-$660/mt FOB Turkey. One mill was also reported to be offering $645/mt FOB Izmir and likely to accept $635/mt FOB, a market observer said.
A European long steel distributor said that the spread between Turkish wire rod and rebar prices was particularly low, if any. Recent rebar offers were reported at $640/mt FOB Turkey, which is only $20/mt lower than the highest wire rod offers.
“Just five to six months ago, there was a $60-$80/mt gap in price. Now it evaporated completely,” the European distributor said. “It is interesting to see equalization of rebar and wire rod prices under market pressure.”
Platts put its monthly Turkish exported wire rod assessment at $645/mt FOB on Nov. 10, down $75/mt on the month. Platts daily Turkish rebar assessment dropped $52.50/mt in the last four weeks, to $637.50/mt FOB Turkey on Nov. 10.
Despite the strong price erosion, the Turkish wire rod prices were still seen as unattractive in the export markets. This was due to the supply of cheaper wire rod from other markets, particularly Asia and Algeria, sources said.
A trader in Europe said that the Algerian wire rod was negotiable at $600/mt FOB. Prices from Southeast Asia were at $530/mt FOB. The trader cited an offer at $600/mt CIF Antwerp for December shipment, with delivery six weeks later.
Recent bookings from Indonesia closed in the range of $599-$615/mt CFR Antwerp, another trader said. Turkish suppliers quoted $645-$650/mt FOB “but no one is buying at that level,” the trader added.
As of Nov. 10, the EU tariff-free quota for Turkish wire rod import for Q4, set at 113,300 mt, had a remaining balance of 53,739 mt with the last allocation date recorded on Nov. 9. In comparison, the quota for Turkish rebar import was exhausted on Oct. 1.
“There is a lot of cheap Asian wire rod from the Far East,” another trading source said. He said that the European market was buying from Southeast Asia and some of the markets in the Mediterranean were buying from China at $600-$610/mt CFR.
The demand for wire rod stayed on the low level, sources said. “If anybody is buying, they are buying half,” a trader said.
Platts is part of S&P Global Commodity Insights.
— Wojtek Laskowski
EC could start antidumping probe into Turkish, Chinese flat steel bar imports: TCUD
The European Commission could start an antidumping investigation against flat bar imports from Turkey and China, the Turkish Steel Producers’ Association, told S&P Global Commodity Insights Nov. 9 after it received an official letter on the matter from Turkey’s Trade Ministry.
The HS code of the product in question was 7216.50.91, TCUD noted.
According to the letter, some European flat bar producers had signed a petition to the EC in favor of an investigation, which was being evaluated by the EU.
An investigation could result in antidumping duties if it is found that these flat bar product imports from the two countries are being dumped and causing damage to the European domestic market.
But when asked if it had any knowledge of the investigation or petition, the European steel association Eurofer told S&P Global it was not aware of this.
The EC had not responded to a request for additional information by the time of publication, while S&P Global also attempted to reach the Turkish Trade Ministry for additional comment, with no success.
According to the latest TCUD data shared with S&P Global, Turkey’s total flat bar exports totaled 242,600 mt from January through September 2022, down 21.5% on the year.
Turkey’s flat bar exports to the EU, however, remained relatively stable at 67,400 mt, with Romania and Germany remaining the top markets at 16,200 mt and 12,100 mt, respectively.
Turkey’s other top flat bar export destinations for the period were Morocco at 12,800 mt, Tunisia at 10,000 mt, Canada at 9,000 mt, the Dominican Republic at 7,650 mt, Peru at 7,600 mt, and the US at 6,300 mt, the data showed.
Turkish long steel pricing has been pressured by low demand in recent weeks.
Platts assessed Turkish exported rebar at $639/mt FOB Nov. 9, down from an intrayear high of $960/mt FOB, reached April 1.
Platts is a part of S&P Global Commodity Insights.
— Cenk Can
Europe, US demand deteriorates, costs exceed prices: ArcelorMittal
ArcelorMittal sees apparent demand declining significantly in Europe this year, while the impact in the US will be bigger than earlier forecast. On an annualised basis, the firm has curtailed 6 million tonnes of production in the fourth quarter, in line with addressable demand, it says.
In Europe, the region most affected by capacity cuts, inflation headwinds are leading to slower – but still positive – real consumption growth in 2022. However, the impact of destocking is significant, particularly in the second half of the year, and expected to lead to a contraction of apparent consumption by up to 7% this year, ArcelorMittal observes. In the US, destocking will have a bigger impact than previously thought, reducing apparent consumption by 1%, Kallanish notes.
Impacts on apparent consumption have been exacerbated by rapid supply chain destocking, which has seen steel prices decline at a faster rate than raw materials, leading to compression of spreads. European spot hot rolled coil prices are not covering fixed costs of marginal producers, while China spreads are anomalously low, the group observes.
The firm, which idled capacity in Q4 to address deteriorating market conditions and cut European gas consumption by 30%, expects apparent demand to improve once the current destocking phase reaches maturity.
The group’s steel shipments fell 7% on-year in Q3 to 13.6 million tonnes, while crude steel production was down 13% to 14.9mt (see separate story). Q3 sales fell 6% to $18.98 billion and net income attributable to equity holders of the parent was down a whopping 79% to $993 million.
Adam Smith Poland


Celsa boosts recycling activity
Spanish steelmaker Celsa Group says it has become the leading recycler in Spain and the second-largest in Europe, Kallanish learns from the company’s latest sustainability report.
Celsa melted 7.01 million tonnes of ferrous scrap to produce almost 6.6mt of long steel in 2021. The group also recycled 73,000t of non-ferrous metals, 860t of plastics and more than 2.6mt of co-products.
According to the report, 96.5% of Celsa’s long products are made of recycled steel, while the steelmaker recovered 94% of the total waste generated in its processes. Another important achievement for the company is that it reduced water consumption by around 40% and also avoided the emission of 12mt of CO2.
“Since the beginning of our decarbonisation plan in 2015, we reduced almost 22% of CO2 emissions from our production plants,” Celsa observes. “In 2021, these reached 263 kg per tonne or 36.8% below the average for the European Union steel sector.”
The company’s target is to reach 98% circularity by 2030 and become a completely circular and zero waste company in 2050.
Todor Kirkov Bulgaria

Europe might see more anti-dumping cases as trade flows shift, EUROMETAL hears


The European steel market was likely to face a new wave of anti-dumping cases concerning flat steel products, delegates were told at EUROMETAL’s International Trade Day in Antwerp on Thursday November 10.
Russia’s invasion of Ukraine in February 2022 interrupted traditional supply chains of steel products and raw materials, Fastmarkets heard.
Ukraine’s steel export volumes have dropped drastically in 2022 since it lost a large portion of its steelmaking capacities due to military action, while blockades of key ports on the Azov and Black Seas have interrupted traditional logistics routes.
During the first nine months of 2021, Ukraine exported 11.89 million tonnes of metal products by rail, according to data from Ukrzaliznytsia, a Ukrainian state-owned rail transport company. That included transportation of products by railway to sea ports for export.
During the corresponding period of 2022, Ukraine’s exports by rail amounted to only 4.7 million tonnes.
Ukraine exported 615,442 tonnes of hot-rolled flat steel products to the EU in 2021, but in the first eight months of 2022 deliveries from Ukraine to the bloc fell to 376,165 tonnes, according to European steel association Eurofer.
Imports of Russia-origin finished steel products were banned in the EU in spring this year as a response to Russia’s military aggression.
The most recent European Commission sanctions package, which included two-year quotas for steel semi-finished products originating in Russia, was adopted in early October.
Russia supplied about 1.98 million tonnes of hot-rolled flat steel products to the EU in 2021, but in January-August 2022 the corresponding import volumes from Russia amounted to only 382,430 tonnes, according to Eurofer.
With traditional volumes of HRC from Ukraine and Russia missing from the market, European buyers have started to import more steel from Southeast Asia recently, Eurofer statistics showed.
Notably, hot-rolled flat steel imports from Japan to the EU amounted to 739,255 tonnes in January-August 2022, compared with 591,355 tonnes during the entire year of 2021.
HRC deliveries from South Korea to the EU also increased, amounting to 564,077 tonnes in January-August 2022, versus 463,487 tonnes in the whole year of 2021.
Deliveries from Vietnam, Taiwan and India have also increased in 2022.
HRC offers from Southeast Asia to Southern Europe have been reported at €600-610 ($603-613) per tonne CFR recently.
Despite the anti-dumping cases and safeguard measures in place, steel import volumes to the EU have remained high, adding to the pressure on the already-weak European steel market.
Yuriy Rudyuk, a partner in law firm Van Bael & Bellis, has said that a new wave of anti-dumping trade cases against hot-rolled flat steel products was likely, considering the persistently high import penetration into the EU market.
European steel producers were struggling to compete with cheaper imports because they faced significantly higher production costs, including carbon emissions allowances.
“Overseas steel suppliers benefit from much lower energy prices and are not exposed to carbon costs,” a steel mill source told Fastmarkets.
Domestic HRC prices in Europe have been falling consistently in the second half of 2022 due to a toxic combination of low demand, high inventories and pressure from imports, sources said.
Fastmarkets calculated its daily steel HRC index, domestic, ex-works Northern Europe, at €648.33 per tonne on Thursday, up by €0.35 per tonne from €647.98 per tonne on November 9.
The latest calculation of the index was up by €2.08 per tonne week on week but down by €79.17 per tonne month on month.
Published by: Julia Bolotova

EU needs traders to balance mill supply
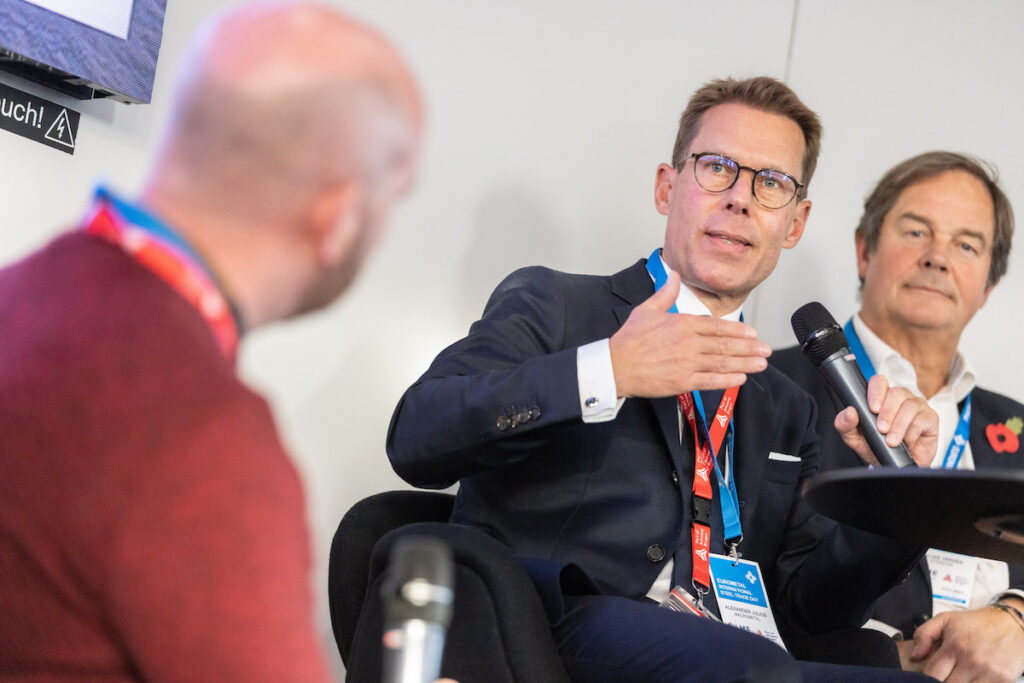
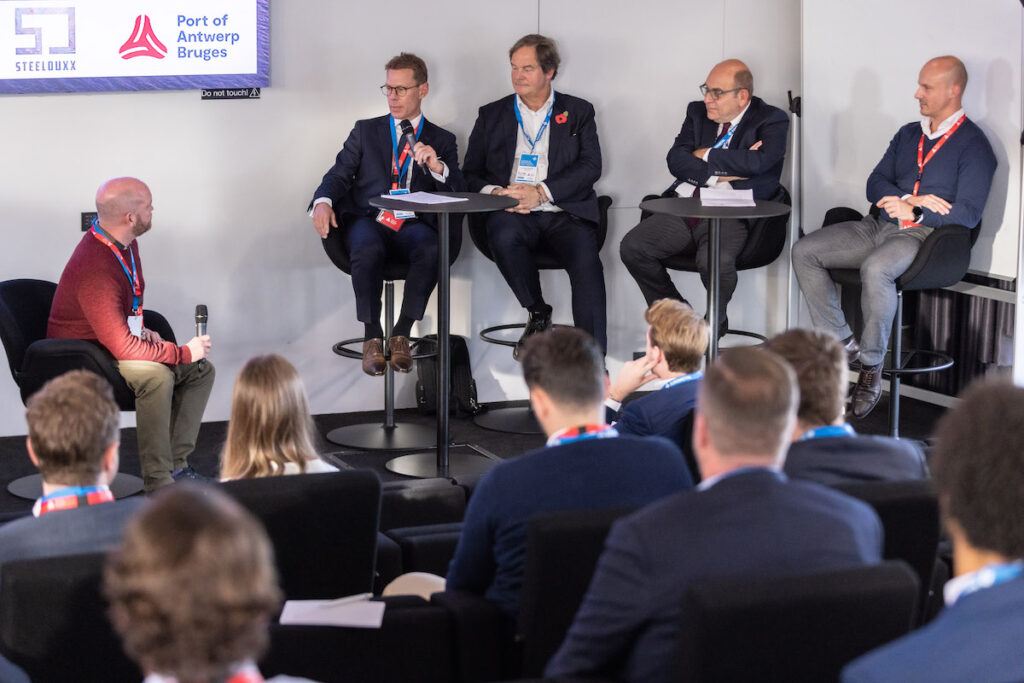
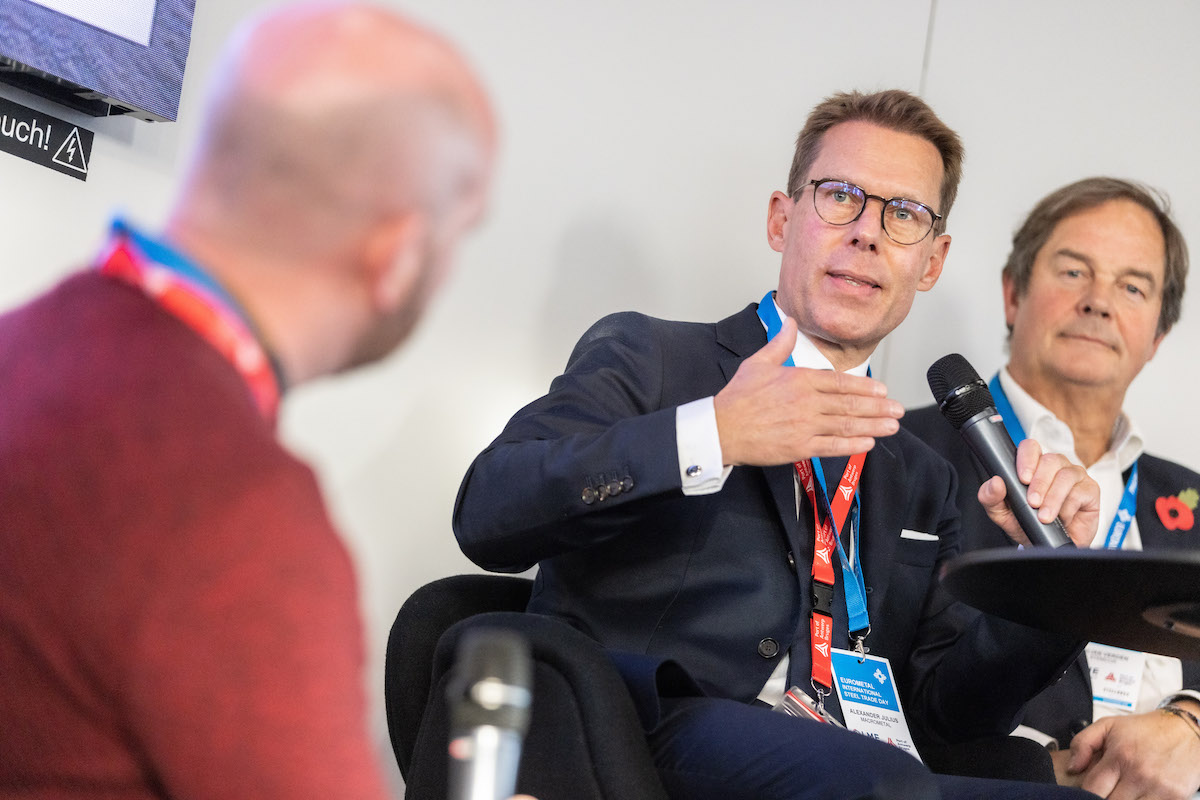
Importers of steel into the European Union are not harming their domestic markets, let alone intending to do so, but are a valuable supplement to local mills, traders claimed at Thursday’s EUROMETAL conference in Antwerp.
“Buying domestic is the natural way, and we are completing the picture,” Alexander Julius of MacroMetals stated at the event attended by Kallanish. He referred to periods when local mills could not supply sufficiently, like in 2021 when the post-Covid resurgence in demand gained momentum. “Mills underestimate the memory of customers of such periods, when we jumped in,” Julius said during the closing panel discussion of EUROMETAL’s International Steel Trade Day.
This was confirmed by Stemcor’s Julian Verden and Steelforce’s Laurent Taylor. “We do remember what happened last year,” Taylor reiterated, and advised that “nobody should buy 100% local, or 100% import”. He underlined that import buying is a skill that requires research, and a tool that can be used in purchasing negotiations.
Verden described the role of a trader as “an arm of the customer” and an “extension of mills”. Foreign producers exporting into the EU “would operate foreign offices elsewhere, but for them it works better with an external agent [EU trader] than having ongoing costs with permanent staff”.
Markus Fix of Ruhr-based service centre DM Stahl complemented the panel when he stated that “you traders were reliable partners when mills failed”. He highlighted their role as buyers of big volumes, to be distributed among buyers of various sizes. Against that, “smaller service centres would not be in the position to order a vessel of 30,000 tonnes,” he said.
Tayfun Iseri, who represents Turkish importers as well as mills, as president of Turkish flat steel association Yisad, concurred. Speaking of his experience in the US, he pointed out that “distributors, service centres and steel users just would not know how to import”.
Christian Koehl Germany

Italian rebar contract values increase amid uncertainty
Italian rebar contract prices are increasing by some €20/tonne ($20). Sources in the market tell Kallanish that steelmakers started by hiking values moderately on Monday but are since asking for a €70-80/t increase compared to October levels. The move is designed to bring to an end the continuous slide in prices seen since last month.
Rebar makers are now all asking for €580/t base ex-works. At the beginning of the week, they were quoting €520-530/t. Contract values are hovering at €500-530/t base ex-works. Including size extras, domestic rebar prices are at €760-790/t ex-works. Mesh asking prices are at €650/t ex-works base, depending on volumes, sources suggest.
Distributors reported good demand in October. Thanks to the rebar price decline last month, demand resumed and the market was more dynamic compared to September. November however has been slow so far. Those who spoke to Kallanish believe the rebar price increases will hamper sales to end users, while all other construction material prices, including timber, are falling.
Two sources say thanks to last month’s improved demand and lower rebar prices, they bought higher volumes in October compared to September. Sources believe the current increases will stop the price decline but others forecast that by mid-November rebar prices will begin to fall again. This is also in view of reduced activity in December, which will see only ten effective days of work before the holiday season starts.
Natalia Capra France