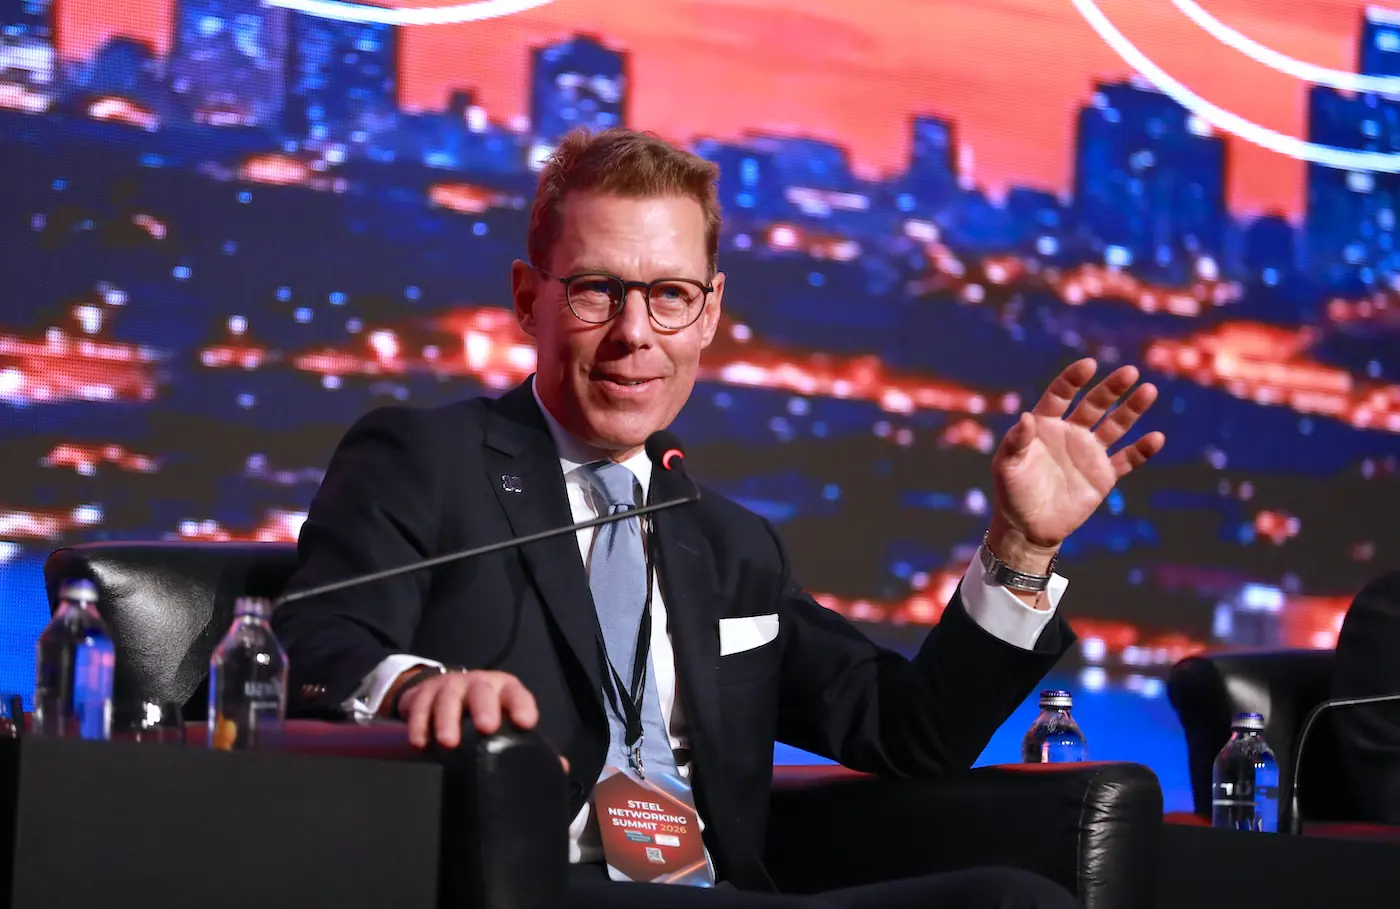
EUROMETAL President Alexander M. Julius stated during his speech at Steel Networking Summit 2026 that the disparity between the European Union’s measures on steel imports and the trade conditions applied to finished products containing steel weakens the competitiveness of European manufacturers. Julius emphasized the need to ensure a level playing field across the entire steel value chain.
Speaking at Steel Networking Summit 2026, organized in İstanbul by the Steel Exporters’ Association (ÇİB), EUROMETAL President Alexander M. Julius discussed trade measures in the European steel market, imports of steel-containing products and the impact of the Carbon Border Adjustment Mechanism (CBAM) on the manufacturing industry.
Julius stated that the EU has developed anti-dumping measures, countervailing duties and safeguard measures on steel imports over the past 25 years, while industries that use steel as an input have not received comparable protection against imported finished products. He emphasized that this disparity between steel producers and steel-using manufacturers should be taken into account when assessing the decline in European steel demand.
Protection gap between steel and steel-containing products
Julius’ presentation outlined an annual duty-free quota of 18.3 million tons across 30 product categories for steel imports into the EU, with a 50% duty applied to imports exceeding the quota from July 1, 2026. Anti-dumping and countervailing measures against subsidies were also identified as additional trade defense instruments for steel imports.
For many industrial products containing steel, typical most-favored-nation (MFN) tariffs were reported to range from 0% to 2.7%. These products were described as having no industry-wide safeguard quota comparable to that applied to steel, while trade defense measures remained limited to specific products.
The presentation also noted that, as of the end of 2025, approximately one-third of the EU’s 232 trade defense measures in force concerned iron and steel.
Julius stated that while protection measures and carbon costs on steel inputs are increasing, European companies using these inputs must compete with finished products imported at low tariff rates. He noted that this situation increases cost pressures on steel-using industries.
Weakening manufacturing activity also affects steel demand
Highlighting the importance of maintaining the competitiveness of manufacturers that purchase steel, Julius stated that an approach focused solely on protecting steel production is insufficient to address challenges further along the value chain.
Julius noted that higher steel prices and carbon costs are intended to support investment in low-carbon production. However, he emphasized that the failure to balance competitive conditions with imported steel-containing products places pressure on manufacturing activities in Europe.
He stressed that weak demand in the European steel industry cannot be assessed independently of the loss of market share experienced by steel-consuming industries.
Products previously destined for the US and Canada are being redirected to the EU
Julius stated that trade measures introduced by the US and Canada affect not only direct steel trade but also trade in steel-containing products. He explained that products facing restricted access to these markets are being redirected to alternative destinations, increasing import pressure on the EU.
According to an assessment in the presentation based on EUROMETAL and Metals Consulting International sources, trade flows previously destined for the US and Canada, representing more than 15% of global trade in steel derivative products, have been partially redirected to the EU.
The presentation highlighted Section 232 measures and melt and pour requirements in the US market, as well as relevant customs regulations in Canada. It also noted that the EU’s lower trade barriers for steel-containing products increase the risk of trade diversion and dumping.
Carbon costs also create competitive pressure on exports
Julius stated that CBAM represents an additional cost factor for steel-using manufacturers, as companies producing in Europe must reflect carbon costs and higher input costs resulting from trade measures in their product prices.
He explained that these companies face difficulties competing in third-country markets where comparable costs do not apply. Julius noted that the issue is not limited to imports into the EU but also affects Europe’s export capacity.
According to the latest information available to EUROMETAL, Julius stated that no mechanism was being planned to compensate for carbon costs on exports. He added that EUROMETAL had proposed an approach that could offset these costs in a manner similar to the treatment of value-added tax (VAT) on exports.
Criticism of CBAM calculation methods
The presentation also included technical assessments of CBAM’s financial phase, which began on January 1, 2026. A section based on Macrometal data examined weighted average emissions calculated using existing production methods and the benchmarks used to determine the equivalent of free allowances.
The presentation highlighted criticism that country-specific default emissions values had been increased without clear justification and that certain production method definitions did not adequately reflect actual production conditions.
The additional 10% applied to country-specific values in 2026 and uncertainties surrounding emissions monitoring methodologies were also among the issues raised.
EUROMETAL’s call receives support from more than 500 organizations
Julius stated that EUROMETAL launched a call to action in April to protect the steel value chain. He noted that more than 500 companies, national federations and industry organizations had supported the initiative.
He explained that the initiative aims to inform decision-makers in Brussels and at national level about the pressure arising from imports of steel-containing products. Julius added that EUROMETAL is working to demonstrate the increase in imports and its impact on manufacturing through data requested by policymakers.
Highlighting the different trends in imports of finished steel products and steel-containing products, Julius stated that EUROMETAL had recently observed a quarterly increase of approximately 3% in imports of steel-containing products.
Türkiye’s hot rolled coil quota also discussed
During his speech, Julius also addressed Türkiye’s hot rolled coil (HRC) exports to the EU, examining the impact of the new quota system on trade flows and importers’ costs.
The presentation showed Türkiye’s country-specific HRC quota at 161,000 tons for each of the third and fourth quarters of 2026. An additional quota pool of 121,000 tons was reported for countries covered by free trade agreements in each period.
HRC imports from Türkiye into the EU totaled 289,000 tons during July and August. Based on the combined country-specific quota and additional quota pool, the presentation indicated an excess of approximately 7,000 tons.
Regarding access to the additional quota pool, Türkiye was highlighted in the third quarter, while Türkiye and India were identified as key countries in the fourth quarter. Julius stated that uncertainties over quota availability affect import decisions and competition between countries.
Julius also noted that Türkiye has improved its production capacity and quality in recent years, enabling it to serve industries such as automotive manufacturing to a greater extent. He emphasized that this development should be considered when assessing trade relations with Europe.
He added that the extent to which increasing costs can be passed on to end users and the sustainability of current price levels remain important questions.