


Struggling EU steel market braces for disruption after Trump tariff threats
While speaking with reporters on Monday February 3, Trump stated that tariffs on EU goods would happen “pretty soon” because of what he perceives as a negative trade balance between the US and EU.
His comments have intensified speculation over the impact of potential tariffs targeting European ferrous exports to the US.
They also sparked a response from the president of the European Commission, Ursula von der Leyen, who said the bloc is ready to engage in “tough negotiations” with Trump.
How could steel tariffs affect Europe?
Europe’s steel industry, already grappling with weak domestic demand, high costs and overcapacity concerns, now faces the added pressure of potential disruptions to a key export market.
The EU is a clear net exporter of steel to the US. Exports of iron and steel products under harmonized standards (HS) code 72 from the EU to the US totaled 3.60 million tonnes in January-November 2024, while the EU imported 797,980 tonnes from the US over the same period, according to data from Eurostat, compiled by the Global Trade Tracker (GTT).
Total global exports from the EU under code 72 were 37 million tonnes in January-November 2024, with ferrous scrap exports making up 20.80 million tonnes. The US was the second largest recipient of EU iron and steel exports.
“It can really have an impact, because there are some mills in Europe who are exporting to the US. If they can’t anymore, prices in Europe could collapse,” a European steel trader told Fastmarkets. “Everybody is unsure.”
But other European steel market sources remained reserved in their assessments of the impact of any possible tariffs on the EU market.
“We’ll see what the actual tariffs will look like,” a buyer in Europe said. The source questioned the competitiveness of EU exports and said they did not think tariffs would have a direct impact on steel sales.
“What we have to be conscious of is the potential diversion of trade flows into Europe in case Trump decides to implement massive tariffs on Asian steel,” the buyer in Europe said.
A second trader expressed less concern over Trump’s threats, noting that the US is a net importer of steel and will still need foreign materials.
The US’ negative trade balance might lead to tariffs driving up inland steel prices within the US, with its industry bearing the brunt of the cost, the second trader said.
“They are not able to produce [enough to satisfy all] the steel demand in the country, so they need the imports anyway,” they added.
But the EU faces stiff competition from other large suppliers to the US, such as Canada, Brazil, Mexico, South Korea and Vietnam.
Of the EU steel exports to the US, the majority of the volume was flat-rolled steel products under HS code 7210 and flat-rolled alloy steel products under code 7225. Next up was ferrous scrap under HS code 7204, with 331,081 tonnes.
US steelmakers typically import prime-grade ferrous scrap from EU countries, such as No1 busheling and No1 bundles material, which are high yield and low in impurity, making them ideal for use in flat steel production at US electric-arc furnaces (EAFs).
Fastmarkets senior analyst Alex Kershaw noted that trade flows could shift significantly if the tariffs are implemented and if the EU responds with retaliatory measures, with EU scrap exporters likely to redirect volumes to alternative markets such as Turkey, Egypt or India.
Steel exports represent a much larger share of EU exports to the US than scrap, meaning that steel trading patterns could also shift dramatically if tariffs are imposed, he added.
How well are EU markets protected?
Should the US hit EU steel with fresh tariffs, some believe that the European market has a stronger defense now than in 2018, after the unilateral US decision to impose tariffs of 25% on steel and 10% on aluminium imports from Canada, Mexico and the EU under Section 232.
“The EU market is better protected now. And will be even better shielded as of April 1, when reviewed safeguard measures come into force,” a second buyer said.
Indeed, the EU’s existing steel safeguards measures were first implemented in 2018 in response to the US Section 232 tariffs.
On October 30, 2021, the US and the EU then agreed to replace Section 232 steel and aluminium tariffs against the bloc’s 27 countries with tariff-rate quotas.
The measures have been extended several times and are currently under review, expected to be concluded by March 31, with any adjustments to the current measures expected to come into force the following month.
Market participants in Europe said the review might involve a reduction in quarterly hot-rolled coil quota allowances and the introduction of new individual quotas for certain origins.
UK trade relations: a different approach?
Trump’s stance on UK trade remains ambiguous. The US president has spoken of having a positive relationship with British Prime Minister Sir Keir Starmer and suggested that trade tensions with the UK might be more easily resolved than with the EU.
“The UK is out of line. But I’m sure that one, I think that one, can be worked out,” Trump said, hinting at the possibility of negotiations to avoid the same punitive measures that may hit the EU.
While UK exporters have been closely monitoring developments, many remain cautious given the volatility of Trump’s trade policies.
The UK is a much smaller exporter of iron and steel to the US compared with the EU, which suggests that tariffs targeting the EU could have a much more pronounced impact on the European bloc’s steel market than it would the UK.
In January-November 2024, the UK exported 190,351 tonnes of iron and steel products to the US under HS code 72, including 75,386 tonnes of ferrous scrap, according to data compiled by GTT.
For context, the UK’s total global iron and steel exports amounted to 9.15 million tonnes over the period, with ferrous scrap making up a whopping 6.92 million tonnes.
The US was only in 12th position among all buyers of UK ferrous products under code 72 over the eleven-month period. On the other hand, the UK imported only 9,344 tonnes of US ferrous products under the same HS code, according to data from the GTT, from a total import volume of 5.89 million tonnes.
This data suggests a very wide imbalance in the UK-US steel trade, even if at much smaller outright volumes than the EU-US link.
So is the UK going to be safe from tariffs? To what extent will Trump apply tariffs to EU goods? And will these also affect ferrous shipments?
There are many questions, but for now, very few answers. Until more concrete policy is determined by the US government, steel market participants across Europe are set to remain in a cautious wait-and-see mode.

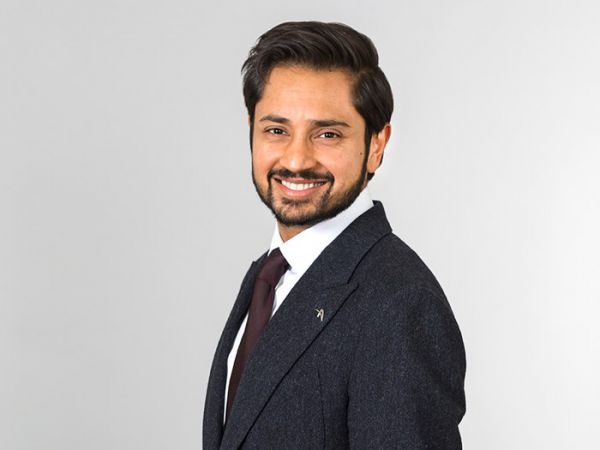
Policies to accelerate steel decarbonization in Europe ‘critical’ in 2025: ArcelorMittal CEO
“Looking to the year ahead, while [steel] inventory levels are low and apparent demand is expected to improve, our industry continues to be characterized by global overcapacity, and we are supportive of policy to address this in our markets,” ArcelorMittal chief executive officer Aditya Mittal said in a Thursday press release accompanying the company’s fourth-quarter financial results.
“Further action is particularly necessary in Europe, which was impacted by increased imports in 2024, further adding to the pressures on European manufacturing. It is critical that we see progress in 2025 both in providing necessary emergency relief and creating a policy environment that incentivizes the investment required to accelerate decarbonization in Europe,” Mittal added.
In 2025, green steel growth is largely expected to be driven by stricter environmental regulations, increasing pressure from consumers and investors for sustainable products, and the EU’s commitment to achieving carbon neutrality, Fastmarkets reported.
ArcelorMittal provided an update on its decarbonization plans in Europe last November, pointing out that the unfavorable economic situation in Europe and uncertainty around environmental policies slow the transition to green steelmaking.
As a result, the company’s decarbonization investments in Europe are progressing at a slower pace than initially envisioned, ArcelorMittal said.
ArcelorMittal has made significant progress in decarbonizing its operations and remains committed to its green steelmaking goals, the company said in the Thursday release.
For instance, since 2018, ArcelorMittal’s absolute emissions (Scope 1 and 2) have decreased by about 50%, primarily due to footprint and portfolio optimization of some of its most carbon-intensive capacities, the release said.
In addition, electric-arc furnaces (EAFs) comprise 25% of the company’s global production, up from 19% in 2018, ArcelorMittal chief executive officer Aditya Mittal said in the release.
Since 2018, the company has invested $1 billion in decarbonization projects globally. These projects include the decarbonization of steelmaking operations in Gijón and Sestao in Spain, as well as launching ArcelorMittal’s green steel brand XCarb for recycled and renewably produced low-carbon-emission steel.
XCarb sales increased from 0.2 million tonnes in 2023 to 0.4 million tonnes in 2024, the company said.
The market for steel with reduced carbon emissions is still evolving in Europe, and sources expect more uptake of “green steel” across supply chains once environmental regulations — such as the CBAM — are implemented.
ArcelorMittal’s current decarbonization investments are focused on ramping up production of high-quality low-carbon flat products in Sestao and the new EAF construction in Gijón.
Notably, by 2026, flat steel production is targeted to reach 1.6 million tonnes per year at the plant in Sestao, where ArcelorMittal runs two EAFs. After ramp-up is completed, much of Sestao’s portfolio will be XCarb-brand low-carbon-emission steel.
According to market sources, HRC from Sestao has a carbon footprint of 580 kg of CO2 per 1 tonne of steel under Scope 1, 2 and upstream Scope 3.
Fastmarkets’ latest weekly assessment of the green steel domestic, flat-rolled, differential to HRC index, exw Northern Europe was €100-200 per tonne on January 30, stable since December 12.
Fastmarkets’ methodology defines European green steel as “steel produced with Scope 1, 2 & 3 emissions at a maximum of 0.8 tonne of CO2 per tonne of steel.”
Julia Bolotova in Brussels contributed to this report.

EUROFER: steel demand forecast to recover by 3.8% in 2025
EU apparent steel consumption should recover 2.2% on-year in 2025, provided the industrial outlook improves and global tensions ease, Eurofer says in its latest outlook seen by Kallanish. However, this is a downward revision from the previous forecast after 2024 consumption is also expected to have declined deeper than previously thought.
2024 demand is expected to have fallen 2.3% versus 2023, compared to Eurofer’s forecast last October of a 1.8% drop. Demand in 2025 had been forecast then to recover by 3.8%.
In any case, no improvement in apparent steel consumption is expected in the first quarter, and consumption volumes are expected to remain far below pre-pandemic levels.
Q3 2024 consumption is confirmed to have declined 0.9% on-year, while domestic deliveries fell 2.3%. EU steel imports inched up 1% in Q3, maintaining a high, 28% market share. EU exports rose 4%, driven by flat products.
Expectations for the recovery in steel-using sector output in 2025 have also been revised down. This is now expected to grow 0.9% versus the October forecast of 1.6%. Steel-using sector output in 2024 is thought to have declined 3.3% versus the previous forecast for a 2.7% drop, due mainly to expected drops in construction and automotive output.
Economic uncertainty will continue to take its toll in the coming quarters despite monetary easing by the European Central Bank, the effects of which will not be fully visible in the short term, Eurofer notes.
The Steel Weighted Industrial Production (SWIP) index dropped for the third consecutive quarter in Q3, by 4.1% on-year.
The outlook remains dominated by “a worsening combination of uncertainties in energy prices, weak manufacturing sectors’ conditions, inflation still above target levels, severe geopolitical tensions and economic challenges, including possible future trade tensions,” Eurofer notes.
Its director general, Axel Eggert, adds: ““We can no longer cope with a situation where external factors beyond steelmakers’ control – massive steel dumping, uncompetitive energy and carbon prices, collapsing demand, trade and geopolitical tensions – are structurally undermining our industry. The initiatives the European Commission will put forward in the coming weeks will determine the future of the EU steel industry, its quality jobs and, with it, the future of EU manufacturing, competitiveness and security.”
Adam Smith Poland


Sülzle Stahlpartner launches carbon-reduced rebar brand
German rebar distribution and bending group Sülzle Stahlpartner has introduced a carbon-reduced product line named STOOX PCF Steel, validated by auditing organisation TÜV.
According to a company spokesman, the move follows increasing inquiries from construction projects, especially in the public sector. Stoox will already be used in an ongoing project, the construction of the U5 underground train line in Hamburg, to which Sülzle is delivering pre-fabricated, custom-made reinforcement cages.
Sülzle claims that Stoox has an average carbon footprint of less than 400kg CO2 equivalent per tonne, undercutting the original target of 500kg CO2e/tonne, as is requested by the awarding authority.
Sülzle appears to be the first German distributor of rebar to announce such a label. It became a member of the Responsible Steel movement one year ago. “We are certainly the first company to have the entire process for determining the product carbon footprint backed by a TÜV certification,” the spokesman tells Kallanish.
Sülzle receives its rebar from various mills that document the carbon footprint of their production; the TÜV certificate also covers the subsequent logistics and fabrication, the spokesman explains.
Hamburg’s ARGE U5 project, a joint venture between Ed. Züblin AG and Wayss & Freytag Ingenieurbau AG, is meant to be a lighthouse project for environmentally sound construction. It aims to reduce conventional CO2 emissions during the U5 construction by 70%.
Christian Koehl Germany

Steel construction at risk: the threat of substitution if emissions reduction falls short
The construction industry could look to substitute steel for other materials to decarbonise the sector if steelmaking emissions are not reduced quickly and competitively, Kallanish learns from a report by the Energy Transitions Commission (ETC).
Its “achieving zero-carbon buildings” report says decarbonising construction requires either the decarbonising of the production of building material inputs such as cement, concrete, steel, bricks, glass, aluminium, or reducing demand for high-carbon material inputs, by using materials more efficiently or substituting lower-carbon materials.
It notes that 95% of embodied carbon emissions are from the production of material inputs, cement, concrete and steel, with the building’s structure accounting for over half of these.
Production of primary and secondary steel accounts for around 7% of global emissions, while the built environment drives around 50% of steel use by mass.
It notes achieving significant emissions reductions via supply decarbonisation will take time, with only little progress likely to be feasible over the next decade. It says this is because the cost of near-zero-emissions primary steel production will be significantly higher than conventional production for at least the next decade, and technologies are still on the cusp of reaching commercial scale.
Lengthy 20-40-year asset lifetimes imply a slow shift to low-carbon technologies, unless high carbon prices force these offline; ETC therefore highlights the importance of reducing building demand for steel.
Reducing material intensity through different building design choices and innovative construction techniques, and substituting for lower-carbon materials could in principle reduce steel demand by 15% to 2050.
Altogether, these demand efficiency strategies could in theory reduce cumulative demand for cement, concrete and steel by 30-35% by 2050.
ETC notes that alternative materials such as timber should be sustainably sourced and dealt with correctly at end-of-life in order to have a lower whole-life carbon impact, Without strict guidance, replacing concrete and steel with mass timber could become a net GHG-emitter.
It says combining the MPP pathways for decarbonisation of material production and opportunities to reduce demand for materials suggests that the total embodied carbon from the construction of new buildings to 2050 could be 65% lower. The vast majority of this reduction is achieved via the decarbonisation of material production.
Carbon pricing will be essential to drive heavy industry decarbonisation since, while decarbonisation is clearly technically possible, it will entail a green premium. MPP estimates suggest the cost today of producing zero carbon steel could be around 50% higher and while these increases will only add about 1.5-3% to the total cost of construction, developers will not voluntarily absorb these costs unless forced to do so via carbon prices or regulations.
Carrie Bone UK

ArcelorMittal reduces shipments, expects elusive restocking in 2025
ArcelorMittal expects higher apparent demand on-year in 2025, with restocking activity to supplement real demand improvement amid low inventory levels, especially in Europe. This comes after the firm’s shipments and revenue dropped in 2024, despite improving in the fourth quarter, Kallanish notes.
The group expressed a similar expectation at the same time last year, but restocking ultimately failed to materialise in 2024 (see Kallanish passim).
Q4 steel shipments and crude steel production each rose 2% on-year to 13.5 million tonnes and 14mt respectively. Revenue grew 1% to $14.7 billion, while net loss narrowed 87% and Ebitda grew 14% to $390 million and $1.65 billion respectively.
Steel shipments in 2024 fell, but only by 2% on-year, to 54.3mt, with crude steel production flat at 57.9mt. Revenue fell 9% to $62.4 billion and Ebitda was down 19% to $7.05 billion. However, net income surged 46% to $1.34 billion. The previous year’s earnings were impacted by the disposal of the Kazakhstan operations and impairment of the firm’s investment in the Acciaierie d’Italia joint venture.
Despite the anticipated demand improvement, global overcapacity remains an issue. “Further action is particularly necessary in Europe, which was impacted by increased imports in 2024, further adding to the pressures on European manufacturing. It is critical that we see progress in 2025 both in providing necessary emergency relief and creating a policy environment that incentivises the investment required to accelerate decarbonisation in Europe,” says ArcelorMittal chief executive Aditya Mittal.
Although 2024 was beset by economic challenges, ArcelorMittal’s $130/tonne Ebitda was still higher than the five-year-average pre-Covid. The firm is focused on tapping demand in the Brazil, India and US markets. Electric arc furnaces now comprise 25% of its global production, up from 19% in 2018.
The company expects world ex-China apparent steel consumption to grow by 2.5-3.5% on-year in 2025, with Europe and US flat products consumption to rise 0-2% and 1-3% respectively.
Adam Smith Poland