


UK proposes extending antidumping duties on Chinese organic coated steel
The UK Trade Remedies Authority published its initial findings late Feb. 25, proposing that antidumping and countervailing measures on organic coated steel, or OCS, imported from China be maintained for an additional five years, until May 4, 2029. This proposal aims to protect the UK industry from potential harm that could occur if these measures were removed.
OCS is used to maintain the durability of various structures, particularly in construction, as well as in metal furniture, heating and ventilation systems, and a range of domestic appliances.
In its statement, the TRA concluded that removing these measures would likely result in a recurrence of dumping and subsidization practices, which have historically undermined domestic production. Since their implementation in 2013, these measures have proven effective in keeping Chinese OCS imports below 1,000 mt annually.
Tata Steel UK is the sole producer of OCS in the UK, manufacturing it at the Shotton facility in North Wales. The company contributes approximately GBP 222 million ($280 million) annually through OCS sales and employs around 8,100 individuals across its various operations.
This transition review was initiated on April 15, 2024, examining data from the period April 1, 2023, to March 31, 2024, with the injury assessment covering from April 1, 2020, to March 31, 2024.
Currently, antidumping duties imposed on Chinese OCS imports range from 5.9% to 26.1%, while countervailing duties vary from 13.7% to 44.7%, depending on the specific exporter.
The TRA has opened a window for businesses potentially impacted by these findings to voice their opinions. Interested parties can submit comments to the TRA via the TRA’s public file until March 18, 2025, allowing for a collaborative approach to shaping the future of the UK OCS market.
The UK government and TRA view these measures as crucial in maintaining a level playing field for UK manufacturers and ensuring the sustainability of local production. Last week, the UK government accepted the recommendation to maintain an antidumping measure on imports of corrosion-resistant steel from China for an additional five years.
Platts, part of S&P Global Commodity Insights, assessed the weekly steel hot-rolled coil (HRC) UK at GBP530/mt DDP West Midlands Feb. 20, stable week over week.


Sweden’s SSAB to supply low carbon steel to Italian crane manufacturer Fassi
Swedish steelmaker SSAB has reached an agreement with Italian crane manufacturer Fassi to supply it with low-carbon steel.
The deal includes steel produced from both iron ore and recycled scrap, SSAB Fossil-free™ steel and SSAB Zero™, which will be used in Fassi’s hydraulic and truck-mounted cranes.
SSAB Zero™ is made using recycled steel and produced with fossil-free electricity and biogas; it has been available for commercial deliveries since 2023. SSAB has also developed fossil-free steel made from iron ore using HYBRIT technology, which employs hydrogen and fossil-free energy instead of coal in the steelmaking process.
The two companies did not disclose the amount of steel included in the deal.
“We look forward to deepening our collaboration with Fassi by delivering premium high-strength steel produced with a significantly lower carbon footprint,” said Per Elfgren, head of SSAB Special Steels.
Fassi CEO Giovanni Fassi added: “Innovation is a projection towards the future. And there is no future without sustainability.”
Fassi is one of the world’s largest loader crane manufacturers. The two companies are already in partnership, with Fassi utilizing SSAB’s Strenx steel, which the company claims adds lifting power, reduces weight and extends reach for its heavy-duty cranes.
Platts, part of S&P Global Commodity Insights, assessed Northwest European hot-rolled coil carbon-accounted at Eur680/mt ex-works Ruhr Feb. 25, stable day over day.
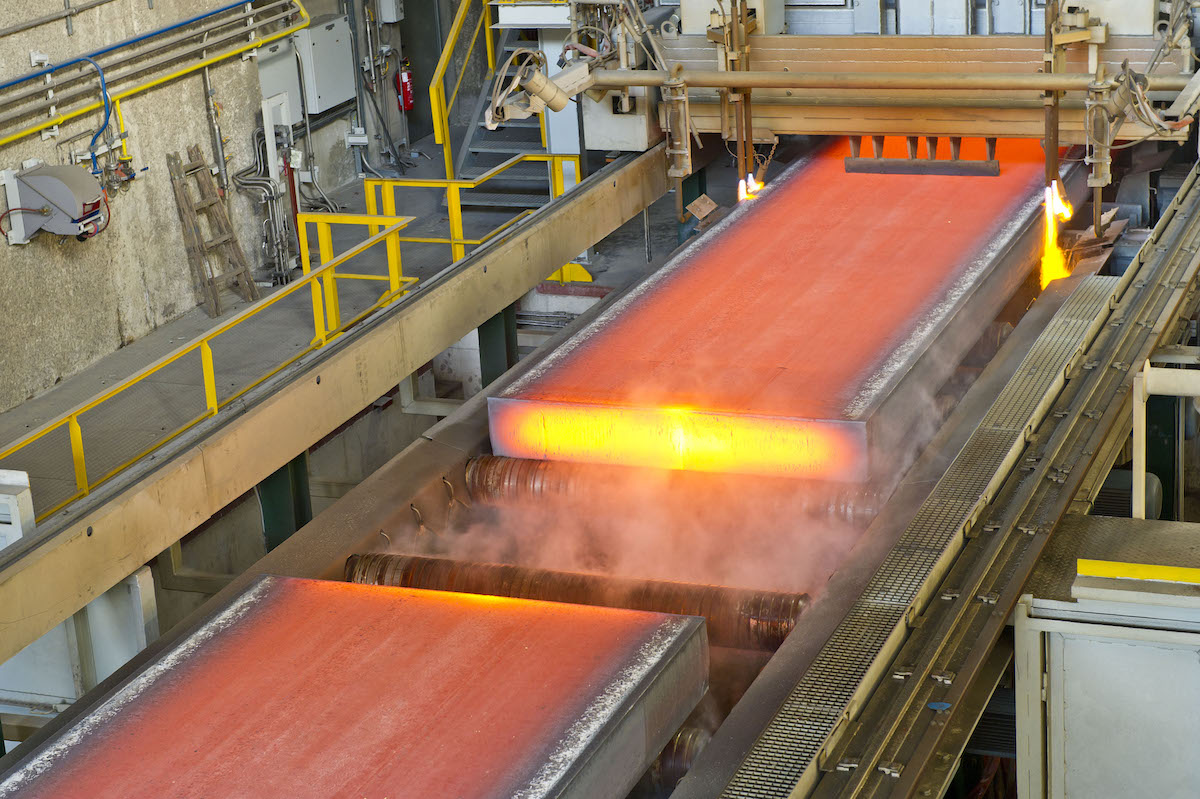
Global crude steel production declines year on year in January
Sizable falls in output were reported by top producing countries Iran, Germany, South Korea, Japan and China in January compared with the same period the year prior. India and the US were the only top ten producing countries to show growth in crude steel production in January year on year, according to worldsteel on Tuesday February 25.

China and India: Diverging trends among leading producers
China, the world’s largest steel producer, had its estimated output fall by 5.6% to 81.9 million tonnes in January 2025 compared with January 2024. The decline is driven by weaker domestic demand amid ongoing property sector struggles, slowing infrastructure investment and intensified environmental regulations to curb carbon emissions.
Crude steel production in China has been on a downward trend since it reached the historical high of 1.07 billion tonnes in 2020.
The country’s steel industry is also facing trade protectionist measures and anti-dumping probes.
Rebar producers were reported to have shifted crude steel capacity to produce semi-finished products due to weakening demand and decreased profit in the fourth quarter of 2024, but member mills of the China Iron & Steel Association (CISA) reported higher steel production rates in the last 11 days of January following the country’s observance of the Lunar New Year holiday.
The world’s second largest crude steel producer India, in contrast, boosted production by 6.8% to 13.6 million tonnes, reflecting strong domestic demand and continued expansion in infrastructure projects and steel-making capacity.
That said, the south Asian country is currently facing coking coal supply issues.
Crude production declines among most major steel producers
Production drops were reported among most of the other top ten steel-producing nations, worldsteel said.
Iran recorded the most severe decline among major producers in January, down 24.1% year on year to 2.2 million tonnes.
Low steel prices within the Asia region, a prime destination for Iranian billet, has led to increased competition and reduced demand. The Middle Eastern country’s steel industry has also dealt with gas and electricity shortages over the winter as well as currency issues due to a complicated exchange-rate system.
Other major producers, such as Germany, South Korea and Japan also reported significant declines in crude steel production in January compared with the same month in 2024, according to worldsteel.
South Korea’s domestic steel sector has weakened due to an oversupply of low-priced Chinese steel products, leading to the introduction of tariffs in February, sources said.
Germany’s crude steel output has remained at a recession level (below 40 million tonnes) for three years amid weak demand, high energy costs and competitive imports, according to the country’s national steel industry association WV Stahl.
The association has called for urgent economic stimulus from the west European country’s newly elected conservative government, following the weak start to the year in terms of crude steel production.
The US, meanwhile, was the only other country apart from India that had crude steel production grow from January 2024 to January 2025, by 1.2% to 6.6 million tonnes.
Regional performance: Widespread contractions
Most regions reported declines in crude steel production for January 2025.
The only region to post growth was Russia & other CIS countries + Ukraine, where production rose by 1.4% to 7.0 million tonnes.


EU expects €28 billion loss in exports due to US steel and aluminum tariffs
According to a report by Bloomberg, the first round of the US president Donald Trump’s new steel and aluminum tariffs is expected to cost the European Union member states up to €28 billion in lost exports.
Maroš Šefčovič, European Trade Commissioner, noted that the current situation is constantly evolving, so the extent of any tariffs could still change.
European market players anticipate that the number of products affected will be four times higher than in 2018, as the list of the products subject to the tariffs also includes derivative steel items.
On February 10, Trump announced 25 percent tariffs on steel and aluminum imports from trading partners with duty-free exemptions or tariff-rate quota deals, such as the EU, as SteelOrbis previously reported.
In 2024, the EU’s steel exports to the US amounted 3.89 million mt, with the value of the exports at $6.99 billion, according to census data from the US Department of Commerce.


Eusider Trading joined as Member of EUROMETAL
EUROMETAL is delighted to welcome Eusider Trading as a new member company.
Eusider Trading SA, established in Switzerland in 2019, specializes in the global trading of flat and long steel products, as well as raw materials, with a particular focus on Metallics. The company procures high-quality materials worldwide, supplying key markets across Europe, MENA, and Latin America.
A strong emphasis is placed on coils, especially coated materials sourced from top-tier suppliers, which are regularly distributed to major steel service centers and stockists worldwide.
Thanks to the leadership of their CEO, Marco Micciché, and the active role of experienced steel professionals coming from previous engagements in primary international steel trade companies, Eusider Trading has expanded its reach and solidified its presence in global markets over the past five years.
Discover more: eusidertrading.com

European aluminium, steel, iron importers speculate on effect of leaked CBAM changes
Reports of impending changes to CBAM have circulated since EU tax commissioner Wopke Hoekstra gave an interview to UK newspaper Financial Times on February 6.
But speculation increased among European importers of the goods affected by CBAM – including aluminium, iron and steel – following the February 24 leak of a document outlining proposed revisions.
The European Commission declined to comment on the document, which has been widely shared on social media and by other industry news outlets.
“We do not offer comment on leaked documents,” a European Commission spokesperson told Fastmarkets via email on February 25. “On CBAM more generally, the first Omnibus package on sustainability is indeed scheduled for discussion and possible adoption tomorrow, February 26, 2025.”
New exemption threshold for small importers
Under the current CBAM legislation, which was scheduled to come into effect from January 1, 2026, any entity importing more than €150-worth ($157) of aluminium, cement, fertilizers or iron and steel must report the CO2 emissions embedded in the incoming material.
But under the changes proposed in the leaked document, only companies importing more than 50 tonnes (or 100 tonnes of embedded CO2) of net mass of goods, covered by the legislation, will have to comply.
“A threshold set at a level of 50 tonnes will exempt the vast majority of importers from obligations under this Regulation while maintaining more than 99% of embedded emissions in the scope of the CBAM,” the leaked document was reported to say.
“This is what the European Commission should have done from the start,” Fastmarkets chief economist Stuart Evans said. “By excluding small emitters, the proposed changes bring CBAM into line with the approach taken for the [EU’s previous] Emissions Trading Scheme.”
One of the chief aims of CBAM was to reduce carbon leakage by ensuring that imported materials with embedded CO2 were subject to the same carbon taxes paid by European producers of similar material.
“It’s an easy win for the European Commission,” Evans said. “It is improved policymaking because it fundamentally doesn’t change the result. CBAM will still cover 99% of emissions but the cost of compliance will be far lower.”
The other change in the proposal was said to be a delay and simplification of CBAM certificate purchases. The leaked document proposed moving the start date of the CBAM certificate sale to February 2027, from the current official start date of January 1, 2026.
According to Dan Maleski, CBAM adviser at Redshaw Advisors, importers would have more time to comply with the requirements, but the costs associated with the emissions embedded in 2026 imports will still apply. “They will simply be incurred in 2027,” he said.
Speculation
The European Commission may have refused to comment on the leaked document, but it has already sparked speculation in the European metals trading community.
“I’m not surprised by this document,” an aluminium trader said. “CBAM in its official current form is ridiculous and clearly needs to be changed. But these proposals don’t address the real issue, which is that CBAM just looks at scope 1 emissions, which are a tiny part of the overall carbon footprint of a tonne of aluminium.”
“These proposals don’t get me too excited,” a second Europe-based aluminium trader said. “They need to include scope 2 emissions to make it an effective policy.”
The trader also pointed out that the new exemption threshold would make little difference for metal traders. “Our shipments are well above the threshold,” he said, “so this new proposal wouldn’t change the CBAM obligation for traders.”
But the trader did feel that the leaked document was significant. “It shows that CBAM won’t stand in its current form. It has started a debate,” he said.
“CBAM will happen,” Evans said. “But I wouldn’t be surprised if we see more changes down the line. The current trade policy of the US administration allows the EU to take a more muscular approach.”
Mixed reactions from the European steel sector
Fastmarkets’ sources in the steel sector shared mixed views on the latest proposals for amendments of CBAM coming from the leaked document.
“I do not think that the European Commission wants to step back from its green ambitions,” a distributor source engaged with imports of flat steel products told Fastmarkets. “There is still a lot to discuss and adjust in the current version of CBAM, and I think this is the aim of a potential proposal for amendment of the current regulation.”
A trader source, who actively imports flat steel products, also expressed satisfaction with the proposals.
But European steelmakers were more reserved. “[The amendments] will, for sure, weaken the system for a year,” a producer source told Fastmarkets.
A second producer source did not expect a significant effect on the domestic market, but the proposed legislative amendments were considered positive for the import industry because they would have one year more for preparation.
The source expressed a concern about the proposed exemption threshold, saying that “50 tonnes are nothing.”
The steel industry was currently responsible for around 5% of CO2 emissions in the EU and 7% globally, according to European Commission data.

European Commission schedules Steel Dialogue, reinforces strategic role
European Commission President Ursula von der Leyen will host a Strategic Dialogue on Steel on 4 March, Kallanish notes.
In a statement issued on Tuesday, the Commission reinforced that steel is a strategic sector, saying it plays a central role in the EU’s broader strategic autonomy.
The meeting is anticipated to bring together steel manufacturers, raw material suppliers, off-takers, and representatives of social partners and civil society. EUROMETAL will be represented by its president, Alexander Julius, the association says.
This comes ahead of the dedicated Steel and Metals Action, which Executive Vice-President Séjourné has been tasked with delivering in the spring. Feedback from the Steel Dialogue and related wider consultation will be fed into this dedicated plan.
“The steel industry is a key sector of our European single market. At the same time this industry is of utmost importance in our fight against climate change,” von der Leyen notes. “The Strategic Dialogue will help develop a concrete Action Plan to tackle the unique challenges of this sector in the clean industrial transition. We want to ensure that the European steel industry is both competitive and sustainable in the long-term.”
“Europe has a plan for its industry: we must produce more, we must produce clean, and we must produce European,” says Séjourné. “This starts with our most strategic sectors: steel is one of them. We must protect our steel sector from unfair foreign competition and boost our own production of clean European steel.”
Key Strategic Dialogue discussion points will include how to enhance competitiveness and circularity, drive the clean transition, decarbonisation, and electrification, ensure fair trade relations and an international level playing field. The Commission will inform and consult with the Council and European Parliament throughout the Dialogue process.
Proposals include the joint purchasing of raw materials on behalf of interested companies, which could ensure diversification of supplies, and a Circular Economy Act to incentivise the use of secondary scrap material in manufacturing. Also discussed will be the use of guarantees and risk reduction instruments to facilitate conclusion of long-term power purchase agreements, and to accelerate the uptake of hydrogen.
To speed up investment, the meeting will also discuss the creation of a dedicated financing mechanism for industrial decarbonisation based on the auctions-as-a-service model.
On the foreign trade front, global overcapacity is expected to reach 630 million tonnes in 2026. This means “it is essential to make more efficient use of anti-dumping or anti-subsidy duties to prevent that our market becomes an export destination for state-induced excess steel production,” the Commission says.
In addition, the safeguard measures for steel currently in place are set to expire by June 2026. The Commission will define a long-term solution to replace those measures in light of global non-market overcapacity, it concludes.
Adam Smith Poland
