


European HRC prices remain largely flat despite bullish sentiment at producers
Fastmarkets calculated its daily steel HRC index, domestic, exw Northern Europe at €540.83 ($596.68) per tonne on Friday, down by €1.67 per tonne from €542.50 per tonne the previous day.
The index was down by €4.38 per tonne week on week and by €49.17 per tonne month on month.
Trading remained quiet in the region. Buyers questioned the recent price increase announced by a leading European producer earlier in the week.
“The market cannot accept [€590 per tonne as a base price for HRC]. Demand is not strong enough to support that rise,” one buyer source told Fastmarkets. “But it was clear that prices [for HRC] have fallen below costs for European mills.”
Buyers estimated tradeable values at €520-540 per tonne ex-works on Friday.
One buyer estimated achievable prices in the range of €510-520 per tonne ex-works, but market sources said that mills were unlikely to accept such low prices.
One integrated steelmaker in the Benelux area was offering HRC at €540 per tonne ex-works, but trade sources said that the mill was also considering a price rise, following the move by a market leader.
Market sentiment would become clearer in the week starting October 7, industry sources said, when public holidays in Germany and in Asian countries were at an end.
“I think, price-wise, we are currently at rock bottom in Europe,” a second buyer said.
“It is clear that [EU mills] will still accept lower prices for fourth-quarter-delivery HRC,” a third buyer said. “The price increase from [the leading European producer] helps to stabilize the market, but [I am] not so sure about actual price rises when demand is so low.”
In Southern Europe, Fastmarkets’ daily steel HRC index, domestic, exw Italy was €535.00 per tonne on Friday, unchanged from the previous day.
The Italian index was down by €6.67 per tonne week on week and by €55.00 per tonne month on month.
Buyer estimates for the workable market price were €520-540 per tonne ex-works, while the majority of sources estimated the market at €530-540 per tonne ex-works on Friday.
One integrated Italian supplier withdrew its offers from the market earlier this week and was expected to come back with new prices.
“After [the European producer’s] price rise this week, other producers also withdrew offers and [were now planning] price rises. We will see how the market reacts,” a buyer in Italy said.
As for imports, the markets have remained quiet due to public holidays in Asia. But market sources suggested that imports would remain uncompetitive in Europe because of trade restrictions, long lead times and the small gap to European prices.
“We do not have new offers from Asia, but China has become more bullish after a stimulus package was announced so we expect higher offers,” a second buyer said.

Polish steel rebar, wire rod prices decrease further on poor demand
Wire rod
Polish mills announced lower offers for October-delivery low-carbon drawing quality wire rod, at 2,700-2,750 zloty ($692-705) per tonne CPT, sources told Fastmarkets.
In comparison, at the beginning of September, similar material was on offer at 2,800-2,850 zloty per tonne CPT.
But persistently low demand has made producers revise their offers downward, Fastmarkets understands.
Fastmarkets’ sources estimated the tradeable market level at 2,650-2,700 zloty per tonne CPT.
As a result, Fastmarkets’ price assessment for steel wire rod (drawing quality), domestic, delivered Poland, was 2,650-2,750 zloty per tonne on Friday, decreasing by 50 zloty per tonne from 2,700-2,800 zloty per tonne on September 27.
“Demand is still very weak, and there is no restocking,” a distributor source told Fastmarkets. The source added that the situation remained unpredictable due to the conflicts in Ukraine and the Middle East.
Import offers of low-carbon drawing quality wire rod from Italy to Poland were heard at €630-650 ($695-717) per tonne CPT, depending on the destination.
From Ukraine, offers of mesh-quality material were heard at €600-610 per tonne CPT.
Moldava-origin mesh-quality wire rod was on offer at €620 per tonne CPT.
Rebar
Prices for Polish rebar also decreased during the assessment week, and were heard at 2,530 zloty per tonne CPT.
In comparison, at the beginning of the previous month, Polish rebar was on offer at 2,610-2,660 zloty per tonne CPT.
Market participants estimated the tradeable market level for the assessment week to be 2,500 zloty per tonne CPT.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, cpt Poland, was 2,500-2,530 zloty per tonne on Friday, down by 70-75 zloty per tonne from 2,570-2,605 zloty per tonne on September 27.
In the secondary market, prices for rebar from stock were heard at 2,620-2,650 zloty per tonne CPT, depending on the region.
Demand for rebar in Poland also remained weak, according to Fastmarkets’ sources.
The completion of some significant construction projects will be postponed until next year, Fastmarkets understands.
“Some infrastructure projects, which are supposed to be funded by the EU, will start no sooner than the first half of 2025,” a second distributor source told Fastmarkets.
Besides, it was not clear yet whether the government’s program to grant low-interest-rate loans to first-time home buyers would continue. The program was expected to support the residential construction sub-sector.
“The government does not even know what form the program would take. I doubt it will come into force in the first half of next year,” the second distributor said.
Polish domestic rebar prices were still under pressure from imports, Fastmarkets understands. Import offers of rebar from European suppliers to Poland were heard at €600-620 per tonne CPT.
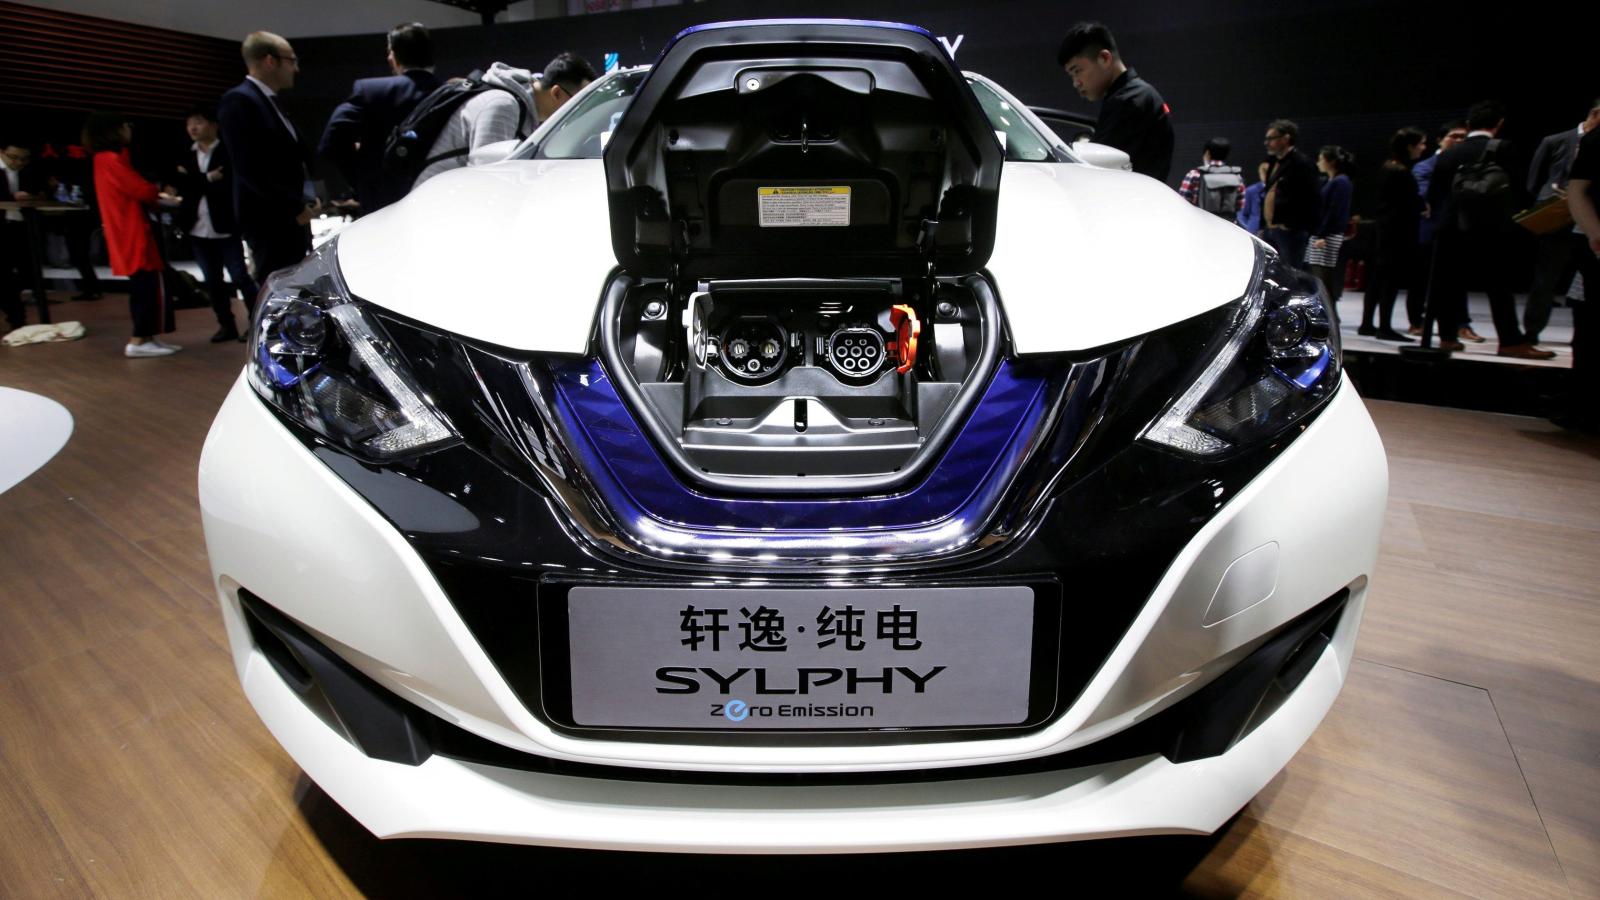
European Union votes to impose tariffs on China-made electric vehicles
The European Union member states on Friday voted to impose extra tariffs on electric vehicles made in China, in a move that is likely to draw a reaction from Beijing.
“Today, the European Commission’s proposal to impose definitive countervailing duties on imports of battery electric vehicles (BEVs) from China has obtained the necessary support from EU Member States for the adoption of tariffs,” the EC says in a statement.
However, the commission adds it would continue negotiations with China, Kallanish notes.
“In parallel, the EU and China continue to work hard to explore an alternative solution that would have to be fully WTO-compatible, adequate in addressing the injurious subsidisation established by the commission’s investigation, monitorable and enforceable,” the statement continues.
The vote came after the EC launched an anti-subsidy investigation on China-made battery electric cars last year, saying the cheaper BEVs were “distorting” the EU market with their “artificially low prices.” As such, provisional duties were put in place from July this year. The countervailing tariffs will be up to 35.3%, on top of the existing 10% car import duty.
While it’s unclear how the member states voted, France, Greece, Italy and Poland were reportedly set to vote in favour.
The tariffs were passed a day after German labour union IG Metall and the works councils of major automakers called on Germany to vote against the tariff, calling the move “the wrong approach.”
“EU tariffs on EVs from China have had a mixed impact so far, according to T&E analysis of the EV-Volumes database,” says campaign group Transport & Environment.
“MG had its largest ever drop in BEV market share in Europe, falling from 4.1% share in August 2023 to 2.4% in August 2024, the research shows. BYD continued to expand its EU share though at a slower pace than before, growing from 1.6% in August 2023 to 2.9% BEV market share in the same month this year. Geely increased its market share from 1.3% in August last year to 2% in August 2024,” T&E adds.
Reethu Ravi | UK


Low demand drags on long steel prices across Northern Europe but New Year could bring renewed activity, sources say
Sources in Germany reported persistent weak demand and little hope of a recovery in the near-term. But market participants in the Netherlands and Belgium reported orders for small tonnages and renewed hope of a pick-up in construction activity in the New Year, Fastmarkets heard.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, delivered Northern Europe, was €600-620 ($663-686) per tonne on Wednesday, down week on week by €25-30 per tonne from €630-645 per tonne.
Depressed demand and high feedstock costs continued to weigh on trading activity, with the German steel sector particularly affected by minimal appetite among key end-user sectors.
“Demand is still very poor. Some orders [have been received but] not large volumes. Germany is in a very bad situation, in terms of demand,” a buyer source said.
Steel scrap prices have increased week on week, which has put further pressure on producers’ margins, market sources said.
The upturn in scrap prices was largely supported by a strengthening Chinese market, according to market sources. Sentiment in the steel market improved following the Chinese government’s recent stimulus efforts, prompting an increase in iron ore and steel prices.
Fastmarkets’ daily index for iron ore 62% Fe fines, cfr Qingdao, was $108.18 per tonne on Wednesday, compared with $96.07 per tonne on September 25. It rose further on Thursday, to $108.75 per tonne.
Fastmarkets’ calculation of its daily index for steel scrap, HMS 1&2 (80:20 mix), North Europe origin, cfr Turkey, was $373.32 per tonne on Wednesday, up by $13.32 per tonne week on week.
The removal of the National Rural Area Programme (NLPG) in the Netherlands will help to stimulate the construction sector, and support the restarting of delayed projects, market sources said.
The NPLG was initiated by the country’s previous government as part of its stringent environmental regulatory program. It was designed to encourage the country’s provinces to meet environmental targets, including the cutting of nitrogen emissions.
This resulted in many construction projects, viewed as key emitters of nitrogen, being cancelled or postponed, market sources said.
The previous government made it more difficult to get construction permits, in turn limiting developers and reducing investment in the sector.
But the new, recently formed coalition government’s removal of the NPLG will help to remove these barriers and support construction activity, market sources said.
The NPLG will be replaced with a different program, the new government said, but it has made it clear that economic concerns will be given priority over stringent environmental regulations, market sources said.
“The new coalition government has put in place new regulations around nitrogen taxes and construction licenses which will help to support new construction activity,” a trader source from the region said. “In the Netherlands, we really need housing, and the government has said that it will build houses and will help to support the construction sector. We will start to see the results of these decisions after the [year-end] holidays.”
Fastmarkets’ weekly price assessment for steel wire rod (mesh quality), domestic, delivered Northern Europe, was €600-620 per tonne, down week on week by €5-10 per tonne from €605-630 per tonne.
Published by: India-Inés Levy


Weak demand inhibits trading in Southern European long steel market
Fastmarkets price assessment for steel reinforcing bar (rebar) domestic, exw Italy was €580-600 ($641-664) per tonne down by €10 per tonne from €590-610 per tonne on September 25.
Prices edged further down due to the weak demand, cheap imports and the depressed outlook, sources said.
“The rebar price is falling a little, but mills intend to put the price up [and] this is colliding with weak demand and an uncertain outlook in the building sector,” a buyer source said.
“Customers don’t believe in a price increase and sentiment is negative, so they’re in wait and see mode,” the source added.
A second buyer source told Fastmarkets: “This week, the producers tried to move prices up, but buyers are still waiting.”
Scrap prices, meanwhile, edged higher, mainly because of the stronger Chinese market, market participants said.
Fastmarkets’ calculation of its daily index for steel scrap HMS 1&2 (80:20 mix) North Europe origin, cfr Turkey, was $373.32 per tonne on Wednesday, up by $8.13 per tonne week on week.
Sentiment in the steel market improved following the Chinese government’s recent stimulus measures, prompting an increase in iron ore and steel prices.
And Fastmarkets’ daily iron ore index for 62% Fe fines, cfr Qingdao was $108.18 per tonne on Wednesday, up from $96.07 per tonne on September 25.
In the long steel market, Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, delivered, Spain was €585-600 per tonne down by €25-35 per tonne from €620-625 per tonne.
Sources reported ongoing weak demand and a near-zero appetite for exported stock.
Southern Europe wire rod
In Southern Europe, meanwhile, Fastmarkets’ price assessment for steel wire rod (mesh quality), domestic, delivered Southern Europe, was €600-620 per tonne on Wednesday down by €10-20 per tonne from €620-630 per tonne on September 25.
Weak demand and high feedstock costs continued to weigh on European mills, sources said, which therefore lowered their offer prices.
“There is low demand because of the coming winter holiday [season, when] customers don’t want to buy big quantities,” a producer source told Fastmarkets.
Published by: India-Inés Levy
Tata Steel Nederland advances downstream climate neutrality
Tata Steel Nederland says it has achieved CO2 neutrality in the production of steel roof and facade panels at its SAB-profiel unit in Geldermalsen, making this its sixth climate neutral location.
The site is part of the steelmaker’s Tata Steel Downstream Europe business unit, within which the Naantali (Finland), Halmstad (Sweden), Gelsenkirchen (Germany), and Maastricht (Feijen and MultiSteel) locations have also achieved CO2 neutrality on scope 1 & 2. Downstream Europe processes steel from the Ijmuiden works.
“In addition to mega projects, such as the transformation to green steel production in IJmuiden, we are also working in other areas to make our company more sustainable. Our commitment to sustainability in our downstream businesses has great potential. Almost a third of our downstream locations are now climate neutral, and we continue to work hard to be fully CO2-neutral,” Tata Steel Nederland board member responsible for downstream activities Gunilla Saltin says in a note seen by Kallanish.
Tata Steel Nederland said last month it is “tightening the belt” by means of cost-cutting measures to cope with current deteriorating market conditions (see Kallanish passim).
Adam Smith Poland

Hydnum Steel, Siemens digitalise Puertollano green steel mill
Spain’s Hydnum Steel (HS) says it is advancing with its plan to build the first green steel mill on the Iberian Peninsula, Kallanish notes. The project, a partnership between the Helvella investment company, Siemens, ABEI Energy and Russula Corporation, will be located in Puertollano, in the Castilla-La Mancha region.
HS and Siemens have opted for an innovative digital concept for the plant. After passing the technological definition phase, the basis of the project has been established in integrating the use of the Digital Twin in all the production stages, from the design to the complete start-up of the facility.
The aim is to reduce the carbon footprint, and improve energy efficiency and competitiveness, while strictly complying with environmental and sustainability regulations, HS observes.
“It’s not just about producing steel but doing it in a way that is fully aligned with global sustainability goals,” says HS chief executive Eva Maneiro. “By integrating advanced Siemens technologies, we ensure that every stage of our production process is efficient and, at the same time, actively contributes to the fight against climate change. Our commitment is to demonstrate that decarbonisation and competitiveness cannot only coexist but represent the future of the industry,” the ceo adds.
Siemens technology provides different simulation tools. During the engineering phase, NX software will be used to create a complete digital model of the plant, enabling manufacturing process optimisation.
The project also includes the integration of both information technology (IT) and operational technology (OT), to immediately capture all valuable data generated by the plant to monitor, analyse and make footprint-reducing decisions, Hydnum observes.
Todor Kirkov Bulgaria

Italian re-rollers to increase coil derivative prices
Coil derivative prices are poised for a price increase, Italian re-rollers and service centres tell Kallanish.
Tube and sheet prices in Italy, along with other EU nations like France and Germany, have declined to “unsustainable” levels, say sources, jeopardising the financial stability of re-rollers and service centres. The upcoming derivatives price increases align with this week’s announcement from ArcelorMittal of a €40/tonne ($44.1) hike in European coil prices (see Kallanish 3 October).
According to multiple sources, similar price announcements for tube and sheet are expected in the coming days, after values have fallen below cost. “I believe we are at a pivotal moment. The coil increase is essential for restoring tube and sheets prices to a profitable level. October will see a gradual restoration of prices to sustainability. Values of coils have hit a significant low, while inventory levels of flat and re-rolled products are currently at a relative low point,” a tube producer says. He indicates apparent demand should recover this month.
According to a different source, end-users have been affected by the high financial costs of their stocks in 2024 and, as a result, they have concentrated on maintaining low inventories. Lower interest rates should boost end-user activity and reduce the pressure to maintain low inventory levels, while potentially higher steel prices could boost pricing lower down the value chain. Re-rollers indicate additional production rate reduction in the fourth quarter.
In September, demand for coil derivatives experienced a notable decline, with tube discounts peaking at 45-47 points. Buyers, including end-users and distributors, were careful in their purchasing decisions, fearing prices may continue to decline.
The announcement of ArcelorMittal’s coil price increase has been positively received downstream, as it presents an opportunity to strengthen prices downstream. Nonetheless, a number of coil buyers argue that any price increases will need corresponding production cuts to sustain them.
Currently, coil producers in Europe are not reducing output due to the potential loss of CO2 certificates. Beginning in the first quarter of 2025, EU producers will likely reduce their output, sources say. As of Monday this week, before the hike announcement, hot rolled coil prices in Europe averaged at €530-550/t, base ex-works, Kallanish notes.
Natalia Capra France

The new quota period in the EU has started
The new quota period in the EU has started as of October 1.
Although the volumes awaiting at the ports are not cleared through customs yet, given the high volumes of imports waiting at the ports, for some products, the quota volumes have already been exhausted. In the table below, you can see the products for which quotas have already been exhausted and also those for which more than 50 percent of quotas have been used up.



European steel HRC producers test market with higher offers
Several trading sources told Fastmarkets that a leading European steelmaker has increased its offer price for November-delivery HRC to €590 ($655) per tonne, ex-works or delivered, depending on the region. This was up by €40 per tonne from previous offers.
But these new prices had yet to be sealed in deals, market sources said, with buyers still digesting them.
Other European suppliers have been considering similar price rises of €30-40 per tonne, the sources added.
“The lowest [HRC] prices are no longer available. But higher offers have not traded yet,” a buyer said.
Buyers’ estimates of tradeable values were heard at €530-550 per tonne ex-works on October 2. But market sources suggested that the lower end of that range may no longer be available from some suppliers.
“The market is at a turning point. The increase [in HRC prices] is necessary for producers, because of costs. Plus, China has become optimistic after [publication of its recent] stimulus package and has started to increase offers, bolstering global markets,” a second buyer said. “However, consumption remains low – that is a stumbling block.”
Trading remained quiet on Wednesday, with market sources expecting more clarity next week.
“Thursday and Friday [October 3-4] are public holidays in Germany, so the market will be quiet. The ‘Golden Week’ in China [for its National Day holiday] is still on. So when everyone comes back to the market [in the week starting October 7] we will have a better understanding about prices,” a mill source said.
Fastmarkets calculated its daily steel hot-rolled coil index, domestic, exw Northern Europe, at €544.38 per tonne on Wednesday, up by €7.39 per tonne from €536.99 on October 1.
The index was, however, down by €5.50 per tonne week on week and by €45.62 per tonne month on month.
In Southern Europe, Fastmarkets’ corresponding daily steel hot-rolled coil index, domestic, exw Italy, was €535.00 per tonne on Wednesday, up by €2.00 per tonne from €533.00 per tonne the previous day.
The Italian index was down by €9.38 per tonne week on week and by €55.00 per tonne month on month.
Offers from a domestic supplier were heard at €550 per tonne delivered. This would be equivalent to €535-540 per tonne ex-works, according to trade sources.
Buyer sources estimated tradeable values at €520-530 per tonne ex-works.
At the same time, market sources said that they were expecting local mills to try to increase their offer prices soon. No official announcement has been made yet, however.
As for imports, the markets have remained quiet due to public holidays in Asia. But market sources suggested that imports would remain uncompetitive in Europe because of trade restrictions, long lead times and relatively high prices.
For example, the latest European Commission customs data showed that HRC tonnages from Vietnam awaiting allocation came to 242,292 tonnes on October 1, but the quarterly allowance for the country for October-December was only 141,850 tonnes.
A similar situation was seen for Japan. On the same date, the tonnage awaiting allocation was 251,333, exceeding its similar 141,850 tonnes quarterly allowance for October-December.
For Egypt, tonnages awaiting allocation totaled 144,517 tonnes on October 1, and for Taiwan the figure was 155,950 tonnes. The quarterly allowance for each country was also 141,850 tonnes.
This meant that imports from these origins would be subject to safeguarding duty. In addition, material from these four origins, which account for nearly half of the EU’s total HRC imports, were also subject to an anti-dumping investigation.
“One thing is clear – importing HRC is not workable in Europe at the moment,” a buyer in Italy said.
New offers from Asian suppliers were expected in the next week.