


German bender puts minimum price tag on rebar
As Germany’s construction industry is struggling to come back to life from suspended animation for over a year, rebar distributors are cannibalising each others’ orders. One of them has now come out with the clear announcement of a minimum price that benders would need to charge for processed rebar to cover their costs.
In a letter received by its customers in June, a southern German distribution group says it need a sales price of €700/tonne ($762) to break even. Its wording – “the price level needs to rise to €700/t” – suggests it recently accepted lower prices. It notes the necessary basis for this figure is stability of its purchase prices.
Mill prices have hardly moved since spring. The price paid by the distributor at its doorstep is around €640/t delivered, on a base price of €370/t. According to the buyer for another bender in central Germany, these have not varied by more than “give or take, €5-10” in a couple of months. He dismisses reports of weekly price drops or surges. “There are no moves on the intake end. Sometimes mills will go down by a few euros to motivate a bigger order; next thing they will go back up by a few,” he tells Kallanish.
On the proposed price tag, he says that “I can subscribe absolutely to the mark of €700; anything lower would be a loss, but you hear of it everyday.” Somewhat critically of the author of the letter, he also notes that “if they’d stick to their announcement, we’d all be better off”.
Christian Koehl Germany


European stainless flats market slows
Transaction prices for European stainless flat steel have remained unchanged on-month. However, deal values may decline as mills recently reduced their offer prices for October delivery by approximately €50/tonne ($54), Kallanish notes.
After a period of robust sales and rising prices for coil, tube, and sheet, the market is now experiencing a slowdown. This can be attributed to the return of Acerinox, whose production was impacted by strikes for months. At present, there are reports of weak demand downstream.
However, after a period of tight supply in the first half of the year, the situation is now improving, as the EU’s four stainless flat steelmakers have resumed production after stoppages of varying degrees. European mills have successfully secured orders until September and are facing delays as a result of previous supply shortages in the region.
The average price for domestic stainless steel cold rolled coil is at €2,800/t delivered for September lead time but, for October, tags are down to €2,750/t delivered. Hot rolled coil is at about €150-200/t below this level on average. In Italy, due to aggressive imports, CRC is slightly lower than in the rest of Europe, at €2,750/t delivered on average, while HRC has been pushed down to €2,450/t delivered, also due to large imports.
Prices of Italian stainless cold rolled sheet are currently at elevated levels. Values for September delivery are at €2,900/t ex-works. Demand for tube remains low as supply is outpacing consumption.
According to sources, distributor prices are stagnating due to a slowdown in the downstream sector. According to a market note from Italian steel trade association Assofermet, distributors have experienced months of “struggle” to recover sales prices. The current distribution values do not seem to be sufficient to cover operating costs, especially when compared to the high quotations proposed by producers. Orders from various end-use sectors are slowing, Assofermet concluded.
Natalia Capra France

Vanilla Steel receives 7-figure funding from the EU for AI project
Vanilla Steel, a startup in the European steel market, is proud to announce the successful acquisition of a 7-figure subsidy from the Pro FIT program of the Investitionsbank Berlin. This milestone, supported by co-financing from the European Union, is aimed at the development of the innovative Smart Forecaster project.
The Smart Forecaster project leverages cutting-edge artificial intelligence to accurately predict future prices and demand for both prime and excess steel. This innovative tool is set to revolutionize decision-making processes within the steel industry by offering precise demand forecasts and pricing trends for a wide array of steel types.
“Even in the traditional steel industry, innovation is possible. At Vanilla Steel, we are committed to pushing the boundaries of technology to bring advanced solutions to the market” said Simon Zühlke, Managing Director at Vanilla Steel. “We are immensely grateful for the financial support from the EU, which enables us to embark on this transformative journey”.
Vanilla Steel aggregates spot steel supply from over 500 suppliers and spot steel demand from more than 3,000 buyers across Europe, facilitating efficient and transparent trading.
The Smart Forecaster project represents a significant leap forward in its mission to streamline and modernize the steel trading process.

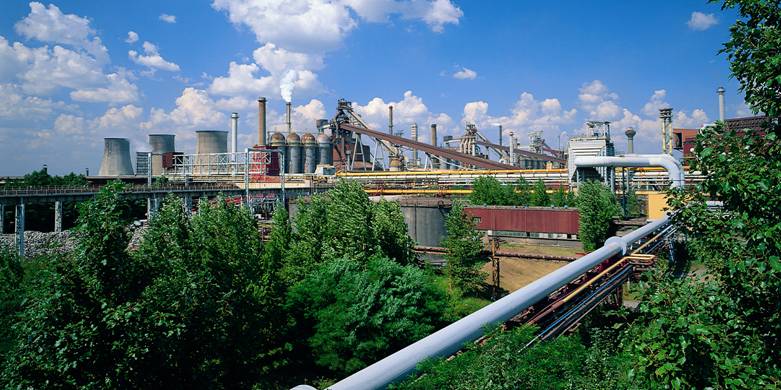
ArcelorMittal Poland closes coke production for good
ArcelorMittal Poland (AMP) has decided to close the remaining coke battery at its Krakow plant after the hoped-for rebound in steel demand did not materialise.
The firm idled the coke battery last November due mainly to weak demand, but also the narrowed differential between coke and coking coal prices (see Kallanish passim).
The hot idling allowed for the battery to be restarted once market conditions improve, but “unfortunately, that didn’t happen”, says AMP chief executive Wojciech Koszuta. “Keeping a battery hot idled is very costly, mainly due to the cost of the natural gas that we use to fuel the facility. The continued hot idling of the battery in the hope the situation will improve is economically unviable.”
Moreover, decarbonisation plans in various sectors in the coming years will result in the gradual decline of coke demand, the firm adds.
The firm found work at other AMP units for 230 of the affected coke plant employees during the hot idling. The remaining 70 workers that have maintained the coke plant since then will receive offers to transfer to other units.
AMP’s crude steel production sunk to just 3.1 million tonnes in 2023, down 9% on-year. This represents a drop exceeding 2mt over the last five years. Production has been gradually declining following the closure of AMP’s Krakow blast furnace in 2020, weakening European steel demand, imports’ increased share in consumption, and uncompetitive production costs in Europe.
The Krakow plant sources slab from AMP’s flagship Dabrowa Gornicza works to feed its hot and cold rolled coil mills, as well as galvanizing and coil painting lines. It also plans to commission a line for zinc, aluminium and magnesium (ZAM) coil coating in 2025.
Adam Smith Poland

Italian rebar prices remain unchanged, activity slow
Italian rebar prices showed little change last week after experiencing a decrease earlier in July. The low end of the transaction price range has nevertheless once again decreased, by €10/tonne ($10.8), due to low consumption downstream, Kallanish notes.
Activity is decreasing as the August break approaches. Sources indicate July sales volumes have been disappointing.
Transaction values in the domestic market fall within the range of €320-340/t base ex-works, or €580-600/t ex-works effective. This includes an average of €260/t for additional size extras.
Domestic mesh is also hovering at around €420-440/t base ex-works. When considering their purchases, buyers should take into account costs for transport and an extra €300/t for size extras.
Meanwhile, scrap prices in Italy have seen an average decrease of €25/t in July. According to sources, the railway and warehouse construction sector is currently driving rebar demand.
Natalia Capra France

Post-summer price direction unclear for European HRC market: sources
Fastmarkets calculated its daily steel hot-rolled coil index domestic, exw Northern Europe at €628.58 ($686.37) per tonne on Friday, up by €0.45 per tonne from €628.13 per tonne on Thursday July 18.
The index was down by €3.55 per tonne week on week and by €2.30 per tonne month on month.
Integrated mills in the region were reportedly selling HRC with lead times of four to five weeks at €620-640 per tonne ex-works, while offers were in the range of €625-650 per tonne ex-works for such material.
A German integrated mill was selling HRC with lead times of four weeks at €625 per tonne ex-works, sources said.
For HRC with lead times in October, a supplier in the Benelux area voiced offers at €660 per tonne ex-works, compared with €640-650 per tonne ex-works for August to September delivery coil.
Another major European mill was looking to achieve €670 per tonne ex-works for HRC with September-October lead times.
Higher offers have not yet turned into deals, sources said.
“That is [a typical] tactic of the European mills — to push offers up, expecting trading to pick up after summer break. However, it doesn’t seem likely that the market will be ready for higher prices, since consumption doesn’t show any signs of a rebound,” a German buyer said.
In Southern Europe, Fastmarkets calculated its daily steel hot-rolled coil index domestic, exw Italy at €620.42 per tonne on Friday, stable day on day.
The index was down by €5.58 per tonne week on week and by €7.71 per tonne month on month.
The Italian market was also seasonally quiet, and prices were largely unmoved, but sources said that local integrated mills were also aiming for post-summer price rises.
“All activities are muted — it’s a holiday season in Europe,” an Italian buyer said. “There is talk of a €20 per tonne price rise [for HRC] from [a local supplier] for September, but it’s too early to say what market would look like after the holidays.”
In the week to Friday, HRC with lead times of four to five weeks was still being offered by a local supplier at €640-650 per tonne delivered, which corresponds to €630-640 per tonne ex-works.
Buyer sources estimated achievable prices at no higher than €610-620 per tonne ex-works, with sporadic trades reported at €620 per tonne ex-works in the week to Friday.
Offers of HRC from Turkey were available at €600-610 per tonne CFR, including the anti-dumping duty.
Published by: Julia Bolotova


European HRC prices hold largely stable amid continued demand slump
The domestic prices for European hot-rolled coil were largely stable July 19, as demand for the summer ahead remained weak and supply levels high. Opinion on price recovery continued to be mixed.
“Ever since March, things got very bad,” a service center source said. “There is no optimism [in the market].”
“I don’t think prices will go down anymore,” another service center source said. “If mills fail to raise prices, then the year will be lost.”
Sources said that most of the service centers and stockholders currently operating in the market are well-stocked, and therefore do not need to buy any material in the near term.
Market sources also noted that, due to the new safeguard measures and the potential prolonged holiday period for mills, lead times for delivery might increase, adding to overall concerns around the European flat steel industry.
“I am worried about the industrial situation in Europe,” a service center source said. “We are not competitive any longer.”
Platts assessed Northwest European HRC at Eur625/mt ex-works Ruhr July 19, up Eur5 on the day. Tradable values were reported at Eur620-630/mt EXW Ruhr.
Meanwhile, Platts assessed domestic HRC prices in Southern Europe stable on the day at Eur625/mt EXW Italy July 19. Tradable values were reported at Eur620-630/mt EXW Italy, and offers were reported at Eur630-640/mt EXW Italy.
Geraint Moody | Devbrat Saha


EU car sales rise in June, but construction activity dips
EU June auto registrations up 4.3% on year
New passenger car registrations in the European Union in June increased 4.3% year on year to 1.1 million units, largely driven by gains in Germany, Italy and Spain, European Automobile Manufacturers Association (ACEA) data showed.
Italy, Germany and Spain recorded respective year-on-year growth of 15.1% to 159,982 units, 6.1% to 297,329 units, and 2.2% to 103,357 units, while France was the only major market that saw a decline, of 4.8% to 181,709 units.
That meant new car registrations in the first half of 2024 were up 4.5% to 5.7 million units, the ACEA said, but remained 18% below pre-pandemic levels.
EU construction dips
In the EU, seasonally adjusted production in construction decreased by 1.0% in May from April, according to first estimates from Eurostat, the statistical office of the EU.
Among member states for which data was available, the largest monthly decreases in production in construction were recorded in Czechia (-5.1%), Romania (-4.1%) and Hungary (-3.8%).
On the other hand, the highest increases were observed in Finland (+1.9%), Bulgaria (+1.1%) and Belgium and Spain (both +0.3%).
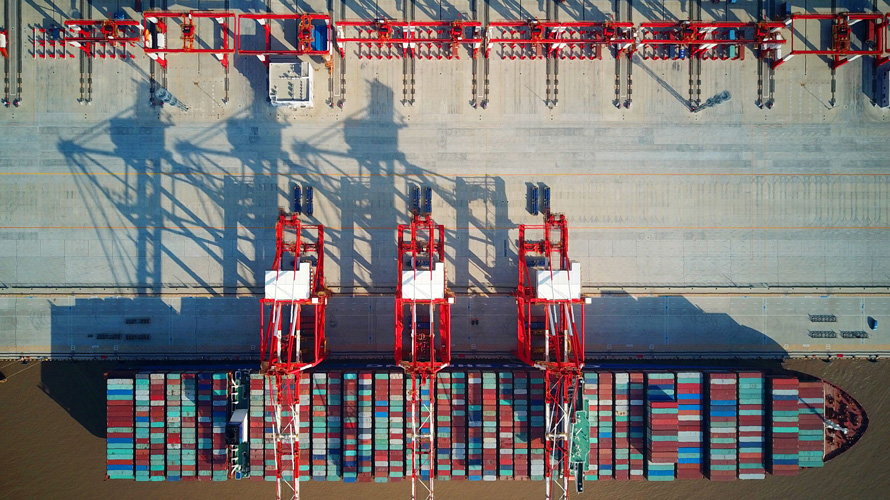
Rotterdam reports lower crude, higher box and dry bulk volumes in H1
Total cargo volume at port of Rotterdam — Europe’s largest port by throughput — were almost flat on the year during the first half of 2024, with lower crude throughput offset by higher container and dry bulk volumes, the port authority said July 18.
The port authority reported a total throughput of 220 million mt in January-June, marginally lower than 220.7 million mt in the same period of last year.
Total crude throughput at the Dutch port fell 5.8% to 48.9 million mt in the six months, with maintenance at some Rotterdam refineries in the first quarter, according to the authority.
Volumes of mineral oil products rose 4.7% to 28.6 million mt, while LNG marginally increased by 0.3% to 6 million mt, port data shows.
Container throughput increased to 67.1 million mt from 64.4 million mt, equivalent to a gain to 6.8 million twenty-foot equivalent units from 6.7 million TEU, due to increasing consumer demand and an early peak season, according to the authority.
Total dry bulk volumes rose 2.1% to 35.5 million mt, mainly driven by higher throughput volumes of iron ore and scrap, according to the authority.
Iron ore and scrap throughput increased by 12.6% to 14.6 million mt, driven by higher steel and iron production in Germany, the authority said.
Throughput of coal decreased by 19.7% to 10 million mt due to low demand for thermal coal for power generation, according to the authority. Agribulk volumes fell by 19.3% to 4.8 million mt amid low demand for soybeans as some food-processing moved to the US, the authority said.
“After a period of economic uncertainty, we see demand for raw materials and consumer products starting to increase,” Boudewijn Siemons, CEO of the port authority, said in a half-year report.
“Whether that trend will continue in other segments will depend partly on the pace of the European industry’s recovery in the coming months.”
Throughput of main goods (mil mt)
| H1 2024 | H1 2023 | Change % | |
| Liquid bulk | 101.6 | 104.8 | -3.1 |
| Crude oil | 48.9 | 51.8 | -5.8 |
| Oil products | 28.6 | 27.3 | 4.7 |
| LNG | 6.0 | 5.9 | 0.3 |
| Agribulk | 4.8 | 6.0 | -19.3 |
| Coal | 10.0 | 12.4 | -19.7 |
| Iron ore, scrap | 14.6 | 13.0 | 12.6 |
| Containers | 67.1 | 54.4 | 4.2 |
Source: Port of Rotterdam

EU HRC buyers look for alternatives to avoid safeguard duties
Buyers in the European hot-rolled coil market were looking at countries not subject to the safeguard measures for imported HRC, even as domestic prices remained under pressure July 18.
“People are looking for alternative imports from other countries, such as Indonesia, Turkey, Egypt, etc,” a Germany-based distributor source said. “They don’t want to risk buying from countries subject to the safeguards. Companies from these alternative countries are trying to enter the European market.”
Platts assessed imported HRC in South Europe stable on the day at Eur590/mt CIF Italy.
A deal for 20,000-50,000mt of imported HRC was reported at Eur580/mt CFR Italy for material originating from Australia. Offers were reported at Eur600/mt CIF Italy for material originating from Asia, and at Eur620/mt CIF Italy for material originating from Turkey.
Meanwhile, Platts assessed imported HRC in Northwest Europe stable on the day at Eur600/mt CIF Antwerp.
Sources said the market remains under pressure as customers seek lower prices or prefer to wait, as restocking activity and end-user demand remains weak.
“Demands is stable, but at low levels,” another distributor source said. “Customers are seeking lower prices and are happy to wait. Service centers are focusing on industrial segment, but there is a lot of downward pressure on prices.”
Platts assessed Northwest European HRC stable on the day at Eur620/mt ex-works Ruhr July 18.
Tradable values were reported at Eur600-640 ex-works Ruhr, but the indications at the lower end of the range were for larger volumes above Platts specifications of 100-1,000mt.
Offers were heard at Eur630-640/mt ex-works Ruhr.
Meanwhile, Platts assessed domestic HRC prices in Southern Europe stable on the day at Eur625/mt ex-works Italy July 18.
Tradable values were reported at Eur620/mt ex-works Italy and offers were reported at Eur640-650/mt ex-works Italy.