


European HRC prices continue to slide on lack of demand
Offers from integrated mills in Northern Europe for HRC with May-June lead times were heard in the range of €650-660 ($704-715) per tonne ex-works on Monday.
This was in sharp contrast with offers reported in early March at €720-730 per tonne ex-works.
But the lower prices failed to spur buying and trading remained very slow. Sources told Fastmarkets that demand from key steel-using sectors has dropped by around 15-20% year on year and this has affected purchases.
Trading was also limited by buyers’ expectations that the rock bottom for HRC prices has not yet been reached, while producers resisted further price drops citing high input costs.
“Mills claim that current [HRC] prices are already at cost-line for them and everyone sees that reducing the price doesn’t have any effect on the market – trading remains weak,” a buyer in Germany told Fastmarkets.
“Next week [at the Tube and Wire trade fair on April 15-19] in Dusseldorf, we might see some restocking, but prices are unlikely to rebound unless mills announce output cuts. And even in this case, effects on the [HRC] market will not be immediate,” a second buyer said.
Industry sources estimated tradeable market levels in the range of €640-660 per tonne ex-works, depending on tonnage.
Fastmarkets calculated its daily steel HRC index domestic, exw Northern Europe at €651.25 ($705.64) per tonne on Monday, down by €5.83 per tonne from €657.08 per tonne on Friday.
The index was down by €12.50 per tonne week on week and by €53.00 per tonne month on month.
Fastmarkets calculated the corresponding daily steel HRC index domestic, exw Italy at €635.00 per tonne on Monday, down by €0.83 per tonne from €635.83 per tonne on Friday.
The index was down by €10 per tonne week on week and by €43.75 per tonne month on month.
HRC offers in Italy were mainly heard at €650-660 per tonne delivered, which is equivalent to €640-650 per tonne ex-works.
Fastmarkets’ sources estimated tradeable market levels in the range of €630-640 per tonne ex-works, but trading remained very limited.
“It is not a question of price – it is a question of [end-user] demand. Demand remains very, very limited and most buyers can live on hand-to-mouth [HRC] bookings,” a trading source in Europe said.
Import offers of HRC from Asian producers to Italy were heard at €560-580 per tonne CFR. According to a buyer source, even lower levels by €5-10 per tonne can be negotiated for potential deals.
But customers remained reluctant to buy due to the overall downtrend with HRC prices, the buyer source added.
Another reason for the postponed signing of import contracts was the lack of clarity with the allocation of the import quotas for the second quarter of the year.
Published by: Julia Bolotova, Darina Kahramanova


Lindqvist steps down as SSAB chief
Lindqvist has six months’ notice and has agreed to stay until a successor is in place, according to the announcement. A recruitment process to find his successor will start immediately.
Lindqvist has been SSAB’s CEO for 13 years and has worked at the company for 26 years.
“During Martin’s time as CEO, SSAB has developed into a publicly traded company with global markets and a strong financial position,” SSAB board chairman Lennart Evrell said in the announcement. “He has been fundamental in building the company that SSAB is today and in driving the transformation to fossil-free production.”
SSAB Americas, a division of SSAB, was selected for award negotiations as part of the US Department of Energy’s $6 billion investment in projects to decarbonize energy-intensive industries.
The company was chosen for the potential construction of a HYBRIT manufacturing facility, which can produce fossil-free iron by using green hydrogen instead of fossil fuels.
SSAB Americas, the largest producer and supplier of steel plate in North America, operates a mill in Muscatine, Iowa, and the company’s special steels division has a facility in Mobile, Alabama.
Published by: Rijuta Dey Bera

European HRC market sentiment bearish on weak demand, oversupply
European hot-rolled coil prices remained under pressure on April 9 due to combination of poor demand and excess supply.
The mills have been trying to hold prices stable in local markets but were giving discounts when making offers to other European countries, sources said.
“We see different prices from the mills depending on the destination and a buyer, there is no unified approach,” a Benelux-based service center said.
Platts assessed domestic prices for hot-rolled coil in Northwest Europe stable on day at Eur640/mt ex-works Ruhr on April 9.
Tradable values were reported at Eur630-640/mt ex-works Ruhr with majority of data reported at Eur640/mt ex-works Ruhr.
German mills offered material to local buyers at Eur650-670/mt ex-works Ruhr, offering material with a discount to other European countries. Market participants said the discounted prices – around Eur610-620/mt ex-works Ruhr – were not available to the German market and were excluded from the assessment.
Steelmakers across Europe have been offering May delivery coil.
Platts, part of S&P Global Commodity Insights, assessed domestic prices for hot-rolled coil in South Europe stable on day at Eur620/mt ex-works Italy on April 9.
Offers have been heard at Eur640-650/mt delivered Italy, bids – at Eur620/mt delivered Italy and tradable values – at Eur620/mt ex-works Italy. Some sources, however, said that the prices of Eur620/mt ex-works would not be accepted for sales within Italy.
Demand, in the meantime, remained muted from end consumers and distributors have been avoiding bookings in the bearish market. Majority of market sources believe that steelmakers need to stop some furnaces to tackle excess supply and, therefore, to prevent price drops.
“The only way to deal with lack of demand and oversupply is stoppages of the furnaces, but the steelmakers take their time,” a German service center said.
Some market sources, however, reported that the distributors might need to restock soon as they have been avoiding booking of substantial volumes since the start of the year.
“Demand still low, with possible small improvement during second half of April due to restocking, with May feeling more positive,” an Italian service center said.
“There are some lights are there by the end of the tunnel, bigger distributors started to talk about restocking, searching for bottom and intensifying the interest,” a distributor said.


Turkey restricts exports to Israel amid ongoing attacks in Gaza
Turkey’s Ministry of Commerce has announced that it has restricted the exports of 54 product groups to Israel, which continues to violate international law with its attacks on Gaza in Palestine since October 7, 2023.
No details regarding these restrictions, which came into force as of today, April 9, have been disclosed yet. There was already public pressure for measures against Israel. Market sources see this decision as “more of a political one”, SteelOrbis understands.
The restricted products include rebar, wire rod and flat steel products, as well as steel pipes and fittings, profiles, iron and steel construction materials, iron-steel wire, cement, aviation and jet fuel and metal processing machinery. It was reported that the measure will remain in effect until Israel declares a ceasefire in Gaza and allows an uninterrupted flow of humanitarian aid to the Gaza Strip.
Meanwhile, in the January-February period this year, Turkey exported 49,990 mt of rebar and 11,387 mt wire rod to Israel. In the given period, Israel was Turkey’s second and fourth main market for rebar and wire rod exports, respectively.


Vallourec partners with NextChem for hydrogen solutions
French pipemaker Vallourec’s hydrogen storage solution, called Delphy, will be integrated into worldwide hydrogen and green ammonia production projects implemented by Italian energy transition specialist NextChem Tech, a subsidiary of Maire Group.
Vallourec and NextChem will research synergies between Nextchem’s green ammonia production technologies and Vallourec’s high-capacity hydrogen storage solution. Delphy will help sort the intermittency issue in producing green hydrogen from renewable energy, ensuring continuous supply to industrial processes, particularly green ammonia production, Kallanish notes.
Delphy is an underground system capable of storing up to 100 tonnes of gaseous hydrogen. In December last year, Vallourec inaugurated a Delphy demonstrator at its site in Aulnoye-Aymeries, northern France. The demo is made of tubes and connections equipped with sealing technology and corrosion resistance. It is installed underground and is designed for green hydrogen producers and users for industrial applications and heavy mobility.
Over the past two years, Vallourec has been developing its New Energies division, a portfolio of solutions designed to support the energy transition, including geothermal, hydrogen storage, carbon sequestration, solar and biomass. The pipemaker is also working on a new protocol to test its tubular solution for safe hydrogen transport. A research team is studying its VAM 21 connection behaviour at temperatures and tensions relevant for the storage of hydrogen.
Vallourec aims to reach 10-15% of Ebitda from New Energies by 2030. Last month, ArcelorMittal agreed to acquire 28.4% of the company. ArcelorMittal ceo Aditya Mittal said Vallourec has a critical role to play in the energy transition, producing vital products for hydrogen, carbon capture and geothermal applications, for which demand is expected to grow (see Kallanish passim).
Natalia Capra France


Demand growth sluggish; costs, overcapacity hit industry: OECD
Global steel demand growth will continue to be very sluggish in 2024-25 amid deteriorating market conditions, says the OECD Steel Committee. Steel firms need to absorb higher costs while facing weak demand and surging imports due to global excess capacity.
Demand for steel fell by 3.3% in 2022 and recovered by only half this amount in 2023 as higher interest rates worldwide continue to depress construction activity and investment. High and persistent inflation is meanwhile reducing spending on steel-intensive durable goods and has led to higher raw material costs for steel firms since June 2023, the committee noted following its 95th session in late March.
World crude steelmaking capacity in 2023 is now estimated at 2.439 billion tonnes, exceeding production by 552 million tonnes. Around 23mt of potential new capacity growth in ASEAN during 2024-26 is through cross-border investments or joint venture investments.
China has made significant progress in limiting domestic crude steelmaking capacity growth. “Still, in addition to growing Chinese investment in Southeast Asia, there is growing concern that substantial financial incentives in China, such as tax benefits, grants, and research funding, are encouraging the capacity of higher value-added steel products. This implies that excess steel production capacity is ‘moving up the value chain’, seen in the recent shift in the composition of exports of Chinese steel and steel-using downstream products over the last years,” committee chair Ulf Zumkley says in a note seen by Kallanish.
A new committee study shows that the use of subsidies per unit of steel producing capacity in the form of cash grants has increased fivefold in non-OECD economies that are not members of the Steel Committee from 2005 to 2021. Subsidies in the form of below-market financing – soft loans – have doubled. Each $1 million of subsidies through grants is associated with capacity increases of about 7-11 million tonnes in the non-OECD area.
Steel trade dynamics underwent significant changes in 2023, marked by a 40% increase in China’s steel exports compared to the previous year, while Southeast Asian exports also grew amid capacity increasing faster than demand. This could lead to more widespread usage of trade defence instruments.
Adam Smith Poland
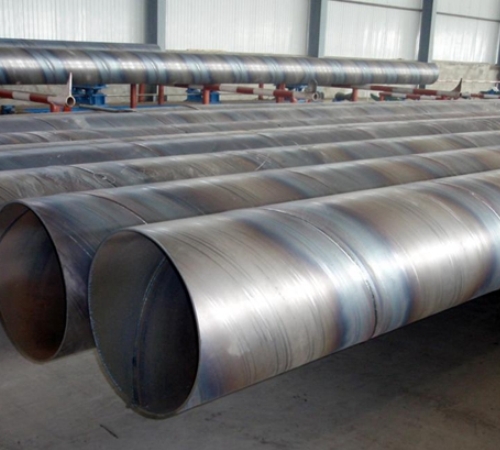
Italian welded tube prices to increase
Some Italian welded tube re-rollers will increase prices starting this week. Sources from hot rolled coil mills, re-rollers and distributors are registering a price floor for domestic and imported HRC, with expectations of some mild increases for European coil and derivatives.
The unsustainable price of tubular products is causing margin pressure for all southern European re-rollers. An Italian tube maker sees production costs increasing in 2024, worsened by the several production stoppages implemented this year to balance demand and supply.
Some tube demand improvement is being reported in Italy. Last week’s activity was slightly higher than usual and positive signs are coming from those end-users who have suffered a strong order contraction in recent months, Kallanish hears.
A re-roller confirms he is starting to decrease discounts by a couple of points this week. Although the fragile market conditions persist, a gradual increase made of “small steps” is achievable in the coming weeks. Until last week, discounts in Italy stood at 38-39 points.
European HRC levels are expected to recover by €10-20/tonne ($10.8-21.6) in contracts in the coming weeks. Steelmakers say they cannot sustain the average level of €650/t base delivered and will try to push up values towards the level of €680/t.
Natalia Capra France

French rebar flattens in quiet market
French rebar prices are flat compared to the end of last month after values decreased in March by some €10/tonne ($10.8) on average. Sources in the market are reporting quiet activity and back-to-back sales, with no change from previous weeks, Kallanish hears.
The first ten days of March were “acceptable” in terms of domestic sales, distributors say. However, since mid-March, consumption has fallen again and sales are low. Construction firms continue to buy only small tonnages each week and report limited visibility. Continued uncertainty and quiet activity, particularly last week after Easter, are impacting turnover throughout the value chain.
French rebar values are hovering at €620/t delivered on average, sources suggest.
The domestic construction sector is officially going through a recession, as confirmed recently by national construction federation Fédération Française du Bâtiment (FFB). New construction fell by 23% year-on-year over the three months ending January 2024.
Activity in some sectors of the industry fell more steeply, such as construction of individual houses which declined by as much as 41% between January 2023 and January 2024. The crisis involves all building segments including non-residential (see Kallanish 20 March).
Natalia Capra France

EU stainless coil prices rise
European contract prices for stainless cold rolled coil are increasing following the hikes implemented by steelmakers last month, sources tell Kallanish.
Over recent weeks, the steelmakers in operation have gathered orders that could not be placed with Acerinox or Outokumpu due to strikes impacting both plants for very different reasons. The long absence from the market of these two producers has balanced demand and supply.
Mills in Europe are now selling at €2,650/tonne ($2,871) delivered on average for CRC, with lead times lengthening into June and July. Italian contract prices are also increasing but lagging behind compared to other EU countries. Until last week, domestic stainless CRC stood at €2,530-2,550/t on average for July lead times, with asking prices at €2,600/t base delivered.
Contracts in Italy are however expected to increase on lower availability and better demand. Domestic hot rolled coil is being sold at between €2,300-2,370/t delivered due to the presence of cheaper import offers from Asia. Prices of both coils and sheets in Europe may continue to rise. Two European producers are currently not quoting for coil.
The stainless flat steel market is generally improving because coil offers are limited. Downstream sheet demand seems to have somewhat resurfaced, service centres in northern and southern Europe say, after 18-20 months of depressed consumption. According to two sources, the current improved activity should last until the summer.
Sheet prices are at €2,700-2,750/t ex-works in Europe, depending on country. The lowest point of the range has been registered in Italy, which remains the sick man of Europe.
A fire broke out at Acerinox’s plant in Los Barrios, Cádiz on 2 April, which the company says was started intentionally. The fire occurred at the company’s paper warehouse and firefighters put it out immediately, preventing serious damage to the plant. The workers’ strike there continues.
Natalia Capra France

Polish rebar, wire rod prices continue to decrease amid slow trading
Rebar
Polish mills offered April-production rebar at 2,700 zloty ($682) per tonne CPT, which nets back to about 2,670 zloty per tonne ex-works, sources told Fastmarkets.
For volumes bigger than 500 tonnes, mills were willing to grant a discount of 20-30 zloty per tonne.
These levels were lower compared with the previous week when rebar was offered at 2,700-2,740 zloty per tonne CPT, which is equivalent to 2,680-2,710 zloty per tonne ex-works.
Market participants estimated tradeable market levels at 2,700 zloty per tonne CPT for small tonnages, which nets back to about 2,670 zloty per tonne CPT.
The workable market level for volumes larger than 500 tonnes was 2,670-2,680 zloty per tonne CPT, which equates to 2,650-2,660 zloty per tonne ex-works, according to market participants.
But lower prices failed to spur trading and no major deals were heard in the market, .
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, exw Poland was 2,650-2,670 zloty per tonne on Friday, down by 30-40 zloty per tonne from 2,680-2,710 zloty per tonne on March 28.
“Consumption is not that bad, but customers are still receiving the material they have already ordered. Once [the ordered volumes] are delivered, they will start buying again,” a producer source told Fastmarkets.
According to a consumer source, the Polish rebar market was quiet in the first week after Easter, but more deals are expected in the coming week.
Buyers shared mixed views about the rebar market’s development in the near future.
“Demand for unprocessed rebar is bad; [it] seems that prices will have to go down further,” a distributor source told Fastmarkets.
“On the other hand, the cut-and-bend sector is doing well, so maybe Polish mills will not be eager to continue with decreases,” the distributor added.
According to a second distributor source, demand from the cut-and-bend sector is not the same in all regions of Poland, and from their perspective, it was poor this week and the previous week.
They added that cut-and-bend companies had bought some volumes in recent weeks due to dropping prices and the fact that they had foreseen higher prices for the material in their budgets. The second distributor source was also pessimistic about demand from the construction sector in the next two months.
The direction of Polish rebar prices will be clearer next week when most new scrap contracts for the month will be signed, the second distributor source added.
Strong competition from imports also continued to put pressure on the domestic rebar market in Poland. Offers of the material from Germany were heard at €615-620 ($667-673) per tonne delivered. Offers of rebar from Hungary and Italy were heard at €615 per tonne delivered.
Wire rod
Polish mills continued offering drawing-quality wire rod in the range of 2,850-3,000 zloty per tonne CPT in the week to Friday, sources told Fastmarkets.
These offers were unchanged from price levels last week when Polish wire rod producers cut their official offers to stimulate buying.
But demand remained low with no restocking, a third distributor source told Fastmarkets.
Bids were heard at 2,800 zloty per tonne CPT.
Sources indicated tradeable market levels in the range of 2,800-2,900 zloty per tonne CPT but no major deals were heard in the market.
Fastmarkets’ price assessment for steel wire rod (drawing quality), domestic, delivered Poland was 2,800-2,900 zloty per tonne on Friday, widening downward by 50 zloty per tonne from 2,850-2,900 zloty per tonne on March 28.
According to market participants, some restocking could be expected during the Tube and Wire trade fair in Düsseldorf, Germany, on April 15-19.
Import offers of drawing-quality wire rod from Italy were heard at €650-670 per tonne CPT.
Offers of mesh-grade material from Italy, Moldova and Ukraine were heard at €630 per tonne CPT.
Published by: Darina Kahramanova