

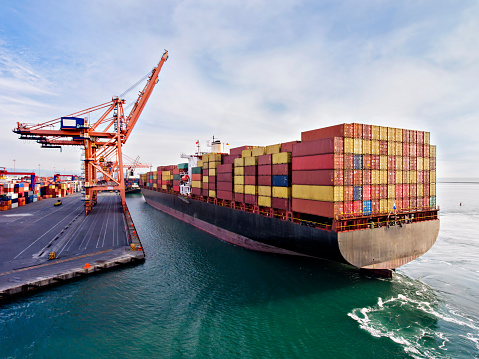
Slumping freight rates struggle to entice more containerized metal trade
The global trade for metals shipped in containers is being constrained by weak demand despite lower freight costs and higher availability of boxes compared with earlier in the year, sources have told Fastmarkets.
Shipping markets throughout 2021 were characterized by stronger demand causing an acute shortage of boxes, leading to a sharp rise in freight costs for metal market participants.
But the tide has changed dramatically in the second half of 2022, with global shipping giant Maersk noting last week that rising inflation has led to consumers spending less on “non-discretionary items such as furniture and home appliances.”
Container head haul and regional export volumes fell by 9.3% year on year in September, according to Container Trade Statistics, as quoted by key shipping industry body BIMCO. Volumes into North America fell by 20.6% year on year in the same month.
The benchmark Shanghai Containerized Freight Index (SCFI) fell to 1,443.29 points on Friday November 11, down by 135.92 points from a week earlier. The index, which has fallen consistently since the start of the year, was at 4,643.79 points in September 2021.
The SCFI is a key indicator based on the freight rate and volume of 12 container freight routes around the world, reflecting changes in global freight rates.
Effect on scrap metal markets
Empty containers are now piling up in port depots, according to various media reports, and although metal market participants are experiencing far greater ease in obtaining boxes, they are being prevented from taking full advantage of the situation by the low demand for metals.
“Last year, if buyers in Europe asked for non-ferrous scrap from the Middle East, there was no point discussing it, but now it is possible again,” a United Arab Emirates-based scrap exporter source told Fastmarkets on Tuesday.
Freight costs for a 20ft container of scrap from Dammam in Saudi Arabia to main EU ports have fallen to around $2,500-3,000 per box in recent weeks after having hit $8,000-10,000 per container last year, the exporter source said.
But in spite of the lower freight costs, the situation has not resulted in many more sales to the region because of poor demand for aluminium scrap in Europe, he added.
November shipment containers from Los Angeles and Long Beach in the US state of California to the Taiwanese port of Kaohsiung were quoted at $750 per 20ft container and $835 per 40ft container on Thursday. The price had risen above $1,000 per container earlier in the year, according to market sources. But Taiwanese steel scrap demand remains tepid amid weak local steel consumption.
“Steel order books everywhere are the worst I’ve seen in a very long time. It’s not easier with container rates coming down – it’s still not enough compared to bulk. In India, container rates are still much higher than bulk,” a US scrap exporter source said on Wednesday.
A second US exporter source said on the same day that dealing with containers was still a “mess” and less efficient than selling scrap in bulk.
A Taiwanese steel scrap trader said that his US scrap suppliers no longer have any problems in obtaining containers but inland transport costs in the US remain expensive.
A major Japanese scrap exporter said that the lower container freight costs have made steel scrap sales from Australia to Southeast Asia possible again, but low demand in Asia was limiting trade on the route.
Effect on ore markets
The lower freight costs have also reduced prices for ores, which are priced by the tonne and therefore transportation costs pay a larger role in overall costs.
Freight rates for South African miners of ore – such as manganese or chrome – exporting to China have fallen by around 46.49% over the second half of 2022 according to Fastmarkets’ assessments.
Freight rates for the Port Elizabeth, South Africa, to Tianjin, China, route were assessed at $29 per tonne on November 11, which is the lowest since January 2021.
Lower freight rates for South African ore producers selling on a CIF basis removes cost support from the market, according to sources.
And this also lowers the offer price point at which it is profitable for manganese ore sellers to truck material to ports. Trucking is used in addition to the volumes moved at lower cost by rail.
In this way, lower costs encourage manganese ore producers to increase the volumes they offer in the market even at a time that demand is weak and inventories are high, sources told Fastmarkets.
Fastmarkets’ manganese ore index 37% Mn, cif Tianjin was calculated at $3.98 per dry metric tonne unit (dmtu) on November 11, down by 1 cent from $3.99 per dmtu a week earlier. This is the lowest price for this material since December 2020.
Ore exports from South Africa are still recovering from October’s strike by logistics workers, as well as a derailment and berthing delays in Maputo, Mozambique, while road transportation is being hampered by poor weather.
Outlook for freight rates
There are mixed views on how container freight rates could develop over the coming months.
“The remaining congestion that helped to prop up the supply/demand balance should dissipate quickly. Liner operators will then be left with lower volumes than in 2019; a fleet that has grown 11.8% since then; an orderbook set to add 9.9% to the fleet in 2023; and poor prospects for the global economy,” Niels Rasmussen, chief shipping analyst at BIMCO, said.
Regulations to reduce the carbon intensity of large-volume shipping may reduce as much as 10% of the global fleet in 2023, but barring any major surprises, BIMCO expects to see “numerous laid-up ships or freight rates that continue to move quickly downwards, or both”, Rasmussen said.
“Some analysts are forecasting a hard landing for container shipping with rates continuing to slide in the coming weeks, potentially going below 2019 levels, before a rebound kicks in,” shipbrokers Banchero Costa said on November 8.
“During the period of high container rates and shortage of equipment, a good portion of cargo shifted back to break bulk shipments. But if the rates continue to crumble, I guess also we will see some of that cargo go back in containers again and that also the rates for conventional shipping will come under pressure,” Gina Swenters, executive director of shipowners Conti-lines Group, said at the EUROMETAL International Steel Trade Day in Antwerp last week.
Published by: Jon Stibbs, Lee Allen, Claire Patel-Campbell, Holly Chant

US, EU steelmakers form carbon reduction coalition
A coalition of steelmakers in the US and EU has formed in order to urge authorities to adopt more rigorous carbon emissions standards for steel production, Kallanish understands.
The Global Steel Climate Council (GSCC) consists of several leading steel manufacturers and groups throughout both the US and EU including Nucor, Steel Dynamics, Celsa Group, and the Steel Manufacturers Association.
“We have the technology to reduce carbon emissions in steel production by 70% today. The global industry needs to build on the innovation that has already led to cleaner steel production in the United States because the green and digital economies around the world are going to be built with steel, and the steel they are built with matters,” says Nucor chief executive Leon Topalian.
According to the GSCC, the new emissions standards negotiated between the US and EU should focus on the amount of carbon emissions being generated through steel production processes, rather than being based on how steel is being made. The coalition boasts that over 70% of US and 40% of EU steel is made using electric arc furnaces from recycled scrap.
“The GSCC single standard will encourage all producers to reduce their carbon emissions and create a level playing field for all manufacturers. The US-EU negotiations should not create a double standard and a slippery slope toward a dirtier environment. We can do better,” adds Steel Manufacturers Association president Philip Bell.
Zach Johnson USA


European Commission opens investigation into bulb flats
The European Commission has opened an anti-dumping investigation into imports of bulb flat bars from China and Turkey. The investigation was anticipated by a letter sent to interested parties, including the Turkish Steel Producers Association, TCUD.
The HS code of the product in question is 7216.50.91. The complaint was lodged by Spanish steelmaker Laminados Losal.
The final decision on the investigation is expected by the beginning of 2024, with provisional measures possibly announced in mid-2023, Kallanish notes.
Emanuele Norsa Italy
Celsa’s Rubiralta Rubio elected Eurofer president
Francesc Rubiralta Rubio has been elected president of Eurofer, the European steelmakers’ association. He takes over from Geert Van Poelvoorde who has been president since 2015, Kallanish notes.
Rubio will continue the successful leadership of Van Poelvoorde, having been a very active member of the board for 12 years. “At the same time, he will bring further momentum for accomplishing the ‘green steel revolution’, ensuring access to affordable, low-carbon energy and steel scrap – which is essential for the industry’s decarbonisation – while preserving the strategic autonomy of our sector, as we are now struggling with unbearable energy costs and new, massive import surges from third countries,” says Axel Eggert, director general of Eurofer.
Rubio has been chief executive and chairman of Celsa since 2010, taking over the role from his father. The Celsa Group is specialised in the production of long products using the EAF route. It is headquartered in Spain, with operations in various countries such as the UK, France, Poland and Norway. According to the group’s website, Celsa produces some 6.6 million tonnes/year of steel products, recycling over 7mt of scrap.
Emanuele Norsa Italy

Shifting trade flows challenge logistics, mills
Deviations in trade flows are challenging markets and spurring mills to maintain production discipline, speakers said at last week’s Eurometal International Steel Trade Day in Antwerp, attended by Kallanish.
Logistics companies increasingly “may have to go to countries with no previous relations, and we may have to pay an entrance fee for that, as they are not awaiting us”, said Gina Sventers of Conti-Lines. As an example of redirected trade flows, she pointed at the advantages for mills in the Middle East, with their lower costs for natural gas used in production. “One Far Eastern buyer in recent months bought half a million tonnes of rebar from GCC countries, which they normally used to buy from Turkey,” she said.
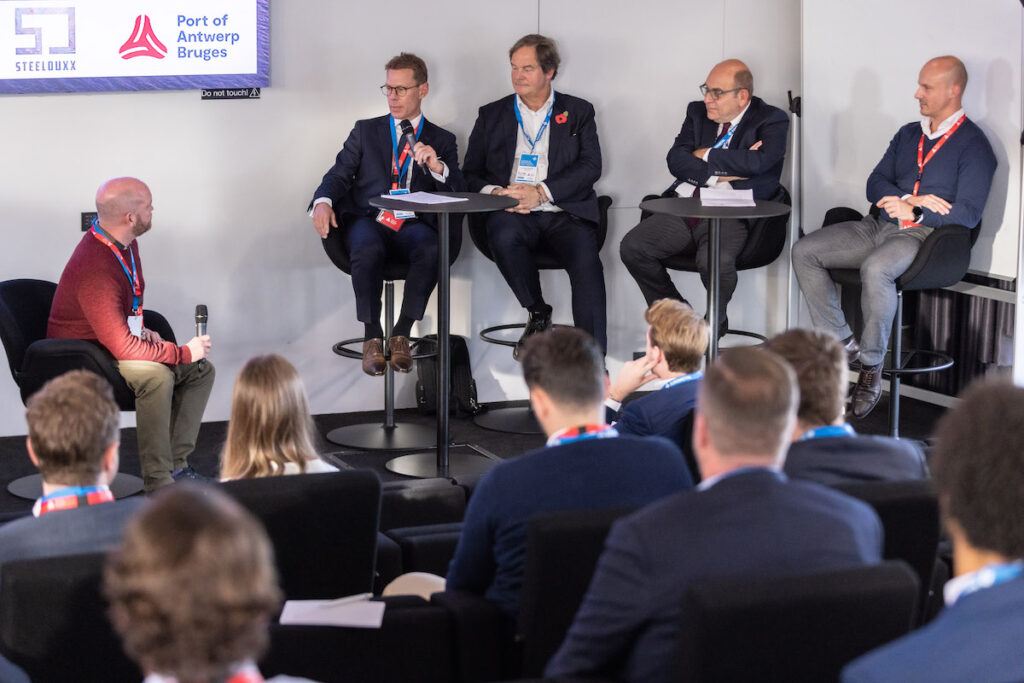
A Turkish observer, Tayfun Iseri of flat steel association Yisad, noted that mills “need to learn to cut production, rather than prices, when the market is low.” He cautioned that “the lower the prices, the more customers will wait for even lower prices.”
He recalled the market turmoil in 2015, when Chinese sellers exported a six-digit tonnage of coil to Europe. “They wasted us and themselves until their government stepped in and put an end to it,” he reiterated. “Back then, we sold coil below the price of billets.”
Christian Koehl Germany

Cognor orders Danieli inspection line
Cognor has ordered from Danieli Centro Maskin a cand inspection line for its plant in Stalowa Wola, allowing the Polish steelmaker to benefit from up to 15% savings in energy consumption and full line set-up times, says Danieli.
The new installation will consist of a fully automated, high-productivity straightening line, a deburring unit and bar handling to process diameters up to 250mm, and with speeds up to 25 m/minute. It will commission at end-2023.
The line is designed for future predictive maintenance through the monitoring and analysis of the data acquired by the sensors installed across the line, to predict the remaining lifetime of the components and to set a preventive maintenance service, Danieli observes.
Earlier this year, Cognor contracted Danieli to replace the existing transformer serving its 48-tonne electric arc furnace in Stalowa Wola (see Kallanish passim). The Stalowa Wola steelworks belongs to Cognor’s Huta Stali Jakosciowych (HSJ) unit, which produces heavy plate and various long products, as well as stainless and alloy steel.
Last year, Cognor also contracted Danieli to supply a merchant bar rolling mill that will replace the current line at its Zawiercie location, as well as a rebar spooling line that is to be located at its Krakow site.
The firm said last month the EAF/blast furnace cost competitiveness trend reversed in the third quarter, in favour of EAF mills like Cognor, as scrap prices dropped faster compared to those of iron ore and coking coal. This supported the firm’s billet sales. However, high energy costs pushed Cognor to promptly deliver some previously contracted supply to cover costs arising from stoppages.
Adam Smith Poland

EU sets electrolytic chromium coated steel definitive duties
The European Commission has confirmed definitive anti-dumping duties on imports of electrolytic chromium coated steel (ECCS) from China and Brazil. The Commission also confirmed the collection of provisional duties imposed since May this year.
The investigation started last year following a complaint lodged by Eurofer. On average during October 2021-January 2022, Brazil and China supplied into the EU a combined 6,000-7,000 tonnes/month of ECCS.
The investigation concerned flat-rolled products of iron or non-alloy steel, plated or coated with chromium oxides or with chromium and chromium oxides, classified under HS codes 7210 50 00 and 7212 50 20. European producers of such products include ArcelorMittal in Spain and France, thyssenkrupp in Germany and Acciaierie d’Italia in Italy.
The definitive duties for Chinese companies have been set at 30.7-77.9%, depending on mill. China’s Baoshan was given the lower definitive duty of 30.7%. For all Brazilian imports, the duty has been set at 53.2%, Kallanish notes from the Commission statement.
Emanuele Norsa Italy

Spanish rebar prices fluctuate
Spanish rebar prices have been volatile over the last few days. After mills announced a decrease on Friday of almost €40/tonne ($41.59) for 16mm material, levels have rebounded by almost half this week, Kallanish notes.
“The market saw a positive momentum for buying material last week,” one stockist observes. “However, on Monday some mills raised their selling price by almost €20/t and put pressure on selling centres since they bought a lot of material last week,” he comments. “Now, most distributors are evaluating the international market, anticipating a new correction.”
Meanwhile, the construction sector continues to demand steel. “Large companies are trying to build stock to be able to finish the delayed projects. Although costs of construction remain high in Spain, steel purchases continue growing since the economic situation is not promising for the planning of new projects next year,” one source observes.
On Monday, most mills and the steel distribution chain declared themselves against the indefinite strike by one of the national transport unions. The action lasted only one day and has had minimal follow-up. It has not had a major impact on the steel sector, market participants conclude.
Rebar is currently sold domestically in Spain at €405/tonne ($421.75) base. Including €262/t size extras and €21/t loading expenses, transaction values are at €688/t ex-works. Some offers have also been heard at €685/t delivered for 16mm rebar.
Todor Kirkov Bulgaria
Steel decarbonization needs to focus on implementing technology, markets: OECD
Steel decarbonization needs to focus on implementing technology, markets: OECD The steel industry is making progress towards decarbonization in several areas, while development and implementation needs to strengthened as the sector is not on a trajectory compatible with climate goals, the Organization for Economic Cooperation and Development said in a report.
Support to scale up innovative steel production technologies and nurturing markets for near zero-emissions steel are needed, the Paris-based OECD said in a November paper. Additional sector investments, international cooperation and trade policies for ensuring competitiveness and a global playing field, and a consideration of strategic inputs and social areas are also required, it said.
While an increasing number of initiatives have been launched to support steel decarbonization, the sector’s contributions to meeting the Paris Agreement climate goal by 2050 lags behind, said the report led by OECD analyst Cecile Seguineaud. The steel sector accounts for nearly 8% of global emissions from the energy sector, the OECD said.
“While the nature and implications of the transformation have been largely explored, turning ambition into action is now the imperative,” Seguineaud said. “This echoes the COP 27 Presidency’s call for implementation, the current decade being critical to achieve the Paris Agreement’s objectives.”
While last year’s UN Climate Change Conference, or COP26, raised the urgency of increasing ambition and enshrined the momentum for steel decarbonization through its ‘Breakthrough Agenda’, the focus at this year’s COP27 in Egypt earlier this month has been on active changes for cutting emissions, the report concluded.
The OECD said more than 90% of global steelmaking capacity and production is now located in countries that have announced a net-zero target, while areas with carbon-pricing mechanisms currently cover less than 20% of global steelmaking capacity. Carbon prices have not reached the level that would be required to be in line with a net-zero pathway by 2050, the group said.
There is also a mismatch between country-level pledges and corporate commitments even as steel companies increasingly announced net-zero targets, it said.
“As of end-2021, companies with net-zero targets accounted for 30% of global steel production. This share has doubled over the last year, though more commitments would help reduce the mismatch even more,” it said.
As of the end of last year, 18% of global steelmaking capacity and production was in countries with a net-zero target enshrined “in law”, with about 60% related to a “policy document” and 18% upon a “political pledge,” it said.
Europe accounts for the majority of companies with net-zero targets, while Asian steel companies have increasingly adopted targets and Asia is the second-placed region after Europe in pledges, it said.
The OECD said blast furnace-based steel capacity represents more than half of newly planned capacity, exacerbating the risk of stranded assets, unless equipped with carbon capture, utilization and storage.
Scrap-based electric arc furnaces need help from a more structural shift in steel production for the sector to decarbonize to near zero emissions, it said.
“Beyond the pledges, near zero emission steel production has not yet taken off sufficiently,” the report said.
— Hector Forster


Beltrame Group launches low carbon steel product Chalibria
European steel merchant bar producer Beltrame Group has launched a low carbon steel product called Chalibria to accelerate the transition towards climate neutrality, the long steelmaker announced Nov. 15.
Beltrame said it would obtain the Chalibria products’ carbon neutrality by offsetting CO2 emissions generated by the value chain through the purchase of carbon credits on a voluntary basis, in line with the PAS2060 standard and the ISO14064-1 certification attested by certification company RINA.
The company aims to reduce its CO2 emissions by 40% by 2030 and to achieve this has defined a decarbonization plan and a precise roadmap, Beltrame said.
To achieve this, Beltrame had identified four macro-groups of activities, namely production efficiency, a circular economy, procurement of green energy, and hydrogen projects.
“The emissions generated during the group’s activities are well below average international and European sectors, reaching 570 kg CO2 per ton of rolled steel (Scope 1,2 and 3 upstream), about 75% less than the emissions of the global steel industry and about 15% less than the European average for electric furnace steel emissions,” Beltrame Group CFO and Managing Director Raffaele Ruella said.
However, the company aimed to reduce its emissions by 40% by 2030 from 2015 levels, he added.
The investments of the decarbonization plan, which will be implemented within the timeframe dictated by the European programs, will make it possible to reduce emissions from production processes and consequently to decrease also the purchase of carbon credits over time,” it said.
“Steel is a special material, which can be recycled indefinitely and this is inherently sustainable, but producing it generates emissions and a high energy expenditure,” Beltrame Head of Group Business Development and CEO France and Romania Carlo Beltrame said.
As part of the decarbonization plan, Beltrame aims to strengthen its production efficiency strategy by modernizing its main gas heating furnaces, the design and construction of heat recovery systems and the installation of digital control systems.
For hydrogen projects, it said its furnaces were already designed to be able to use hydrogen as a fuel in a mix with natural gas and the company was preparing for developments in the use of low carbon, or green, hydrogen as a fuel, it said.
Meanwhile, its circular economy activities included improving the quality of scrap and other raw materials, reusing waste, such as the slag from steelworks and refining plants, from the production process and replacing raw materials with recycled materials.
“These applications have allowed the group to consolidate the waste reduction process and by-products sent to landfills, favoring their recovery in internal or external cycles factories, covering approximately 90% of their total today,” it said.
Beltrame also aims to increase its use of green energy by developing renewable energy plants for self-consumption and supply contracts of renewable electricity through power purchase agreements, it said.
In 2022, it created a consortium with two other companies to invest in the construction of renewable energy sources and to supply energy electricity produced by the plants to each member.
As part of its increasing investments to minimize emissions, it said good progress had been made on the construction of a photovoltaic park near its plant in Targoviste, Romania to reduce energy consumption.
The park is due to have an installed capacity of 60-65 MW, with the company also planning to install 10 MW photovoltaic panels on the roofs of its buildings to have a total power generation capacity of 70-75 MW by late-October 2023.
Beltrame said it was evaluating further initiatives to increase the share of low carbon energy.
For the emissions that it would not yet be able to reduce through the decarbonization plan’s projects, it would use carbon offsetting, it said.
Platts, part of S&P Global Commodity Insights, assessed the weekly TSI Northwest Europe rebar price at Eur800/mt ex-works Nov. 9, up from Eur790/mt ex-works at the start of the year, but down from the intra-year high of Eur1,340/mt ex-works reached March 30.
— Jacqueline Holman