

Acciaierie d’Italia idles part of Taranto hot end
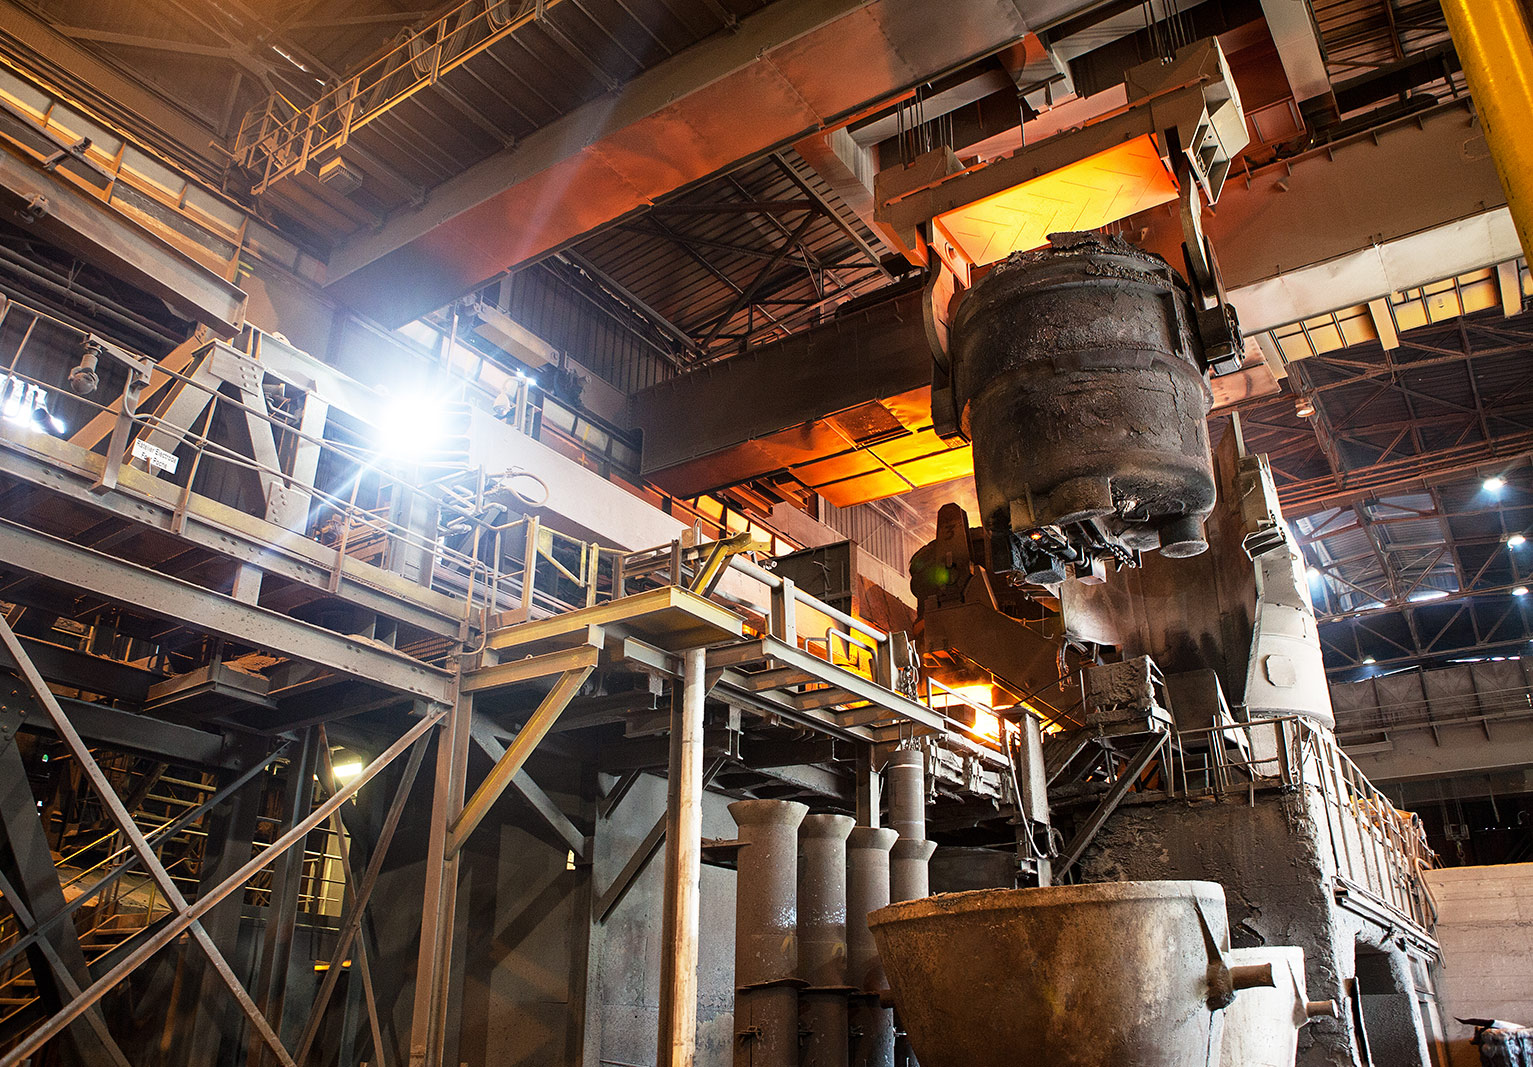
Acciaierie d’Italia, the joint venture between ArcelorMittal and state-owned Invitalia, is to again idle blast furnace no.4 at the Taranto steelworks from 1 December because of a technical issue. This will cause meltshop no.1 to also be idled for over a month, together with continuous casting units no.1 and 5, Kallanish learns from union sources.
While Taranto’s cold rolling mill is currently operating, workers believe it is only a matter of time before it is also idled. BF no.4 and the rest of the mothballed equipment are planned to be restarted on 20 January.
In October, the steelmaker restarted BFs1 and 4. The latter was idled for about seven months and the company spent €70 million ($79m) on upgrade works.
Acciaierie d’Italia posted approximately 4.4 million tonnes of output in 2020. Unions believe the target of 5mt for this year may not be reached. Until 20 January, Taranto will be working with two blast furnaces, no.1 and 2, and meltshop no.2, Kallanish notes.
Natalia Capra France

EU construction recovery to slow following 2021 jump
European construction activity is set to jump 5.6% year-on-year in 2021, performing better than previously expected, according to the latest forecast issued by Euroconstruct.
The recovery will take construction activity in Europe to above pre-Covid levels. “The upward correction is based on numerous factors: the synchronous international upswing, the use of infrastructure investment as a classic instrument of fiscal policy, the introduction of generous incentives for building renovation and the growth of the housing sector against a backdrop of low financing costs and rising real estate prices that have favoured the upswing in investment,” says the research and consulting network.
“In addition, the changes induced by the pandemic affected some phenomena already underway, accelerating them or triggering new demand,” it adds.
Going forward, a positive trend for construction in Europe will continue to 2024, but the speed of recovery will slow significantly. Euroconstruct expects activity to jump a further 3.6% y-o-y in 2022, before seeing growth stabilise at 1.2-1.5% y-o-y each in 2023 and 2024, Kallanish notes.
“All non-residential construction sectors will show a relatively better short-term performance, against a more moderate increase in the level of expenditure for housing: in particular, for civil engineering, a growth rate close to 3% per year is estimated, not so far from that expected for non-residential building (+2.5% on average 2022-2024), while for the biggest European market the slowing path should be more pronounced (+1.6%),” Euroconstruct writes in its blog.
At a country level, the positive development is sustained by strong growth of over 4% in Ireland, Spain, Hungary and the UK. A flat trend is expected for Germany and Switzerland, while sectoral output is expected to shrink in Finland and Sweden, the firm concludes.
Emanuele Norsa Italy
Nippon Steel plans India expansion; eyes mill in Southeast Asia
Japan’s Nippon Steel reiterated its plans to raise the crude steel production capacity of its ArcelorMittal Nippon Steel India (AM/NS India) joint venture as well as to establish an integrated steel mill in Asia, the steelmaker said Nov. 30, as part of its global expansion plans.
Under consideration are plans to expand the capacity of AM/NS India, which includes “the construction of a second steel mill,” Eiji Hashimoto, representative director and president of Nippon Steel, said, as well as either buying or taking a taking a stake in a steel mill in Asia, particularly in Asean.
Recently in Southeast Asia, India’s Tata Steel sold its 100% stake in NatSteel Holdings to TopTip Holding, a Singapore-based steel and iron ore trading company, Sept. 30 for $172 million. Tata Steel also plans to sell Tata Steel Thailand, which is the largest domestic producer of long steel products with 1.7 million mt/year of production capacity.
On April 1, 2022, Nippon Steel plans to merge its two Thai subsidiaries, NS-Siam United Steel (NS-SUS) and Siam Tinplate (STP) to consolidate the manufacturing and sale of cold-rolled and hot-dip galvanized steel sheets. The merged company will have production capacities of 1 million mt/year of CR steel, 360,000 mt/year of hot-dip galvanized steel, 140,000 mt/year of tinplate and 120,000 mt/year of tin-free steel.
Nippon Steel’s expansion is in line with its restructuring plans that are expected to be completed by March 2026 which include reducing the number of blast furnaces in Japan to 10 from 15. The reduction will lower its domestic crude steel production capacity by 10 million mt/year or about 20% of its overall output.
“We will shift into high gear in full-scale oversea business that will ensure higher added value,” Hashimoto said, as Nippon Steel plans to build up 100 million mt/year of crude steel production capacity globally, up from about 71 million mt/year at present.
The output expansion includes doubling the production capacity of AM/NS India to 14 million mt/year while a new 1.5 million mt/year electric arc furnace at its AM/NS Calvert venture in Alabama is due to be started up over the first half of 2023.
Locally, Nippon Steel aims to start operating a new EAF at Hirohata in the first half of 2022 with a production capacity of 60,000 mt/month, which will be used for electrical steel sheet making.
While expanding its crude steel output, the Japanese steelmaker reiterated its goal to be carbon-neutral by 2050, with plans to cut its carbon dioxide emissions down to 70 million mt/year by 2030 from 91 million mt in 2019.
“Our idea of a ‘zero-carbon steel production process’ is to combine two steelmaking routes, utilizing their respective features: the BF and basic oxygen furnace (BOF) route, and the EAF route,” Hashimoto said.
Zero-carbon steel “has its own big challenges,” Hashimoto said, pointing out that the “needed innovations” will cost about Yen 500 billion ($4.4 billion) for research and development and Yen 4 trillion to Yen 5 trillion in capital expenditure.
— Clement Choo

China’s manufacturing PMI rebounds in Nov, but outlook remains sluggish
China’s manufacturing purchasing managers’ index, or PMI, rebounded to 50.1 points in November, an expansion in manufacturing activity for the first time in two months but still the third lowest in 21 months, China’s National Bureau of Statistics said.
China’s PMI was seen at 49.2 points in October and at 49.6 points in September. PMI, which indicates direction of economic trends in manufacturing, is in contraction if the reading is below 50 points.
As power shortages eased in November, it led to improved manufacturing production in China.
However, new orders have now remained in contraction for four straight months. Similarly, new export orders contracted for the seventh month in a row.
Market sources told S&P Global Platts that they expect sluggish domestic consumption and slowing property investment would continue to weigh on the recovery of the manufacturing industry and its demand for steel into 2022, especially as overseas orders for Chinese goods were tapering off after overseas factory operations gradually return to normal.
Some steel mill sources said steel demand from vehicle and home appliances sectors — indicators of consumption-related manufacturing — showed no signs of improvement in November.
One source said passenger car production was likely to increase in 2022 due to easing semiconductor chip shortages.
“But the growth [of passenger cars] should be limited, as [China’s] domestic consumption is likely to remain sluggish amid intermittent new COVID-19 cases and slowed economic growth,” the source added.
Meanwhile, property investment is expected to trend downwards in 2022 due to declining new home sales and land purchases at a time of tightened credit borrowing, according to some steel market participants.
Construction-related manufactured goods, as well as home appliances, will continue to feel the heat brought about by property sector, sources said.
Given the prospect of a slowdown in domestic steel demand, China’s steel production in 2022 is unlikely to exceed the level in 2021, even without any government requirements, according to sources.
According to NBS, sub-indexes of manufacturing production rebounded to 52 points in November, up from 49.2 points in October and 49.6 points in September.
New orders and new export orders also rebounded by 1.4 and 1.9 points from October, but were still in contraction at 49.4 and 48.5 points, respectively.
— Staff
ABB tool to improve meltshop productivity
ABB has launched what it claims is the first smart factory digital application of its kind for the metals industry, Kallanish hears from the technology supplier. This is set to help improve efficiency in crude steelmaking.
Based on advanced digital algorithms, ABB Ability Smart Melt Shop offers real-time ladle tracking, automated crane scheduling and a predictive thermal modelling engine, the firm observes. The tracking engine follows ladle movement via cranes and transfer cars in real time. Radar and laser positioning technologies provide accurate visualisation while reducing hardware footprint and maintenance needs.
According to ABB, this will enable steelmakers to move towards autonomous operations by eliminating manual co-ordinations, with increased safety in hot zones due to lower footfall. Mills can expect 4-5% higher casting speeds to improve productivity and reduce arcing by 5% degrees Celsius per heat in ladle furnaces, ABB claims.
The application has already been installed by JSW Steel in India at the Dolvi works in Maharashtra. ABB says it expects to increase the mill’s profit by around $2 million/year through 4% higher casting speeds, time savings of one working day per month and additional output of 24,000 tonnes/year.
Christian Koehl Germany

Metinvest increases Italian plant plate capacity
Italy-based Trametal, the re-roller subsidiary of Ukrainian steelmaker Metinvest, has started a new plasm cut trimmer edge line at its plate rolling mill in San Giorgio di Nogaro, near Udine, Kallanish learns from the company.
The new master plasma bevel Line Tech Nova 55 was assembled in a warehouse adjacent to the main plate mill. It will boost output from the current 65,000 tonnes/year to approximately 235,000 t/y.
The plate mill has an overall capacity of 600,000 t/y. The expansion is in line with the company’s plan to respond to increasing demand from the Italian and European shipbuilding sector, selling more material to large shipbuilders such as Fincantieri, Metinvest explains.
The €10 million ($11m) investment for the new equipment has been funded by a state-guaranteed loan granted by Cassa Depositi e Prestiti S.p.A (CDP).
In 2020 Metinvest Trametal signed its first facility with CDP for €15m. The six-year term loan facility, with a two-year grace period, was issued under an Italian government programme guaranteed by SACE S.p.A., the state-owned export credit agency. This comes under the “Garanzia Italia” initiative to support companies through the international health crisis.
Natalia Capra France

EU steelmakers must compete for hydrogen resource: Jeffries
The green hydrogen requirement to fuel green steelmaking in Europe would amount to 1.2 million tonnes by 2030, below the EU’s Hydrogen Strategy target, but the steel industry will be fighting over the resource with other sectors, says Jeffries. Green hydrogen costs would meanwhile need to decrease 75% to $1.20/kg for H2-DRI/EAF costs to break even with the traditional BF-BOF route.
As EU steelmakers decarbonise, electric arc furnaces’ share in the bloc’s steelmaking will rise to 55% in 2030, with iron ore and scrap demand up 17% and 4% versus 2019, but coking coal demand down 13%, says Jeffries.
The industry has identified hydrogen-based iron-making as the path to decarbonisation. However, the question is, “will hydrogen, and specifically green hydrogen, be available to meet these ambitions?” Jeffries points out in a report seen by Kallanish.
Under Jeffries’ “business as usual” scenario, European hydrogen demand is forecast to increase – relative to 2015 – by 48% by 2030 and 140% by 2050. In the ambitious scenario, these increases are 105% and 593% respectively. Heating and power for buildings, and transportation are the two largest incremental drivers of hydrogen demand, contributing 65% of the total increase by 2050. Industry energy, which includes steelmaking, is forecast to be 12% of the incremental demand.
Jeffries estimates electricity usage from steelmaking will grow 135% by 2030 versus 2019. Despite hydrogen-based steelmaking forecast comprising some 10% of EU steelmaking by 2030, it would represent 54% of sector electricity consumption.
The forecast for $1.20/kg hydrogen cost being required for H2-DRI/EAF to break even with the BF-BOF route is based on long-term assumptions for iron ore of $80/tonne, coking coal of $150/t and electricity of €50/MWh.
Vale’s green briquette venture meanwhile provides an example of iron ore providers moving down the value chain and taking ownership of Scope 3 emissions, Jeffries observes. “This may provide an illustration of similar moves by Australian miners and the possible build out of renewable resources and energy infrastructure,” it comments. “However, such a scenario to leverage Australia’s natural resource advantage needs government support at all levels.”
Adam Smith Germany

Chinese mills cut production on Winter Olympics
Chinese steel mills will restrict production in the first quarter of next year to ensure air quality during the Beijing Winter Olympics. At the same time, power cuts in some provinces have caused southern China’s steel mills to reduce production.
Kallanish learns from market sources that restrictions will hit all heavy industrial enterprises in Huabei, Huaibei, and West China, especially Tangshan, Tianjin, Shijiazhuang, Zhangjiakou, Chengde, Shandong, Jinan, Weihai, Weifang, Taiyuan, Datong, Changzhi, Luoyang and Zhengzhou. These will need to suspend or restrict production from 1 January to 8 March 2022. There is no official document to announce the details of the production limit, however.
Individual cities in Shandong have issued policies that require companies with an environmental rating of C grade or below to suspend production completely during most of this production restriction period. Although Tangshan did not announce a similar policy, the Tangshan government adjusted ten grade D steel companies to grade C on Monday.
The central government requires that crude steel production be kept unchanged this year, and this goal is expected to be easily completed in most provinces. Therefore, after getting rid of production restrictions for the purpose of controlling this year’s output, steel mills are expected to increase production to supply restocking demand before the Spring Festival. This is expected to bring around 3 million tonnes of additional production in December, according to Huatai Futures.
Regional production restrictions are also continuing through winter due to power supply issues. Market reports indicate that electric arc furnace steel mills in Heyuan, Guangdong have almost completely stopped production and will restart in early January 2022. The reason for the shutdown is local energy consumption control requirements.
By Kallanish Team

Turkish HDG mills focus on alternative markets amid EC antidumping investigation
Turkish mills have started to focus on alternative markets in recent weeks as the European Commission investigates an antidumping case against hot-dip galvanized steel coil imports from Turkey and Russia on a request from the European Steel Association. The case, which could retroactively impose duties on imports, has increased concerns among European buyers, sources told S&P Global Platts Nov. 29.
“As Eurofer’s move has been expected in the market, demand from the European market has almost disappeared in recent weeks,” an export manager of a Turkish producer told Platts Nov. 29, adding that it has started to focus on alternative markets in this sentiment.
“Nobody in Europe is currently demanding Turkish material due to the dumping investigation, while demand from Ukraine and Egypt is mixed. Turkish producers are currently offering DX51D with 100 g/sq m of zinc coating, 0.50 mm HDG at $1,180-$1,200/mt FOB in this sentiment,” the manager said.
The New Year’s slackness also has begun to dominate the overall market sentiment, and demand from almost all export markets, including the EU, is currently notably below expectations, sources said.
“Demand from the US market also disappeared following the Section 232 deal with the EU. We are currently focusing on the North African market,” a manager of another Turkish coated coil producer told Platts Nov. 29, confirming 0.50 mm HDG offers at $1,180/mt FOB.
Noting that domestic demand also has almost faded away due to the sharp currency depreciation, a general manager of a Turkish steel service center said he is expecting to receive new lower offers both from Turkish coated coil producers and import suppliers in the coming days.
“Low export demand could also support lower prices,” he said.
The EC opened an investigation into HDG coil imports from Turkey and Russia June 24 on allegations that imports of certain corrosion-resistant steels originating from these countries were being dumped, as Platts reported previously.
Predisclosure of the investigation is expected Dec. 24, while provisional measures, if any, will be imposed by the EC until Jan. 24, 2022. Definitive measures could be announced on July 20, 2022, which could raise the pressure on Turkish mills’ HDG pricing.
— Cenk Can

Turkish mills’ sections exports rise, Morocco top market
Turkish steel mills’ sections exports in the first three quarters of the year totaled 1.59 million mt, up 15.7% year on year, according to the latest monthly Turkish Statistical Institute (TUIK) data.
Morocco was the top destination for Turkish sections in January-September at 106,700 mt, up 17% on year, while exports to Malaysia reached 88,000 mt, up 31.3%.
Peru became one of other largest importers of Turkish sections in that period at 87,000 mt, more than threefold higher on year, while Turkish mills’ sections exports to Egypt totaled 77,300 mt, down from the 111,700 mt exported in the same period the previous year.
Turkish mills exported 67,300 mt of sections to Colombia in the nine-month period, while exports to the UK totaled 65,000 mt.
Other destinations were Israel (56,300 mt), Canada (42,000 mt), Italy (36,000 mt), UAE (36,000 mt), Greece (35,100 mt), Argentina (32,300 mt), Iraq (30,500 mt), and the US (29,600 mt).
— Cenk Can