

EU-US agreement on S232 expected soon: Eurofer
A first agreement between the European Union and the US on the existing section 232 measures could be announced in the coming days, according to Karl Tachelet, director for trade and external relations at Eurofer.
Tachelet stressed that a final deal should be reached by the beginning of December to secure the blocking of the doubling of the existing retaliatory measures imposed by Europe on the US back in 2018. “By the beginning of November we need to understand if a deal can be achieved, in order to work toward a final deal by the beginning of December,” Tachelet confirmed.
Eurofer believes that it is very likely that the ongoing negotiations on the topic will result in a deal, Kallanish understands.
“I would be very surprised if an agreement is not been reached,” Tachelet said.
What remains unclear is what an agreement would include. It is understood Europe and the US could agree to a quota system for sales into the US. This would mean a certain volume of European steel would be able to be imported in the US without tariffs being applied. Imports beyond the quotas would sill face the 25% import tariffs.
Europe historically exported over 3 million tonnes of steel products to the US annually, now exports are at some 2m t/y, meaning S232 lowered exports by some 1mt, Eurofer calculates. The association also noted that around half of current exports to the US are products that have been exempted from S232 measures following specific applications by steelmakers.
While expressing support toward an agreement on S232, Eurofer noted that is still needs to look into the modalities of how the quotas will be calculated and applied. Tachelet said, for example, that quotas should be calculated on a country-by-country basis, rather than generally for the continent.
“The S232 measures are a success story for the US steel industry so there is internal pressure from the industry to keep them in place. Nevertheless we expect an announcement and a deal in the next days and weeks,” Tachelet concluded.
Emanuele Norsa Italy


Steel demand recovery ongoing, supply outlook uncertain: Eurofer
The recovery of steel demand is set to continue through 2021, but at “a moderate rate” and subject to a “considerable uncertainty” expected to last until the first quarter of 2022, the European Steel Association said during an Oct. 28 webinar on the state of the European steel market.
The association, also known as Eurofer, said the outlook was becoming increasingly uncertain particularly due to disruptions in the global supply chain, which were likely to seriously affect demand from steel-using sectors, although by 2022 most of the current disruptions were expected to ease significantly.
The association reviewed its apparent steel consumption figure for the whole 2021, which it now forecasts rising by 13% to 146 million mt of steel, up from its previous view of an 11.2% increase.
Steel consumption was forecast to grow by 4.7% in 2022, when it is expected to return to above-2017 levels thanks to a mild but continued improvement in demand from steel-using sectors.
The whole of 2020 was impacted sharply by the COVID-19 pandemic and saw apparent steel consumption in the EU plummet by 10.6%, revised from a fall of 11.1% in the previous outlook, for the second consecutive year after a 5.2% slump in 2019.
Eurofer also reviewed its real steel consumption outlook for 2021, reducing it from a previously expected 7.9% rise to an expected increase of 7%. However, the association was still positive, considering the drop seen in 2020 caused by the COVID-19 crisis when real steel consumption declined by 9.8%, the second consecutive year taking into account 2019’s 4% fall.
Outlook for steel-using sectors
Total output from steel-using sectors was expected to rebound in 2021 by 8.5% after the 10.4% fall in 2020 due to low output levels, although this was revised downward from the 9.3% rise expected in the previous outlook. This was then forecast to grow more moderately in 2022 by 4.7%, Eurofer said.
Construction sector output, which counts for 35% of total steel demand, was expected to rebound in 2021 by 6.4%, revised up from 5.5% in the previous outlook, and increase a further 4.2% in 2022. However, the association said the current global supply chain issues had started affecting the construction sector in terms of materials shortages, which could impact the outlook.
EU construction confidence took a sharp hit in March 2020, falling to 2015 levels. Residential construction was hit by stoppages caused by lockdown measures, but in 2021-22 conditions were expected to remain broadly positive thanks to a slight improvement in economic conditions and government housing supporting schemes, the association stated.
Non-residential construction was the sector that suffered the most, a trend that may continue if smart-working remains partially in place in the post-pandemic scenario. However, civil engineering was expected to boost the construction sector’s performance thanks to public investment in infrastructure.
The second largest steel consumer sector, the automotive industry, was also facing major disruption issues in the supply chain, particularly due to the lack of microchips, which had affected the industry in the first half of 2021 and was expected to persist into the first quarter of 2022.
After a severe slump of 21.2% in 2020, revised downward from 20% in the previous outlook, due to the pandemic, automotive output was set to rebound by 9% in 2021 and more pronouncedly by 12.1% in 2022, Eurofer said.
— Annalisa Villa

ArcelorMittal puts out fresh contract prices for industry customers
Steelmaker ArcelorMittal Europe has issued new contract prices to industry customers with hot-rolled coil contract prices at Eur1,080/mt and hot-dipped galvanized at Eur1,220/mt across Europe, sources told S&P Global Platts Oct. 28.
According to sources close to the company confirming the new contract prices for quarterly and longer contracts, the prices are not for automotive customers but rather for industry customers such as distributors.
An ArcelorMittal spokesperson would not comment on the company’s steel pricing.
Order books for other end-users such as the mechanical engineering or white goods industries have been strong, and one European mill source said some rerollers had already received firm bookings into 2023.
Automotive demand still unclear
The question over automotive demand and the level of volumes being booked by carmakers struggling with production disruption is, however, still looming over the steel market. Contract negotiations are ongoing for the automotive industry.
Earlier this month, a Southern European automotive manufacturer and a European mill were heard to have finalized a long-term HDG contract for Eur1,250/mt — Eur50-100/mt lower than what mills were initially attempting to conclude.
Other mills were heard to be proposing even higher contract prices, between Eur1,300-1,400/mt, for HDG material.
Because of the ongoing semiconductor and chip shortage, the European automotive sector has endured ongoing production disruption, with some auto manufacturers relinquishing previously agreed-upon volumes back to mills, prompting a surge of HDG availability.
“A lot depends on the semiconductor issue,” a German trader told Platts. “If car manufacturers must continue with reduced volumes, it‘ll impact auto steel needs and prices. If the issue can be solved and car manufacturers restart full steam, steel demand and prices will go up strongly again, especially for green steel in the years to come.”
There is also no change in current spot price levels for flat steel from European mills yet as attention is focused on contract negotiations that are currently above spot level prices.
Spot prices remain at current levels
A German distributor said discounts were now available for spot transactions and said automotive contract negotiations were likely to conclude in November. Market participants were expecting higher spot prices in Q1 on the back of prolific gas and electric surcharges from mills, and elevated raw material costs.
The mill source said that the delta between longer term contracts and spot prices “have never been higher,” but that the first positive signs can be seen in Southern Europe where customers start to accept higher prices. The Made in Steel industry fair in Milan, Italy, earlier in October, and the Blechexpo fair in Stuttgart, Germany, this week, have boosted sentiment across the industry but have not resulted in higher spot prices in Europe — yet.
The daily Platts HRC assessment dropped Eur170/mt since its all-time high at Eur1190/mt EXW Ruhr June 25 this year. The Italian HRC assessment fell Eur228/mt since its record peak at Eur1145/mt EXW Italy June 10 this year.
— Laura Varriale, Amanda Flint
Revista Infoacero Octubre 2021
En el siguiente enlace pueden acceder a la edición de Octubre de INFOACERO
A continuación destacamos algunos de sus contenidos:
1. Opinión – Dña. Meritxell Serrano – Junta Directiva de la UAHE.
2. Evolución del Índice de Precios de Productos Siderúrgicos – UAHE.
3. Información Asociativa: Resumen SNF Lisboa (30 Septiembre).
4. Formación y Conferencias: Calidades del Acero, Transformación Digital, Masterclass Kaltenbach Solutions y Lantek.
5. Jornada UAHE: Asamblea General y Conferencias, (Madrid, 25 de Noviembre).

EUROMETAL at Catalonia steel distribution forum 2021
Fernando Espada, chairman of EUROMETAL, and Roberto González, chairman of EUROMETAL Coordination Work Group of National Federations, participated in the XVII Forum de la distribució de productes siderúrgics (XVII Forum for the distribution of steel products), organized by the Unió de Magatzemistes de Ferros de Catalunya i Balears on October 28, 2021.
This initiative was born in 2005 with the aim of creating an open dialogue and enrichment space for the metallurgical sector.
Roberto González was responsible for opening the XVII Forum as president of the UAHE (Unión de Almacenistas de Hierros de España).
The president of EUROMETAL spoke on the panel “trends in our value chain” accompanied by Mr. Alfonso Hidalgo de Calcerrada (UNESID) and Ramón José Aloguín Casas (Solunión Assegurança de Crèdit).
EUROMETAL also contributed in this online forum as a Gold sponsor.
The forum had over 160 participants.
Automotive slowdown to hit ArcelorMittal Florange output
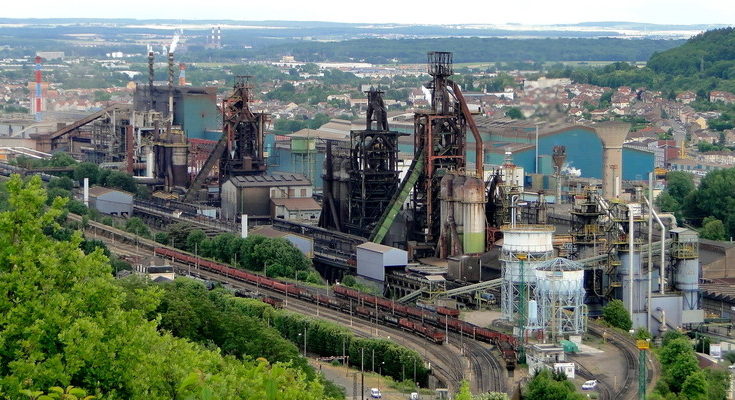
ArcelorMittal has announced to its workforce its intention to temporarily idle some rolling lines at its unit in Florange, France, due to the reduction in demand from the automotive sector, Kallanish learns from local sources.
The company has not issue prior to press deadline an official comment on the matter. It is understood nevertheless that the lines impacted should be those for galvanised coils at the unit, including the second one recently inaugurated. The Galsa line number 1 could be temporary halted from 28 October until 7 November, and the Galsa line number 2 from 18 November until 22 November.
Workers will be invited to take holidays to avoid the need to use layoffs at the site.
If the semiconductors shortage continues to further to impact automotive output, more reductions could be implemented by other steelmakers in the coming months, Kallanish notes.
Emanuele Norsa Italy
Aperam pushes up November alloy surcharges
French stainless steel producer Aperam has increased its November alloy surcharges for its austenitic range of flat stainless steels for Europe by over €50/tonne ($58) on average versus October, Kallanish learns from the company.
The surcharge for grade 304 (1.4301) has gone up from €2,190/t in October to €2,239/t effective 1 November. For grade 316 it has increased significantly from €3,379/t to €3,409/t. Grade 309S, a heat-resistant stainless steel used in high-temperature applications, has also seen its surcharge hiked from €2,969/t to €3,080/t in November. The surcharge for the most popular ferritic grade, 409, has risen from €843/t to €929/t, the company reveals.
Offers for nickel cash buyers were at $19,180/t on 24 September and reached $20,495/t on 26 October, Kallanish notes.
Natalia Capra France

Italian section producers seek increases
Italian beam and merchant bar producers are seeking €30/tonne ($34/t) increases on average because of the increased cost of energy and price hikes expected for domestic scrap in November, Kallanish notes.
Section prices have lost €30/t on average compared to the beginning of the month in line with other long products in the country. Demand, particularly for merchant bar, remains unreliable, with buyers only purchasing back-to-back. Market sources say domestic merchant bar is trading at €450-470/tonne base ex-works while producers are now asking €480-490/t base ex-works. Including €420/t average size extras, local material is at €870-890/t ex-works, sources suggest.
Beam values are now at €570-580/t base ex-work, down from €600/t base ex-works of the beginning of the month. Producers are seeking €620/t ex-works. Including €380-390/t average size extras, the first category of beams is at €960-990/t ex-works. Prices increase by €20/t for each subsequent category, sources say.
Natalia Capra France
Iron ore slides, resists coal’s slump
Seaborne iron ore prices fell a little on Wednesday but remained within their $120+/tonne range. Steel and coking coal prices have fallen more dramatically on weak sentiment and price controls for coal.
The Kallanish KORE 62% Fe index fell $0.76/t at $120.48/dry metric tonne cfr Qingdao. The Kallanish KORE 65% Fe index dropped $1.42/t at $142.32/dmt cfr, and the KORE 58% Fe index fell $0.73/t at $92.02/dmt cfr.
On the Dalian Commodity Exchange, January iron ore settled flat at CNY 700/t ($109.48/t), while on the Singapore Exchange November 62% Fe futures settled down $3.25/t at $117.60/t. The same contract for 65% Fe and 58% Fe futures settled down $5.43/t at $135.91/t, and $3.32/t at $89/t respectively.
Scrap and billet prices too continued their decline. Grade 6mm+ heavy scrap delivered to mills in the Yangtze River Delta fell CNY 7/t to CNY 3,688/t. In Tangshan, billet prices fell CNY 60/t to CNY 4,900/t.
Thermal coal has driven the decline, spreading to coking coal and coke and then other ferrous products. On DCE January coking coal futures settled down CNY 126.5/t at CNY 2,844/t, while the same contract for coke settled down CNY 131.5/t at CNY 3,637.5/t. Speculators have fled futures markets on higher trading costs and government moves to control prices.
Sentiment meanwhile remains weighed down by weak demand, a struggling real estate sector and the deepening winter.

US steel imports up 17% in September; 35% in the first 9 months of 2021
| Top imported products in the US (C&A)Based on DOC data; in mt | |||
| Aug. final | Sept. prelim | % change | |
| Slab | 431,948 | 494,998 | +14.6% |
| HRC | 344,979 | 399,124 | +15.7% |
| OCTG | 106,736 | 219,152 | +105% |
| HDG | 271,936 | 217,915 | -20% |
| Coiled plate | 137,264 | 167,510 | +22% |
| CRC | 121,671 | 146,982 | +20.8% |
| Rebar | 84,816 | 143,950 | +70% |
| Other semis | 103,570 | 121,664 | +17.5% |
| Coated sheet & strip | 109,616 | 110,228 | +0.6% |
| Wire rod | 75,285 | 102,782 | +36.5% |
US steel import volumes in September rose 16.7% month on month to 2.9 million mt and climbed 34.6% year-to-date in the first nine months of 2021 compared with the same period in 2020, according to preliminary US Commerce Department data Oct. 27 and analysis from the American Iron and Steel Institute.
September imports soared 156.4% from the same month last year when the industry was recovering from the onset of the coronavirus pandemic.
The import share of the US finished steel market was an estimated at 25% in September and 21% over the first nine months of 2021, according to the AISI.
Imports of slab and other semi-finished steel increased from August, with slab imports up 14.6% to 494,998 mt and non-slab semis up 17.5% at 121,664 mt, according to the US Census preliminary count.
September imports of hot-rolled coil and cold-rolled coil climbed 15.7% to 399,124 mt and 20.8% to 146,982 mt, respectively, from August levels. Hot-dip galvanized imports dropped 20% to 217,915 mt in the same period.
Oil country tubular goods and rebar imports in September jumped from the previous month, rising 105% to 219,152 mt and 70% to 143,950 mt, respectively.
September imports from South Korea, Mexico and Thailand spiked month-on-month, while higher imports from Turkey and Algeria represented the rise in rebar to the US.
Canada was the largest exporter of steel to the US in September, with preliminary imports from the country totaling 747,027 mt, compared with 695,572 mt in August.
| Top steel exporters to the US (C&A)Based on DOC data; in mt | |||
| Aug. final | Sept. prelim | % change | |
| Canada | 695,572 | 747,027 | +7% |
| Mexico | 383,536 | 401,861 | +5% |
| Brazil | 301,282 | 386,375 | +28% |
| South Korea | 150,800 | 270,998 | +80% |
| Germany | 140,030 | 152,123 | +9% |
— Nick Lazzaro