


EU unites over US tariffs: Polish minister Krzysztof Paszyk
EU countries are united and determined to protect the European steel sector from potential market destabilisation after the US announced blanket steel tariffs, says Polish development and technology minister Krzysztof Paszyk. However, the bloc should negotiate a deal with the US to remove transatlantic trade barriers.
This was the conclusion of a video conference call this week between EU trade ministers, with the participation of Commissioner for Trade and Economic Security Maroš Šefčovič. Poland is heading the EU’s rotating presidency in the first half of 2025.
“Although the EU-US partnership is of strategic importance, Poland will support the European Commission to be active in such cases and to react proportionately and responsibly if necessary. At the same time, we want to maintain the offer of positive cooperation with the US – so as to jointly remove barriers on the transatlantic market or take care of economic security.”
European Commission President Ursula von der Leyen said earlier this week the US tariffs will “trigger firm and proportionate countermeasures” from the EU. However, there have since been calls from within the EU to negotiate a trade deal with the US, rather than retaliate.
European steelmakers’ association Eurofer meanwhile said it expects the EU to urgently revise the existing safeguard regime in response to the US tariffs. The EU could lose up to 3.7 million tonnes/year of steel exports to the US, it added.
Adam Smith Poland


European green steel premiums edge higher in recent deals; traded volumes limited
Across Europe, green steel produced in electric-arc furnaces (EAFs), with Scope 1, Scope 2 and upstream Scope 3 greenhouse gas emissions below 0.8 tonnes of CO2 per 1 tonne of steel, was offered at premiums of €200-300 ($207-311) per tonne during the assessment week.
Bids for such material were reported at €80-150 per tonne. However, several sources pointed out that mills were firmly insisting on prices above €150 per tonne for such specs, considering the costs of production.
“To produce green steel, we have to buy green energy, pay for environmental declarations,” a mill source said. “What’s the point of selling it [green steel] below cost?”
Transactions for such material were reported at €150-170 per tonne over the past seven days.
One large-size deal was also reported within the range of €150-170 per tonne for April-shipment material.
As a result, the green steel premium for flat steel in Europe was stable, with Fastmarkets’ weekly assessment of the green steel domestic, flat-rolled, differential to HRC index, exw Northern Europe set at €150-170 per tonne on Thursday, narrowing upward from €100-170 per tonne a week earlier.
Even though overall traded volumes for green steel were low across Europe, sources pointed out that there was a positive tendency over the past two years.
“In 2021-2022, traded volumes [for green steel] were zero or close to zero. Now we have a market — small, but evolving rapidly,” a buyer in Northern Europe said.
Besides, demand for green steel remained highly regionalized across Europe, with Nordic countries leading the race, sources said.
“In Norway, Denmark and Sweden, there are state-funded projects requiring green steel procurement. Not mass-balanced, but real physically produced green steel,” a second buyer source in Europe said. “At the same time, in Southern and Central Europe, interest in green steel is very low,” they added.
Sources said that, in addition to the high premiums, the lack of public projects across Europe — projects that could insist on green steel procurement — and the lack of stimulus measures to encourage “going green” were limiting demand for green steel.
“Buying steel with reduced carbon content is great for the environment — it’s a step in the right direction. It’s just not affordable when many companies are fighting for survival in a tough market,” a third buyer source told Fastmarkets.
Despite the looming challenges, however, European steelmakers were committed to the green steel transition and expected the market for green steel to grow exponentially in the upcoming years, supported by regulations.
“It’s a very small market so far, but with big potential. We have already seen an exponential rise in booked volumes [of green steel] year on year, and these volumes are only set to grow in the future, supported by the EU’s decarbonization plans,” a second mill source said.


Trump sets roadmap to establish reciprocal tariff regime
The President said in a post on Truth Social ahead of an Oval Office press conference that he had instructed Secretary of Commerce Howard Lutnick, Secretary of the Treasury Scott Bessent, US Trade Representative Jamieson Greer and Senior Counselor to the President for Trade and Manufacturing Peter Navarro to do all the work necessary to deliver reciprocity to the US’ system of trade.
The named officials have until April 1 to create the new reciprocal tariff regime Trump has dubbed the “Fair and Reciprocal Plan,” after which the US will begin imposing reciprocal tariffs.
The senior officials will be examining non-reciprocal trading arrangements and determining an appropriate US tariff for each foreign trading partner.
“For many years, the US has been treated unfairly by other countries, both friend and foe. This system will immediately bring fairness and prosperity back into the previously complex and unfair system of trade. America has helped many countries throughout the years, at great financial cost,” Trump said in his Truth Social post.
“It is now time that these countries remember this and treat us fairly — a level playing field for American workers,” the President said.
A White House official told reporters in a conference call that US officials will look first at “the most egregious” examples of non-reciprocal trading arrangements, with a special focus on India, the EU and Japan.
After new tariffs are established, if any nations subsequently reduce their tariffs, the US will respond by reducing its reciprocal tariffs against that same nation, Trump said.
In his Truth Social post, the President explained how he views non-tariff costs and barriers.
“For purposes of this United States Policy, we will consider countries that use the VAT system, which is far more punitive than a tariff, to be similar to that of a tariff,” Trump said.
“Sending merchandise, product, or anything by any other name through another country, for purposes of unfairly harming America, will not be accepted,” he said. “In addition, we will make provision for subsidies provided by countries in order to take economic advantage of the United States.”
“Likewise, provisions will be made for nonmonetary tariffs and trade barriers that some countries charge in order to keep our product out of their domain or, if they do not even let US businesses operate,” Trump said.
“We are able to accurately determine the cost of these nonmonetary trade barriers. It is fair to all, no other country can complain,” he added.
Manufacturers also have the option of relocating to the US, where they would face no tariffs, the President said.
Trump also said he will be imposing tariffs on imported automobiles, pharmaceuticals and semiconductors in the coming months.
The President defended the Section 232 tariffs he imposed on steel and aluminium imports in his first administration and his recent move to restore 25% tariffs on Canada and Mexico.
“If I didn’t do the tariffs in my first term, you wouldn’t have one steel company here — they’re going to be thriving. You’re going to want to buy those steel companies like crazy,” he said.
“The tariffs have given US Steel a new lease on life,” and now the company can do well on its own without needing to be acquired by Nippon Steel or any other buyer, Trump said during the press conference.

Limited imports support European HRC price recovery
However, according to market participants, the current positive trend in the European HRC market is not so much demand-driven but related to the lack of strong competition from imports.
The latest steel safeguard review of the European Commission, launched in December, sparked uncertainty among local buyers, decreasing their appetite to purchase imported HRC. Thus, European customers started to rely more on domestic production.
Fastmarkets calculated its daily steel hot-rolled coil index domestic, exw Northern Europe at €603.33 ($625.74) per tonne on Thursday, up by €0.83 per tonne from €602.50 per tonne on Wednesday.
The Northern European index was up by €3.33 per tonne week on week and by €30.83 per tonne month on month.
One leading European mill has started offering April-May delivery HRC at €660 per tonne ex-works or delivered, depending on the destination, since last week, Fastmarkets understands.
Other mills in Northern Europe were heard offering HRC for delivery in the second quarter of the year at €610-630 per tonne ex-works.
Some transactions were reported at €600 per tonne ex-works, industry sources told Fastmarkets.
Buyers estimated the workable market level for HRC in Northern Europe at €595-605 per tonne ex-works.
Meanwhile, in Southern Europe, Fastmarkets’ corresponding daily steel hot-rolled coil index domestic, exw Italy was calculated at €593.57 per tonne on Thursday, up by €0.24 per tonne from €593.33 per tonne on Wednesday.
The index was down by €0.18 per tonne week on week and up by €28.57 per tonne month on month.
Local suppliers were heard offering April-delivery HRC at €600-630 per tonne delivered, which would net back to €590-620 per tonne ex-works.
One European supplier was offering HRC with second-quarter lead times to Italy at €660 per tonne delivered, which would be equivalent to €650 per tonne ex-works, Fastmarkets understands. According to industry sources, discounts of €10-20 per tonne were possible.
Buyers’ estimates for the workable market level for HRC in Italy were at €590-600 per tonne ex-works, with the upper end of the price range considered challenging for local customers.
“[Levels at] € 600 per tonne ex-works [are still] a problem for the buyers at this stage because the downstream market is not [performing] great, but apparently there are no alternatives,” a buyer source based in Italy told Fastmarkets.
In terms of imports, no fresh offers or deals were heard in the European market.

China’s steel, aluminum markets remain unfazed by Trump’s tariffs
China’s steel and aluminum markets have shown resilience in the face of the 25% tariffs imposed by US President Donald Trump, indicating that such a move is not expected to adversely impact the two industries in the short term.
China already faces a 25% tariff on its steel exports, which has blocked most Chinese steel from the US market. Broader trade investigations into China’s aluminum exports have also reduced shipments to the US since 2018.

China’s steel exports are likely to remain strong, at least in the first half of 2025, market participants said during the week of Feb. 11.
Any tariff escalation typically would create greater uncertainty in global trade policies, pressuring the growth of China’s manufactured goods.
Infrastructure
China’s steel markets are more prone to trade barriers as domestic consumption remains under pressure due to property sector woes since 2021. Robust exports were the crucial driver behind the manufacturing growth.

China exported about 892,000 mt of finished steel to the US in 2024, up 5.5% year over year, but accounting for only 0.8% of China’s total steel exports, data from research firm CEIC showed.
In 2024, the total retail sales of China’s consumer goods increased 3.5% year over year to Yuan 48.79 trillion ($6.72 billion), slowing from a 7.2% growth in 2023, NBS data showed.
China’s steel consumption by key sectors such as machinery and vehicles rose 2.3% year over year to 309 million mt in 2024, according to S&P Global Commodity Insights data.
China’s exports of manufactured goods are seen strong in the first quarter of 2025, market sources said.
Exports of aluminum products are expected to see limited impact, as shipments to the US have significantly declined since 2018 due to trade investigations, market sources said.
Trade flows
Over January-November 2024, China exported about 812,786 mt of finished steel to the US, up 5.1% year over year, according to the customs data
The export value in dollar terms of China’s mechanical and electrical products, the most steel-intensive manufacturing sector, increased 7.5% year over year to $2.125 trillion in 2024, customs data showed.
In December alone, the export value in dollar terms of China’s mechanical and electrical products increased 12.3% year over year to $119.107 billion, led by a rush to ship goods before tariffs hit China.
The US was China’s largest export destination for aluminum products in 2017, according to customs data.
China exported 259,412 mt of aluminum products to the US in 2024, accounting for 4.1% of China’s total aluminum products exports, according to state-owned research agency Antaike.
Prices
As China’s steel demand slowed faster than its output in 2024, the domestic hot-rolled coil and rebar prices averaged Yuan 3,648/mt ($502/mt) and Yuan 3,519/mt in 2024, down 8.9% and 10.8% year over year, respectively, according to Commodity Insights data.
A robust demand from the electric vehicle and photovoltaic sectors, slower output growth and support from production costs kept China’s aluminum prices elevated in 2024.
The closing price of the most active aluminum contract on the Shanghai Futures Exchange averaged Yuan 19,909/mt ($2,724/mt) in 2024, up 6.5% from a year earlier, exchange data showed.


EUROFER: CBAM simplification and effectiveness must go hand in hand
Improvements are urgently needed to enable steel decarbonisation investments in Europe.
Following the conference “A Carbon Border Adjustment Mechanism for Climate – Addressing carbon leakage to strengthen global climate action”, organised in Paris by the European Commission and the French Ministries of Finance, Economics and Climate Transition, EUROFER emphasises that simplification must go hand in hand with ensuring the instrument’s effectiveness. This means addressing key issues such as resource shuffling, exports, and the inclusions of products further down the value chain.
Alarmingly, during the conference, the Commission announced that legislative proposals on crucial aspects of the Carbon Border Adjustment Mechanism (CBAM), including exports provisions and coverage of downstream sectors, will only be presented at the beginning of next year. Furthermore, a top priority for securing steel decarbonisation investments in Europe – which is tackling resource shuffling – is currently not event listed in the Commission’s planning of upcoming legislative proposals.
This situation contradicts the clear political guidance and sense of urgency expressed by both French Ministries during the conference, and supported by other member states.
EUROFER is concerned about the differing timelines allocated to the simplification and effectiveness of CBAM. While the Commission is fast-tracking simplification through the Omnibus Package, the European steel industry remains deeply worried about the lack of urgency in ensuring CBAM’s effectiveness.
This year’s review of CBAM is critical to achieving both objectives. To ensure its effectiveness, a watertight design is needed. This urgently requires major improvements, including:
- Introducing a structural legislative solution to the very high risk of resource shuffling;
- Introducing a structural solution to preserve European exports, thus avoiding carbon leakage on global markets;
- Extending the CBAM’s scope to steel-intensive downstream products.
Additionally, other design elements – such as stringent default values and the free allocation adjustment – must uphold the mechanism’s environmental integrity.
If these adjustments are not implemented this year, the combination of CBAM and the scheduled phase-out of free allocation will fail to provide adequate protection against carbon leakage. This could further incentivise the relocation of production to third countries, negatively impacting both steel and downstream sectors.
While pursuing the effectiveness and environmental integrity of the mechanism, the administrative burden on operators should be minimised through simpler and streamlined procedures. The Commission has already planned certain simplifications as part of the Omnibus revision. In particular, a revision of the current de minimis threshold of €150 could be an appropriate adjustment to avoid unnecessary reporting for small consignments. Furthermore, CBAM reporting obligations should not apply to European products exported outside the EU, processed abroad, and subsequently reimported into the EU as CBAM goods. Effective monitoring should prevent such provisions from favouring circumvention practices.
In line with these recommendations, a more effective yet simpler CBAM is both possible and urgently needed. Launching it without the necessary improvements would further erode the competitiveness of the European steel industry. This is indispensable given that the EU carbon price has reached approximately 80€/t, while over 25 million tonnes of steel – equivalent to around 20% of EU production – are imported annually from third countries without any carbon cost.

US steel-consuming manufacturers expect ‘harm’ from Trump tariffs
Downstream US manufacturers and other steel consumers are mostly decrying President Donald Trump’s imposition of widespread tariffs, Kallanish detects.
The Coalition of American Metal Manufacturers and Users (Cammu) bluntly states that the broader application of Section 232 tariffs, with no obvious exceptions, increases costs at US factories, pinches supply of basic materials and harms US competitiveness.
“Re-imposing 25% tariffs on steel and aluminum imports from our allies and without a workable exclusion process puts US manufacturers directly in harm’s way,” Cammu writes in a statement.
“For the past six years, Section 232 tariffs have driven up steel and aluminum prices, even for manufacturers sourcing domestically,” the coalition explains. “Lead times for these critical materials have also increased. As a result, US manufacturers are paying significantly more for steel and aluminum than their global competitors, undermining their ability to compete.”
Even American conservative allies of the Republican party agree on the net negative of relying on tariffs to achieve broad policy goals.
“We have far more steel- and aluminum-consuming businesses (think construction, machinery and equipment manufacturing, auto manufacturing) than we do steel and aluminum producers, so the advantage created for the producers comes at a much greater cost to downstream users,” comments Erica York, a vice president at the Tax Foundation.
Analysts at the Economic Policy Institute argue that “tariffs cannot and should not be the centerpiece of a national economic strategy.” The inevitable trade war and currency exchange aberrations are particularly harmful to US manufacturers selling into overseas markets. Metals and minerals are among the upstream items exposing domestic manufacturers to a deterioration in efficient supply chains and an escalation of costs.
“Many US exports use imports as intermediate inputs to final goods produced in the United States,” the policy institute explains. “Making these inputs more expensive with tariffs will boost the price of these US exports and make them less competitive in global markets. Second, trading partners are highly likely to retaliate to US tariffs with tariffs of their own, making exports more expensive in international markets, which we’ve seen on ‘Made in America’ goods from Boeing airplanes to Kentucky bourbon.”
US automakers are already complaining that the tariff threats are causing chaos, higher cost projections and an inability to have confidence in business plans (see separate story).
With reciprocal tariffs likely to make US exports less competitive, overseas customers already “are shifting their supply chains away from US producers,” Cammu argues. The lost business often does not come back.
“Small and medium-sized businesses are particularly vulnerable, losing contracts to overseas rivals with unrestricted access to these essential inputs,” Cammu adds. “Downstream suppliers often cannot choose where they receive their steel and aluminum inputs.”
Not all US-based steel consumers agree with the premise. Some have specific situations in which Trump’s tariff policies are expected to be beneficial. One is Lowell Iron & Steel in Massachusetts, a 146-year-old fabricator of steel structures.
“The tariffs, thank God they’re coming,” Lowell president Dennis Scanell proclaims in a pro-tariff document released by the White House this week. “Maybe this evens the playing field for us. … There’s no way we can compete with Canada.”
Singlehandedly, the tariff strategy has the potential to cancel out multiple other policies from the new president that had been viewed as positive.
“This trade war threatens manufacturing jobs that have benefited from other pro-manufacturing policies enacted by the Trump administration,” Cammu argues. “Expansion plans will stall, and companies will face tough decisions regarding technology investments, workforce retention and long-term growth.”
Dom Yanchunas USA
Trump tariff ‘chaos’ inflicts pain on US automakers
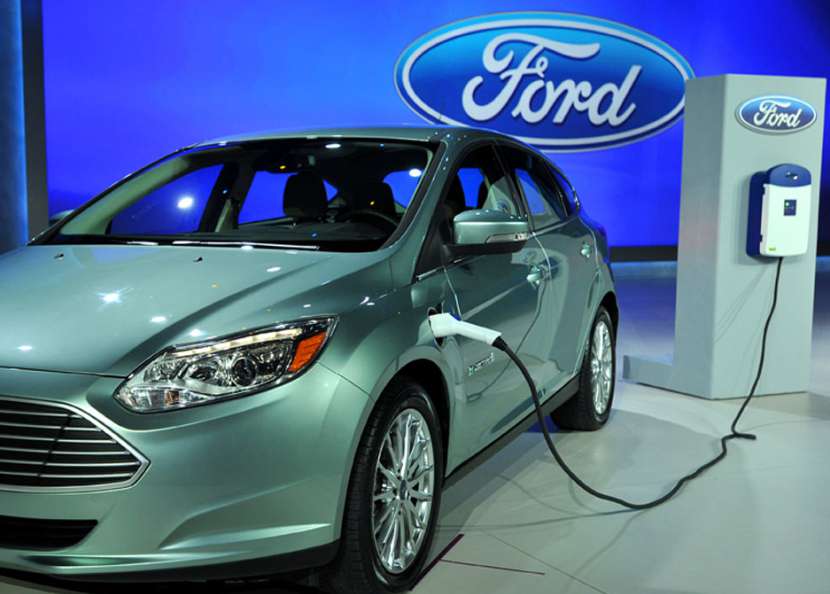
US President Donald Trump’s executive order calling for 25% tariffs on steel and aluminium imports has his domestic auto industry scrambling to reassess operations, Kallanish reports.
At an auto conference on Tuesday, Ford Motor chief executive Jim Farley explained that the introduction of the tariffs is causing the automaker cost-prohibitive operational disruptions.
“There may even be a speculative part of the market where prices come up because the tariffs are even rumoured,” Farley said. “So we’ll have to deal with it. That’s what I’m talking about with cost and chaos. It’s a little here, a little there, a couple weeks or a couple of months of vehicles crossing the border, components crossing the border, that’s going to be a tariff. This is what we’re dealing with right now.”
Sherry House, Ford’s chief financial officer, addressed the challenges facing business planning.
Ford executives are working “to protect our flow and to protect our customers. But generally speaking, we’re not making a lot of large decisions at this point. We’re waiting to see the impact of what’s going to happen. Right now, we’re paused on a lot of the Mexico and Canada tariffs,” House said.
At the same conference, General Motors ceo Mary Barra said the automaker is in the midst of preparing for various risks.
“We started doing scenario planning and looking at what are the different things we can change, we can move. We are prepared when we know exactly what’s going to happen. We know the steps we can take and we think we can mitigate 30% to 50% of tariffs without deploying capital. If tariffs are longer, there’s additional things that we’ve studied that we know we can do from a capital-efficient way,” Barra said.
A former US auto executive tells Kallanish that the race against China for global electric vehicle (EV) market share is now endangered by the challenges the 25% tariff poses to the industry as well as changes the Trump administration may pursue with the Inflation Reduction Act (IRA).
“This couldn’t come at a worse time. China is a threat to all manufacturers. Their global dominance in the EV market is enormous, and it will take years for ‘The Big Three’ to catch up. Taking Trump’s intentions to eliminate the IRA EV incentives into account, China will gain further advantages and jeopardise the transition plans for Ford and GM. The confusion caused by any tariff war will magnify the challenge and disrupt all short-term and long-term plans,” states the former auto executive.
According to that same source, all automobile prices will likely rise in the US.
“Tariffs of 25% on steel and aluminium would be costly since a typical vehicle contains about 1,000 lbs of steel and aluminium. It’s difficult to estimate the effects on consumer prices. By some estimates, it could be as much as $1,500. At some point, manufacturers would have to increase prices. When and if tariffs are eased, prices will probably not come down, or if they do, it will be in the form of short-term incentives and gradual price adjustments. Remember, prices tend to rise much faster than they decline,” says the executive.
The Michigan-based automotive advocacy group MichAuto issued a statement regarding the tariffs lodged against Canada and Mexico, suggesting that maybe it would be better to adjust the framework of the existing Uniited States-Mexico-Canada Agreement (USMCA).
“While the administration works to stem the flow of illicit drugs and illegal immigration, this should exclude the use of punitive tariffs, which are counterproductive to commerce. MichAuto urges that the proven tools at hand such as the reopening of the USMCA and the direct input and involvement of our vital industry be utilised in a manner that does not stymie commerce and negatively impact companies and the consumer, but rather works toward solutions that preserve our strong trade partnerships and protect American jobs,” states Glenn Stevens, executive director of MichAuto.
Kristen DiLandro USA

ArcelorMittal considers transferring certain European activities to India
ArcelorMittal is evaluating the potential relocation of specific European support functions to India as part of a strategic initiative to consolidate certain operations in that region.
The group has provided assurances that there will be no relocation of European production activities to India.
“As discussed on 11 February 2025, at a meeting with the European Works Council, ArcelorMittal Europe is exploring opportunities to optimise its business processes, to provide centralised and cost-effective services for the Europe segment…The steel industry in Europe is facing several major challenges which are threatening the future of steelmaking on the continent. ArcelorMittal Europe is therefore working hard to respond to these challenges, including a focus on further reducing operating costs not directly related to steel production,” it says in a note obtained by Kallanish.
“A number of initiatives have already been implemented across our businesses in response to the challenges facing the steel industry. The initiative discussed today is to study the possibility of further centralising certain business support activities, by extending our business services hub to carry out some of these activities in India. The initiative is one element of the company’s response to the crisis and would bring the company in line with the approach being adopted by companies in a broad range of industries,” it added.
Elsewhere, the company says it plans to monitor various developments in 2025 before reaching a conclusive decision on the feasibility of its decarbonisation investments in Europe.
These developments include the planned review of the Carbon Border Adjustment Mechanism (CBAM), a forthcoming assessment of EU steel safeguards, and the release of the Steel and Metals Action Plan.
Upon completion, these initiatives will establish the parameters ArcelorMittal will use to formulate the business case for decarbonisation investments in Europe.
The steelmaker said last year it is suspending decarbonisation investments at its Dunkirk facility in northern France due to the downturn in the global steel industry.
The company has not disclosed any details regarding the progress of its sustainability investments at Gent or Dunkirk. However, it has shared an update on its decarbonisation investment in Spain, where engineering works are ongoing for the construction of a 1.1 million tonne EAF at its long products facility in Gijón (see Kallanish passim).
Natalia Capra France

Weak demand depresses tube output in EU
According to the Economic and Steel Market Outlook 2025-2026/Q1 2025 Report from the Economic Committee of the European Steel Association (EUROFER), in the third quarter of this year the output of the EU steel tube industry declined by 3.3 percent year on year, after a 3.4 percent decrease in the previous quarter.
According to the EUROFER report, in the longer term, demand for large welded tubes from the oil and gas sector is not expected to improve substantially as the EU has accelerated its transition towards LNG shipping for its energy needs, thereby reducing its reliance on gas transported via pipelines. Oil demand is expected to keep declining throughout the rest of 2024 in the EU, aligning with low economic growth expectations.
EUROFER stated that production in the EU steel tube sector is expected to decrease by three percent in 2024. As for 2025, tube output is forecast to grow by 0.3 percent year on year.
