


EU plans ‘firm’ countermeasures following US agreement termination
The US imposition of blanket 25% steel import tariffs will also involve the termination effective 12 March of exemption and duty-free quota agreements with trading partners such as Brazil and the EU. The latter says it plans to implement “firm” countermeasures.
The temporary duty exemption for Ukraine will also be terminated from 12 March, Kallanish notes.
The tariffs were announced officially late on Monday.
In a statement, the White House says the “benefits of this temporary [Ukraine] exemption have accrued primarily to producers in EU member countries, which have significantly increased duty-free exports to the US market of steel articles processed from Ukrainian semi-finished steel.”
Since 2021, imports from Ukraine have remained steady at 0.5% of total US imports, while imports from the EU have increased to 14.8%, it adds.
Ukraine has seen its two largest steelworks, Azovstal and Ilyich, taken out of action due to Russia’s invasion. To compensate, main domestic steelmaker Metinvest has been rolling semi-finished steel at its EU facilities in Italy and Bulgaria.
European Commission President Ursula von der Leyen responded by saying she “deeply regrets” the US tariff imposition. “Unjustified tariffs on the EU will not go unanswered – they will trigger firm and proportionate countermeasures,” she notes. “The EU will act to safeguard its economic interests. We will protect our workers, businesses and consumers.”
European steelmakers’ association Eurofer meanwhile says the EU could lose up to 3.7 million tonnes of steel exports to the US as a result of exemptions and quotas being removed (see separate story). Despite these exemptions, EU steel imports into the US decreased by over 1m t/year, the association adds.
The EU exported 3.413mt of HS chapter 72 iron and steel products – which include scrap – to the US in January-November 2024, exceeding the full-year 2023 total of 3.399mt, according to Eurostat. Except for the Covid and Covid rebound years of 2020 and 2021, annual shipments since 2019 have hovered at around 3.4mt and saw no significant impact from the duty free quota agreement, effective 1 January 2022.
Downstream steel derivative products, except those processed from steel articles that were melted and poured in the US, will also be subject to a 25% import duty in the US. For any derivative article not under chapter 73, the duty will apply only to the steel content of the article. The importer must provide customs with any information necessary to identify the steel content used.
Imports of products such as fabricated structural steel and prestressed concrete strand have increased significantly, eroding the US domestic industry’s customer base, the White House notice claims.
Adam Smith Poland


IREPAS Short Range Outlook : February 2025
Global longs market under very strong pressure from Chinese exports, Trump 2.0 brings uncertainty and volatility
The global long steel products market is currently under very strong pressure mainly because of Chinese exports, which have been increasing and not showing any signs of slowing down. We have already seen what Trump 2.0 means – uncertainty, volatility and a lack of visibility. It seems like the situation will get even worse until the dust settles and his goals are clearly understood. So far, Trump’s announcements have given rise to concerns about inflation, which will slow down interest rate cuts.
US long steel and construction segments waiting for the dust to settle
The market in the US has entered a waiting period in terms of the outcome of some of the decisions already made by the White House and others under consideration and delayed for further negotiations. New infrastructure projects are on hold, amid the government freeze on spending. Interest rates have not come down and there is no clear sign for the near future, thus delaying many projects and also purchases by would-be home buyers. Labor shortages in the construction sector are becoming a near certainty, causing delays and higher costs for construction developments. Domestic rebar producers are reluctant to increase prices for another 30 days, until there is certainty regarding the duties on Mexico. They are generally competing with each other rather than with imports, which are very light.
All eyes still on China
On the other hand, the real determining factor for rest of the world other than the US is China, simply because the US is now a separate world for the global steel market. We all need to wait and see what China’s policy in the current year will be: will they continue with steel exports of over 100 million mt or will they slow down to help the global market to stabilize?
EU mills locked in cycle of low demand and high costs
The EU steel market is suffering from continuing low demand for long products, with European mills locked in a cycle of poor demand and high costs. The construction market in most EU countries is still very slow due to seasonal reasons but also in general due to much less demand from investors. In this context, the merger of Badische and Van Merksteijn will certainly have an impact in terms of consolidation. Meanwhile, energy prices in Europe are once again at levels not seen since 2022. The cold winter and the shortage of base load in Germany have pushed electricity and gas prices to their highest levels of the last three years, at least until the end of spring. These higher costs will force long steel producers in the EU to increase prices and to shut down more capacities in 2025. Feralpi seemed to have stopped production completely in January, while Riva Germany officially announced shutdowns to run from January 1 to March 30.
EU’s long steel import quotas quickly exhausted at start of year
The EU’s import quota for “all other countries” was exhausted on day two or three at the start of the year, with the huge volumes which were imported by Bulgaria and Romania. This means there will not be more imports from “all other countries”. Turkey and Algeria are mostly not competitive enough to attract EU importers. The price increases announced by German and Italian mills have not yet been accepted by the market but they probably will be as soon as benders have to restock, especially given the current euro/US dollar exchange rate. The very strong US dollar is another factor keeping prices low in the international market.
Protectionism is the new magic word, consumers to lose out
Protectionism seems to be the new magic word for economies worldwide. The markets are running into a spiral of protectionism in which everybody will lose out, especially the middle-class consumers and industries.
Longs mills forced to cut outputs, low profits make environmental targets unattainable
Mills in the long steel products market are forced to lower their capacity utilization rates, which will negatively affect their cost of production. There is a chain reaction of displaced export capacities due to Chinese exports. The steel industry is also suffering from a lack of profits, that makes it impossible to achieve net zero commitments.
Current market very difficult to operate in, outlook very unpredictable and unstable
Under these circumstances, the current status of the market can be described as unstable and very difficult to operate in. The outlook for the next quarter is very unpredictable and unstable.

HRC prices in Europe hold steady; buyers cautious
The week before, ArcelorMittal announced a price increase of €30 ($31) per tonne for April/May-delivery HRC across Europe, with offers now reaching €660 per tonne ex-works or delivered, depending on the destination.
But other mills in Northern Europe refrained from following the move, keeping their offers for the second quarter of 2025 at €620-630 per tonne ex-works, industry sources told Fastmarkets.
However, buyers were cautious, and the traded volumes were limited, Fastmarkets understands.
“Final customers and stockholders still do not undertake a large-scale restocking. They wait to see how the market would develop,” a buyer source based in Northern Europe told Fastmarkets.
Buyers’ estimations for the workable market level were at €590-600 per tonne ex-works.
Fastmarkets calculated its daily steel hot-rolled coil index domestic, exw Northern Europe at €598.75 per tonne on Monday, down by just €0.42 per tonne from €599.17 per tonne on Friday February 7.
The Northern European index was up by €7.50 per tonne week on week and by €33.33 per tonne month on month.
Meanwhile, in Southern Europe, Fastmarkets’ corresponding daily steel hot-rolled coil index, domestic, exw Italy was €592.50 per tonne on Monday, unchanged from the previous calculation on Friday.
The index was up by €5.00 per tonne week on week and by €30.00 per tonne month on month.
The latest offers of April-delivery HRC in Italy were heard at €600-610 per tonne delivered, which would net back to €590-600 per tonne ex-works.
Buyers estimated the workable market level at €580-600 per tonne ex-works on Monday.
However, no major deals with HRC were heard in the Italian market.
Italian customers were well-stocked and were not in a hurry to buy new material, industry sources told Fastmarkets.
The market of imported HRC was also quiet on Monday due to trade risks related to the current steel safeguard review, which was expected to be over by the end of March.
Taiwan and Indonesia were heard offering March-shipment HRC at €560-570 per tonne CFR to Italy. Offers from South Korea were reported at €580 per tonne CFR.
HRC from Turkey was on offer to Italy at €590 per tonne CFR, including the anti-dumping duty, industry sources told Fastmarkets.


UK Steel calls Trump’s tariff proposal ‘deeply disappointing’
Industry association UK Steel says it is “deeply disappointing” that US President Donald Trump is targeting the UK with an additional 25% tariff on steel imports, Kallanish notes from its statement.
It remains unclear whether this will cancel all or some of the previous arrangements on existing Section 232 measures, the association adds. Until now, customers in the US could also apply for product-specific exemptions for tariff-free imports of products not made in the US.
UK Steel director general Gareth Stace says: “It is deeply disappointing if President Trump sees the need to target UK steel, given our relatively small production volumes compared to major steel nations. The UK produces world-leading steel, supplying the US with high-quality products for defence, aerospace, stainless, and other critical sectors, materials that simply cannot be replicated elsewhere.”
The association also notes fears of excess steel capacity being re-directed to other markets such as the UK. Without strong trade shields, unfairly priced imports could undermine domestic steelmakers and threaten the long-term viability of the industry, it adds.
“The imposition of US tariffs on UK steel would be a devastating blow to our industry. The US is our second largest export market after the EU. At a time of shrinking demand and high costs, rising protectionism globally, particularly in the US, will stifle our exports and damage over £400 million [$496m] worth of the steel sector’s contribution to the UK’s balance of trade,” Stace says.
“At the same time, the introduction of further US tariffs will inevitably divert global trade flows, with excess steel potentially redirected to the UK market. This reinforces the urgent need for watertight UK trade measures in 2026 to prevent surges in imports following the UK’s steel safeguards expiry. Accelerating the UK’s CBAM to 2026 would provide an additional layer of protection against unfairly priced steel. The UK Government must act decisively to shield our domestic industry from the fallout of rising global protectionism,” Stace concludes.
Carrie Bone UK

Talent management, specialisation essential, argues service centre
When reconsidering their corporate strategies, small and medium-sized companies (SMEs) in the steel sector ought to take talent management into account, as well as specialisation and sustainability reporting, says 247TailorSteel.
The Dutch-German service centre group has compiled an article of recommendations for its customers in which it addresses metals industry trends for 2025. As one of the key themes, it emphasises that specialisation is becoming ever more important. “Create a clear advantage for yourself against the mass producers, which can deliver big volumes, but do not offer specialised knowledge and tailored solutions,” Kallanish reads in the article.
Given that a shortage of skilled personnel has become a key issue for the German economy, 247TailorSteel advises SMEs to contact technical colleges to identify potential newcomers at an early stage. Also, vocational training of existing staff is essential to keep them updated and motivated in their work.
The group also touches the aspects of reshoring of overseas sites to the home country, in the interest of shorter transport times, lower transport costs, and fewer emissions caused by transport.
Speaking of emissions, the article notes that one bitter pill cannot be averted: reporting obligations in the interest of the Emission Trading System (ETS) and the Corporate Sustainability Reporting Directive (CSRD). “All this will cost your time as well as financial resources. But as unpleasant as it is, you need to face that task,” 247TailorSteel writes.
Christian Koehl Germany

Trump officially imposes 25% tariffs on steel, aluminium
US President Donald Trump has officially issued a blanket 25% tariff on all steel and aluminium imports to the US, Kallanish reports.
The president signed an executive order creating the tariff on Monday night. The move was expected after Trump mentioned it informally on Sunday whilst travelling to the Super Bowl football game.
“It’s a big deal,” Trump said Monday in the Oval Office. “This is the beginning of making America rich again.”
Currently, the US has postponed the 25% tariff it planned to enact against Canada and Mexico.
Kristen DiLandro USA
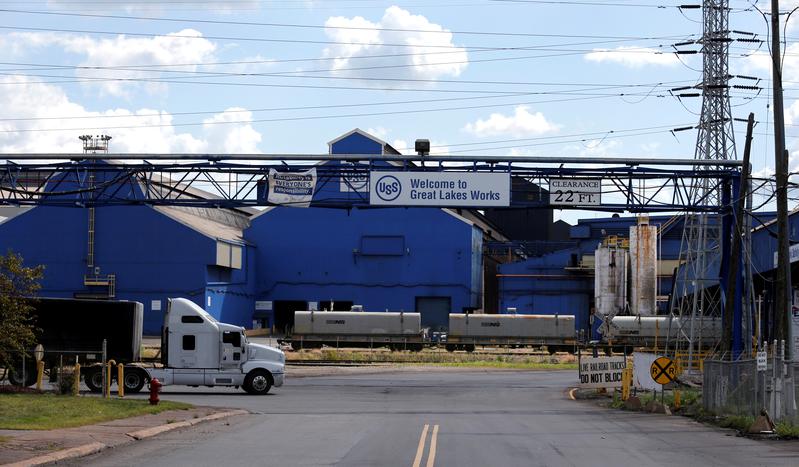
Nippon Steel to ‘heavily invest’ in US Steel rather than acquire it: Donald Trump
Trump said the agreement will preserve American ownership of US Steel and will help the iconic company benefit from Japan’s steelmaking expertise.
“US Steel is a very important company to us. It was the greatest company in the world… 80 years ago, and we don’t want to see that leave. It wouldn’t actually leave, but the concept, psychologically, not good,” Trump said.
“They’ve agreed to invest heavily in US Steel as opposed to own it, and that’s very exciting,” he added.
Prime Minister Ishiba said Japan will invest $1 trillion in the US but provided no indication of how much Nippon Steel might invest in US Steel.
“They’re doing it as an investment, no longer a purchase. I didn’t want it bought, but investment I love,” Trump said.
“And we’ll meet with the head of [Nippon Steel] next week, a very great company, and they’ll work out the details and I’ll be there to help mediate and arbitrate,” Trump said.
LNG shipments
As part of the agreement between the US and Japan, President Trump pledged to begin shipments of liquefied natural gas (LNG) via a new pipeline in Alaska, a move he touted for also being able to bring trade between the two nations closer to an equal balance and away from Japan’s long-standing trade surplus.
The 807-mile proposed pipeline Alaska LNG would connect natural gas reserves in Northern Alaska to Nikiski for export, according to project developer Alaska Gasline Development Corporation (AGDC).
Assuming a standard 0.5-inch wall for the 42-inch line pipe specified for the 807-mile line, that means the line would consume about 472,577 short tons of steel.
Fastmarkets last assessed equivalent product steel ERW line pipe (X52), fob mill US at $1,250-1,300 per short ton on January 8.
The total steel value of the line, then, could range around $590 million-614 million.
Trump issued an executive order on January 20 requiring the federal government to prioritize the development of the Alaska LNG pipeline.
“Alaska LNG will annually strengthen the US balance of trade by approximately $10 billion, create thousands of jobs, and eliminate up to 2.3 billion tons of carbon emissions over the project’s 30-year authorization,” AGDC president Frank Richards said after the order was issued.
Market chatter
A steel distributor supported Nippon Steel’s potential investment as a positive for the company and the US.
“I have no doubt that Nippon is committed to making US Steel a success. They definitely need all that Nippon has to offer,” the distributor said.
“It’s unfortunate that a foreign entity needs to be the one that [invests in] US Steel, but if that’s the only offer, it needs to be allowed so they can be a continuing company,” they added.
Nippon Steel’s investment in US Steel is by no means a sure thing, the distributor said.
“Trump being the businessman and dealmaker, he may be able to get a couple [American] steel companies interested and broker a deal to have them buy US Steel instead,” they said.
United Steelworkers (USW) union president David McCall issued a statement reiterating opposition to any Nippon Steel investment in US Steel.
“While we await the details of the proposed investment, we encourage President Trump to continue safeguarding the long-term future of the domestic steel industry by instead seeking American alternatives,” USW stated.
Nippon Steel’s proposed $15 billion acquisition of US Steel was blocked by former President Joe Biden due to national security concerns in January, and the Committee on Foreign Investment in the United States ruled that the order blocking the deal would not be effective until June 18 to give Japan a chance to appeal it in court.
Alesha Alkaff in Boulder, Colorado, contributed to this story.
EU industry cautious over rebound, awaits policy rescue
Big European steel industry names have offered a glimmer of hope for the demand outlook in recent days, but tempered expectations for 2025, Kallanish notes. In any case, the industry’s health will depend heavily on anticipated European Commission measures.
ArcelorMittal said it expects higher apparent demand on-year in 2025 amid low inventory levels, especially in Europe. The group’s expectation of restocking throughout 2024 did not materialise, however. Chief executive Aditya Mittal also cautioned that EU measures to support industry will be critical this year. The European Commission is due to publish its Clean Industrial Deal later in February. A specific action plan for the steel industry is also eagerly being awaited.
European steelmakers’ association Eurofer said the Commission initiatives “will determine the future of the EU steel industry”.
ArcelorMittal’s European operations saw sales and Ebitda drop 5% and 18% respectively on-year in 2024 to $29.95 billion and $1.62 billion, despite a 4% rise in steel shipments to 28.66 million tonnes, driven by flat products.
Eurofer said EU apparent steel demand should recover 2.2% in 2025 but only provided the industrial outlook improves and global tensions ease. This is also down from its forecast in October of a 3.8% rebound this year. The firm steadily revised down its 2024 demand growth projection throughout last year.
Economic uncertainty will continue to take its toll in the coming quarters despite monetary easing by the European Central Bank, it added. Energy prices, weak manufacturing and geopolitical tensions continue to weigh on activity.
US Steel, which owns the major flat steelworks in Kosice, said it expects slightly improved results in Europe in the first quarter, but pressure will remain from challenging pricing and demand conditions.
Tata Steel, which owns the IJmuiden and Port Talbot steelworks, pointed out that despite the European Central Bank reducing interest rates significantly, concerns persist about inflation and energy costs in Europe.
Adam Smith Poland

Steel becomes object of politics in Germany
Chancellor Olaf Scholz of the Social Democrats (SPD) has paid a visit to thyssenkrupp Steel in Duisburg, shortly before German voters are called upon to elect a new national government.
The visit is seen as a reaction to earlier remarks by Scholz’s adversary, Friedrich Merz, which were interpreted as a dismissal of the idea of “green” steel. Merz, the Christian Democrats (CDU)’s candidate for chancellor, questioned the economic feasibility of the energy transition in view of a lack of affordable energy. He was attacked by several political commentators and subsequently clarified he was not questioning the transition in general.
“Following the doubts expressed by Friedrich Merz … Olaf Scholz found clear words in Duisburg for the future of steel in Germany,” an SPD press release reads. Scholz was cited as saying that “the transition must be enforced, [so that the industry is enabled] to deliver [a new steel product] in time.”
While most of Scholz’s statements were foreseeable, reiterating positions expressed earlier, one tangible detail concerned framework conditions that must be improved. Scholz declared that electricity grid fees – the factor most hurting manufacturing industries in Germany – must be capped, and that this is part of SPD’s programme. The party notes that the visit took place following an invitation from tk Steel’s works council – a detail not mentioned in the company’s official press release about the visit.
In subsequent commentaries in the German press, the visit was largely seen as business as usual in the run-up to elections. One commentator quipped that Scholz “is positioning himself as a steel chancellor, although he was not much of one during his years in office.”
Christian Koehl Germany

Trump will impose 25% tariffs on Steel and Aluminum
The US president said he planned sweeping tariffs on all steel and aluminum imports on Monday and would take other action to even out tariff rates with the rest of the world later this week.
Donald Trump has said he will announce new 25% tariffs on all steel and aluminum imports into the US on Monday that would affect “everybody’, including its largest trading partners Canada and Mexico, in another major escalation of his trade policy overhaul.
Trump’s pre-announcement came as China’s retaliatory tariffs, announced last week, came into effect. The measures target $14bn worth of products with a 15% tariff on coal and LNG, and 10% on crude oil, farm equipment and some vehicles.
The US president, speaking to reporters on Air Force One on Sunday, also said he would announce reciprocal tariffs – raising US tariff rates to match those of trading partners – on Tuesday or Wednesday, which would take effect “almost immediately”. “And very simply, it’s, if they charge us, we charge them,” Trump said of the reciprocal tariff plan.
The move on steel and aluminum brought a swift reaction from Doug Ford, the premier of the Canadian province of Ontario, who accused the US president of “shifting goalposts and constant chaos” that would put the economy at risk.
Monday’s tariffs would come on top of existing metals duties.
Amid wider pushback against Trump’s economic heavy-handedness, French President Emmanuel Macron warned in an interview broadcast on Sunday that he was willing to go “head-to-head” on tariffs with the US president. “I already did so, and I will did (sic) it again.”
Macron told CNN that the EU should not be a “top priority” for the US, saying: “Is the European Union your first problem? No, I don’t think so. Your first problem is China, so you should focus on the first problem.”
Macron said tariffs would harm European economies but also the US, given the level of economic ties. “It means if you put tariffs on a lot of sectors, it will increase the costs and create inflation in the US. Is it what your people want? I’m not so sure,” he said.
He said the EU must be ready to react to US actions, but stressed that the 27-nation bloc should mainly “act for ourselves”. “This is why, for me, the top priority of Europe is competitiveness agenda, is defence and security agenda, is AI ambition, and let’s go fast for ourselves.
“If in the meanwhile, we have [a] tariff issue, we will discuss them and we will fix it.”
Trump has long complained about the EU’s 10% tariffs on auto imports being much higher than the US car rate of 2.5%. He frequently states that Europe “won’t take our cars” but ships millions west across the Atlantic every year.
