


Limited trading in Europe’s steel beams market, prices widen downward slightly
Fastmarkets’ weekly price assessment for steel beams, domestic, delivered Northern Europe, was €760-790 ($823-856) per tonne on Wednesday, widening downward by €10 per tonne from €770-790 per tonne a week earlier.
Similarly, Fastmarkets’ weekly price assessment for steel beams, domestic, delivered Southern Europe, was also €760-790 per tonne on Wednesday, also widening downward by €10 per tonne from €770-790 per tonne a week earlier.
Offers by major producers to the German market were heard at €760 per tonne, while higher prices were estimated in other parts of Europe.
Consumption by the construction sector has been weak across Europe, but Germany has been significantly affected by weak end-user demand and high energy prices. The country’s steel output last year was at its lowest volume since the financial crisis of 2009, according to national steel industry association WV Stahl.
Meanwhile, scrap costs in Turkey’s bellwether market remained firm, following price rises in November and December last year.
Fastmarkets’ calculation of its daily index for steel scrap, HMS 1&2 (80:20 mix), North Europe origin, cfr Turkey, was $413.47 per tonne on Wednesday, up by $5.85 per tonne week on week from $407.62 per tonne.
Published by: Holly Chant


CPL develops ecoke 100%, trials in blast furnaces
CPL Industries has started supplying ecoke 100% and also carried out trials with blast furnace-based steelmakers, the firm informs Kallanish.
The firm’s ecoke 30% product, biocoke that contains a minimum of 30% of renewable biomass, was successfully trialled by Liberty Steel UK in 2022 to replace anthracite as its main source of charge carbon in the Rotherham electric arc furnace.
Since then, “we’ve been on journey to increase the biomass”, CPL chief executive Jason Sutton tells Kallanish. Liberty’s Rotherham plant is now sourcing 100% biomass-containing ecoke. This enables a carbon emissions reduction at that operation of about 30%. The high level of biomass works well for some steelmakers, while others need a higher level of carbon and so have stuck with the 30% product, Sutton explains.
Spanish steelmaker Sidenor, which also trialled ecoke 30% in 2022, has since moved on to commercial use of the product.
CPL successfully completed trials with blast furnace-based steelmakers to replace the nut coke in their burden with ecoke. Although it is not supplying commercially into those facilities, the trials proved ecoke technically succeeded as a nut coke replacement.
The firm is also in talks to agree commercial terms for ecoke supply to a number of stainless steelmakers in Scandinavia as a metallurgical coke replacement.
CPL anticipates increased demand for ecoke will take it to its full capacity of 500,000 tonnes/year and is considering expanding in future.
As for its feedstock, the firm sources biomass products from agricultural residues and a biocarbon element that principally comes from Africa. It does not foresee any supply constraints, but intends to work with partners to ensure sufficient volumes and logistics capabilities, Sutton concludes.
Adam Smith Poland


Hydnum Steel’s Spanish green steel mill project advances
Spain’s Hydnum Steel (HS) says it is advancing with its plan to build the first green steel mill on the Iberian Peninsula, Kallanish notes. The project, a partnership consisting of the Helvella investment company, Siemens, ABEI Energy and Russula Corporation, will be located in Puertollano, in the Castilla-La Mancha region.
“Our priority project application for the plant has been submitted to the Castilla-La Mancha regional government,” the company confirms. “The procedure confirms the justification of its social and economic interest at the regional level, as well as its public utility and strategic nature.”
The recognition of the Puertollano project as a priority guarantees preferential administrative processing and fast-tracks project implementation, especially in matters of land and urban planning. Among other advantages, it implies economic and financial incentive measures.
The green steel plant is designed to use fossil-free energy throughout the manufacturing process and will gradually incorporate green hydrogen into the production process to substantially reduce CO2 emissions.
“Production will be in line with the sustainable development objectives in the steel sector and the circular economy, recycling scrap as raw material, minimising the use of water and valuing the waste and by-products generated during the manufacturing processes,” HS confirms.
The facility will occupy an area of 1.3 million square metres. The project is valued at €1.65 billion ($1.73 billion) and will create more than 1,000 direct jobs. The plant is expected to be operational in 2026.
Todor Kirkov Bulgaria

365 Days of Steel: exploring the endless tapestry of Steel in Construction, Design and Art
The book ‘365 days of steel’ takes readers through the fascinating history of steel in construction, design & art.
Over the past 140 years, architects, engineers, designers and sculptors have exploited the qualities of this unique material in their projects. Strong yet light, sometimes imposing but just as often light-footed, steel offers a designer endless possibilities. From Richard Serra’s sculptures and Charlotte Perriand’s furniture to Daniel Burnham’s first skyscrapers and Calatrava’s elegant bridges: all are wonderful examples of the versatility of steel.
This richly illustrated book invites you on a 365-day journey full of inspiring examples and interesting anecdotes about well-known and lesser-known projects. This book is an asset for anyone who would like to know more about the many reasons why designers have enthusiastically embraced and applied steel.


‘365 days of steel’
Author: Bruno Dursin
The book is the logical consequence of 365 posts on LinkedIn shared from 9 April 2022 to 8 April 2023.
For a year, every day one page on the application of steel in construction, design & art. Each of those examples show the versatility of this wonderful material that offers endless possibilities. I hope readers will be equally fascinated and amazed by how architects, engineers, designers and artists have gone about working with steel.
The book will be out on 8 March 2024 and costs €49 (incl. VAT) + €9.50 postage (within Europe).
where to buy?

CBAM complications, safeguard hinder steel activity: Assofermet
The normative framework of the EU Carbon Border Adjustment Mechanism (CBAM) and safeguards on steel imports is hindering the daily activity of Italian and European steel companies, says Italian steel trade association Assofermet.
The challenges in filling CBAM reports, the economic repercussions expected from the mechanism starting in 2026, as well the safeguard measures in force from 2018 are a deep concern for Assofermet’s many members.
The European Commission (EC)’s Directorate General for Trade and the Directorate General for Taxation and Customs Union asked the association to highlight the critical issues of the mechanism to help with drafting the final version. “It has been assured that our perspective will be taken into account, especially for the future evolution of CBAM … Agreeing that CBAM will also generate increased costs for downstream end-users in the steel supply chain, it was pointed out to the Commission that if certain finished products … are not included in the mechanism, the European industry will lose competitiveness, given its global role,” Assofermet warns in a note sent to Kallanish.
The association notes an open-minded attitude from Italian authorities to listen to the problems of the entire steel supply chain stemming from regulations and willingness to continue dialogue on the regulatory framework. While the first quarterly report deadline for CBAM has passed, the safeguard on steel imports is currently set to expire at the end of June 2024. “There are no official updates yet on a possible extension after the first half of this year,” Assofermet concludes.
31 January was the deadline for importers to submit their first report detailing emissions as part of CBAM. The European Commission nevertheless announced this week that due to a technical incident, it is offering the possibility to request for a 30-day delay for submission (see Kallanish passim).
During the ongoing transitional phase of CBAM, European importers of steel need to file quarterly reports in the European Commission system, starting from those for the fourth quarter of 2023. During the transitional period, importers are required to report on the quantity of imported goods and resulting direct and indirect emissions. No payments will be due. The transitional phase is planned to conclude at the end of 2025.
Natalia Capra France

European HRC prices firm despite slow trading
In Northern Europe, buyers estimated that the achievable price was €750-780 ($813-845) per tonne ex-works for March-April delivery coil.
One source reported a transaction for a small tonnage at €800 per tonne ex-works.
Market participants said the official offer level from integrated steelmakers for April delivery was €800-820 per tonne ex-works, but this could not be widely corroborated in the market.
“[There have been] some sales at €800 [per tonne ex-works], but this is rather an exception, ” a buyer source said. “The vast majority of buyers wouldn’t book anything at this price.”
As a result, Fastmarkets calculated its daily steel hot-rolled coil index, domestic, exw Northern Europe at €760.63 per tonne on January 31, up by €3.75 per tonne from €756.88 per tonne on January 30.
The index was also up by €13.96 per tonne week on week and by €65.13 per tonne month on month.
The major concern remains sluggish end-user demand and market participants are worried that when some steelmaking capacities comes back online in the first quarter, it might put pressure on prices.
“Salzgitter and Tata Steel reignited big blast furnaces in January [and] everyone agrees that the recent price rise [for HRC] was mainly driven by supply tightness,” a distributor source said.
Fastmarkets calculated its daily steel hot-rolled coil index, domestic, exw Italy at €753.75 per tonne on Wednesday, stable day on day.
The index was also up by €15.00 per tonne week on week and by €65.42 per tonne month on month.
Integrated mills in Italy were offering March-delivery HRC at €780 per tonne delivered (around €765-770 per tonne ex-works).
The tradable value for domestic HRC in Italy was said to be around €750-760 per tonne ex-works.
Trading was “on pause,” sources said, because buyers have sufficient stocks and are not hungry for bookings.
“Buyers are well-booked and want to see what happens with prices in February-March,” a seller in Italy said. “At the same time, it is unlikely that [HRC] prices will drop in the short run, because supply remains reduced and importing material is getting increasingly complicated.”
In the secondary market, 4 mm hot-rolled sheet was traded around €840-850 per tonne CPT, compared with €830-850 per tonne CPT seven days ago.
Import offers were reported at €655-680 per tonne CFR from Asia and at around €690 per tonne CFR from India, for March-April shipment.
Turkish mills were offering HRC to Italy at €700-715 per tonne CFR, including the anti-dumping duty.
Published by: Julia Bolotova
US assigns initial AD duties on Italian plate
The US Department of Commerce preliminarily finds that certain Italian carbon and alloy steel cut-to-length plate products were sold in the US below average market value during the period of review from May 2022 through April 2023, Kallanish understands from monitoring the Federal Register.
Commerce also found that one mandatory respondent did not sell the subject merchandise below market value during the period of review. The department preliminarily assigns NLMK Verona SpA a weighted average dumping margin of 2.45% and Officine Tecnosider SRL 0.00%.
The products covered under this antidumping duty order are classified under the following HTSUS subheadings: 7208.40.30.30, 7208.40.30.60, 7208.51.00.30, 7208.51.00.45, 7208.51.00.60, 7208.52.00.00, 7208.53.00.00, 7208.90.00.00, 7210.70.30.00, 7210.90.90.00, 7211.13.00.00, 7211.14.00.30, 7211.14.00.45, 7211.90.00.00, 7212.40.10.00, 7212.40.50.00, 7212.50.00.00, 7225.40.30.50, 7225.40.70.00, 7225.50.60.00, 7225.99.00.90, 7226.91.50.00, 7226.91.70.00, 7226.91.80.00 and 7226.99.00.00.
Kristen DiLandro USA

Europe weakness hits SSAB earnings, foresees shipment growth
Swedish steelmaker SSAB posted lower earnings on-year in 2023 due mainly to the impact of a weaker market and lower prices, especially in Europe, Kallanish notes.
Consolidated revenue declined 7% year-on-year to SEK 119,489 million ($11.48 billion); adjusted operating result was SEK 16,467 million against SEK 29,283 million the year before. While 2022 was a record year for SSAB and most global steelmakers, 2023 was characterised by a weaker market, lower steel prices and higher raw material costs.
The weak market forced SSAB to adjust production, costs and staffing in Europe. These measures are expected to continue to be implemented during the first quarter of 2024, especially in the construction related segments. SSAB’s other European units, such as Tibnor and Ruukki Construction, also implemented cost saving programmes and personnel reductions.
Overall crude steel production at SSAB Europe surpassed 4.3 million tonnes in 2023, some 400,000t above the level registered in 2022. This is due to the fact 2022 output was impacted strongly by the consequences of the war in Ukraine.
For Q1 2024, SSAB expects shipments at the European unit to be somewhat higher than in Q4 2023; nevertheless, realised prices should be somewhat lower, therefore limiting the impact on turnover. SSAB Americas shipments are also expected to grow quaerter-on-quarter in Q1, while SSAB Special Steels shipments are expected to be significantly higher than in Q4 2023.
Despite the overall weakening of financial results in 2023, SSAB notes that demand for steel with no carbon dioxide emissions increased significantly. “We delivered more than 50,000t of SSAB Zero, a steel without scope 1 and 2 emissions. Interest increased strongly not only in Europe, but also in the USA,” the group says.
“We have started the construction of the electric arc furnace in Oxelösund, a key item for fossil-free steelmaking. At the end of January 2024, the ruling on the granted concession for the power lines to Oxelösund gained legal force and the project continues according to plan,” it continues.
Emanuele Norsa Italy

UK EAF will find metallics, DRI considered: Narendran
Tata Steel is confident it will secure sufficient ore-based metallics supply to feed its prospective electric arc furnace at Port Talbot, despite concerns over DR pellet shortages. It will also look into the viability of gas- and hydrogen-based direct reduction at the site, Tata Steel chief executive TV Narendran said during a Welsh Affairs Select Committee meeting on Wednesday.
Narendran pointed out the decision to close the Port Talbot blast furnaces was made because Tata has had no return on investment in 15 years of operation, the production assets are reaching the end of their lifecycle, and decarbonisation financing is available. To keep the BF running without the coke ovens would mean another $600 million in loss funding is required and at least $200m in capital expenditure, the ceo added.
“The electric arc furnace need not be the end – it is the beginning. Tomorrow … if there is gas available in plenty in Port Talbot … and if there is some funding available to invest in a DRI unit, we can always set up a DRI unit,” Narendran noted during the meeting monitored by Kallanish. However, the firm is yet to discuss this with UK government.
At Tata’s Ijmuiden plant in the Netherlands, thanks to gas availability in that country, the firm plans to build a gas-based DRI-EAF operation, later migrating to hydrogen when it becomes available. It is yet to conclude discussions with the Dutch government over the sum of funding, Narendran said.
Tata Steel UK ceo Rajesh Nair added that, unlike Port Talbot, Ijmuiden already has a pellet plant which facilitates the DRI route.
The firm has also studied the possibility of using a reducing electric furnace (ESF) at Ijmuiden. However, since the technology is still unproven and the investment required is considerable, it decided to wait till another firm builds it first, Narendran explained.
Pressed by Stephen Kinnock, MP for Aberavon, about concerns over access to sufficient metallics supply to blend with scrap feed in the EAF, the executive said: “We will have access, we are a big global player.” There is a lot of work going on globally to increase DR-grade pellet supply, which should address any supply problems in the next 3-4 years, he added.
Kinnock argued it is “hugely risky” to abandon the BF on the basis of there potentially being sufficient pellet supply “from somewhere in the world” to run the EAF. Narendran countered by saying that running the BF/BOF in the same meltshop as the EAF would be even more risky.
The Aberavon MP also highlighted the risk of the EAF not being commissioned in time and steel feedstock imports for Port Talbot from India then being impacted by the UK’s Carbon Border Adjustment Mechanism (CBAM). “All the more reason we want to build the electric arc furnace sooner than later,” Narendran replied.
Asked about the national grid connection for the new EAF, Narendran said power supply was initially seen as a bottleneck but it is now scheduled to be ready for 2027. Nair added: “That’s a formal commitment from the National Grid to make that happen, so it’s well within our plans.”
Narendran said that although Tata has made no commitment yet to build a scrap shredder at Port Talbot, it does plan to invest in the UK scrap supply chain.
Kinnock also pointed to concerns about Ijmuiden blast furnace no.6 operational issues impacting the Trostre site’s ability to source feedstock from there once the Port Talbot BFs are shut. “That blast furnace [BF6], yes, did get delayed … It’s starting this week, so that’s behind us … It was basically a relining of blast furnace 6, that’s now complete, so we should have the feed [for Trostre] and we are making sure that, if required, we can feed the Netherlands from India, so that the Netherlands can support the UK,” Narendran concluded.
Asked about whether Tata will in fact build the Port Talbot EAF, the ceo said: “Yes, we are committed to building an electric arc furnace.”
Adam Smith Poland
Tata Steel relights BF in IJmuiden
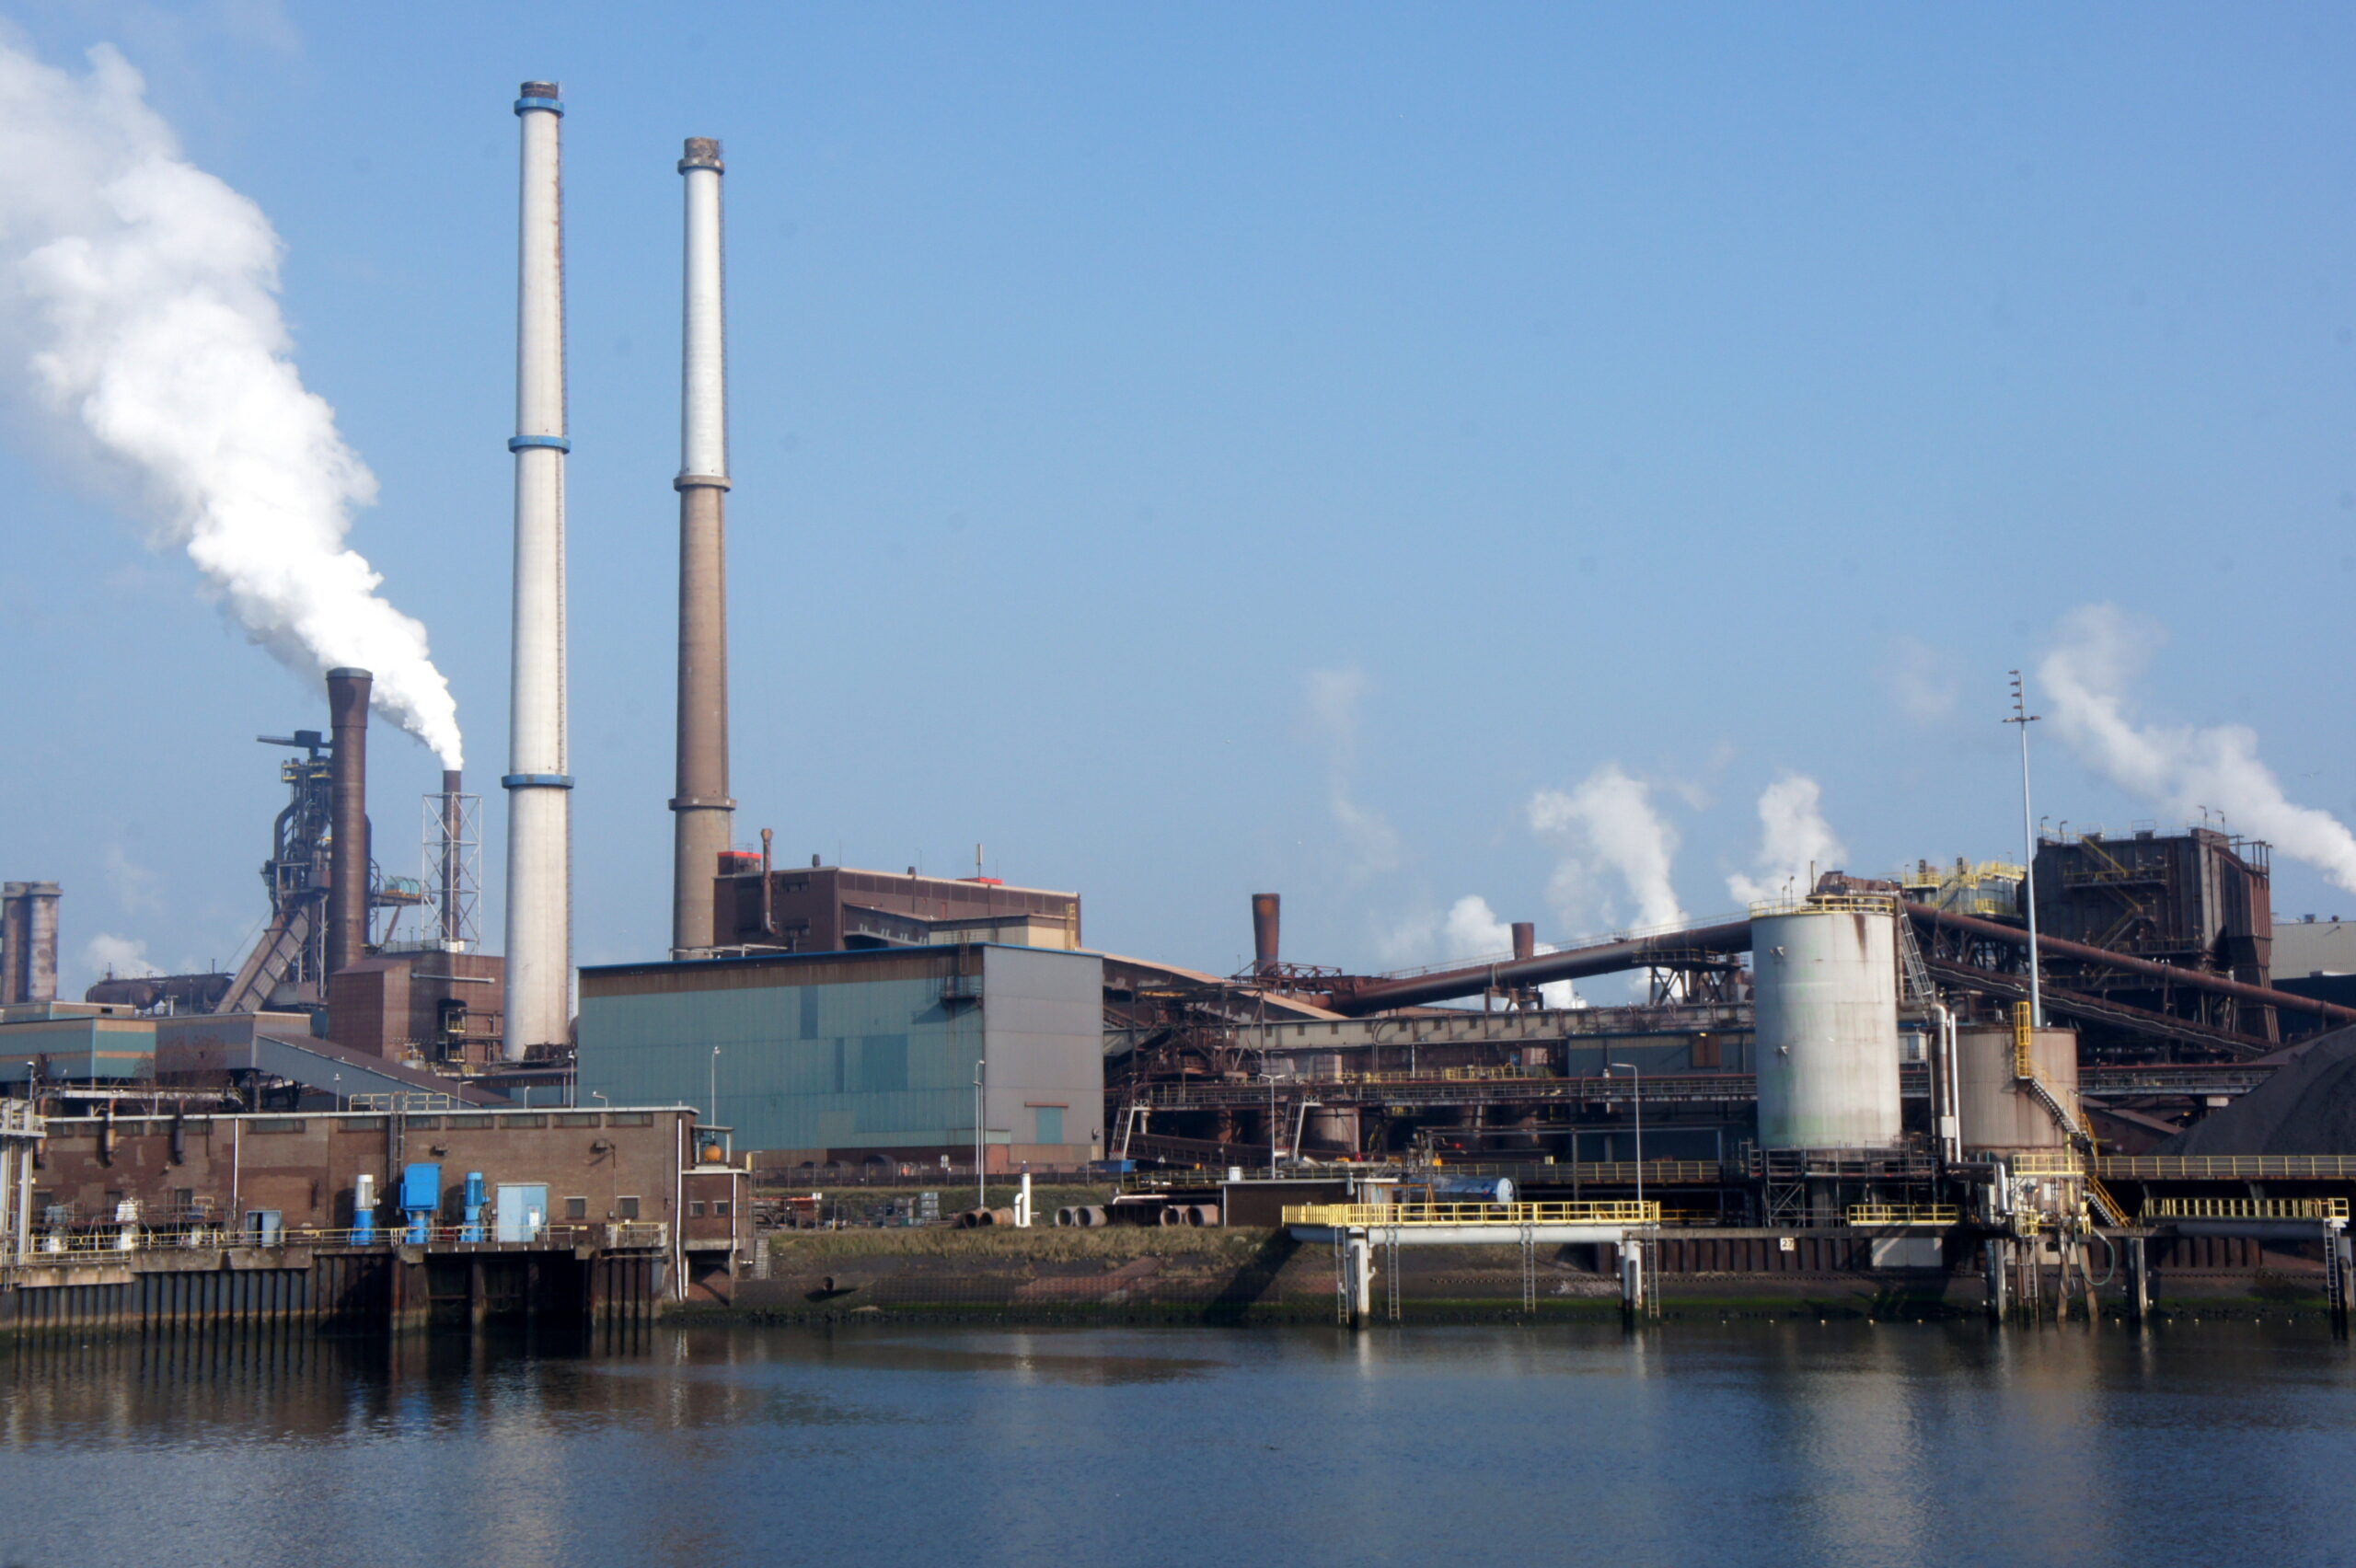
Tata Steel’s BF6 was idled late in March 2023 for maintenance work. The restart, however, was postponed several times because of “technical issues.”
“[The relining of BF6] is a large project and has a number of third-party dependencies in terms of services and equipment,” a Tata Steel spokesperson said on October 23. “As a result of certain delays and delivery issues from third parties, we have had to make changes to the schedule of the project.”
The furnace has now been finally reignited, however.
“A few days ago,” the spokesperson said on January 31, “we began the start-up process on BF6. Step by step, we are working toward a full ramp-up in the production of hot pig iron.”
Several sources familiar with the matter said that the BF in IJmuiden was restarted on January 29.
The IJmuiden steelworks can produce 6 million tonnes per year of pig iron from two BFs. BF6 has capacity for 2.5 million tpy of that total volume.
Tata Steel IJmuiden has capacity for 7.5 million tpy of crude steel, according to Fastmarkets’ company information. The site produces hot-rolled, cold-rolled, hot-dipped galvanized and pre-painted coils as well as tin-plated products.
Market concerns
Market sources were worried that, if more steelmaking capacities were brought back online in the first quarter of 2024, this might hamper the fragile uptrend in the EU flat steel market.
Prices for flat steel in Europe have been picking up in January, primarily driven by reduced supply resulting from output cuts and some limited restocking activity, although end-user demand remained low.
“The acute price rise [in HRC] is entirely supply-driven,” a source in Northern Europe said.
Fastmarkets calculated its daily steel hot-rolled coil index, domestic, exw Northern Europe, at €760.63 ($824.13) per tonne on January 31, up by €3.75 per tonne from €756.88 per tonne on January 30.
The index was also up by €13.96 per tonne week on week and by €65.13 per tonne month on month.
Earlier this month, Salzgitter restarted its BF “A” at Flachstahl in Germany after a four-month outage.

Published by: Julia Bolotova