

Liberty Belgium plants receive funding, eye mid-February restart
Liberty Liège’s Flémalle and Tilleur plants are expected to restart by mid-February after the firm received the funding required to carry out the first step of its transformation plan. The funding comes alongside the successful conclusion of a number of commercial negotiations.
The transformation plan is expected to be well advanced by the spring. It includes the tinning line at Tilleur developing a new business model, which will see it build partnerships with major customers to manufacture specialist packaging for their products. Also included is the G5 galvanisation line at Flémalle being used to generate short-term profit, a spokesperson for parent company GFG Alliance tells Kallanish.
Toker Ozcan, chief executive of Liberty Steel GREENSTEEL EMEA, which includes Liberty Liège, says: “We strongly believe this new plan is in the best interests of our employees and our loyal customer base. This will help us to deliver a sustainable business model for Liberty Liège. Now we have the initial funding in place, which demonstrates Liberty’s commitment to the business, we are able to restructure and ramp up the business as soon as possible.”
“We continue to encourage the regional Government to support the delivery of this plan. With the continuing rise in energy prices in Europe, with their impact on cheap imports, we also need the continued commitment of the unions to support the transformation of Liberty Liège, which will make the business more productive, more competitive and better able to compete in the global market,” Ozcan concludes.
GFG Alliance has provided funding exceeding €40 million ($46m) to Liberty Liège since it was acquired in July 2019. However, GFG’s long-term investment plans for the plants were initially undermined by the poor steel market in 2019 before the business was adversely impacted by the pandemic and supply chain disruptions, the group says.
Adam Smith Germany

Liberty Steel confirme le financement de ses activités à Liège
Nouveau rebondissement à Liège: Liberty Steel confirme finalement le financement de la première étape du plan de transformation sur ses sites en bord de Meuse.
En toute fin d’année dernière, Liberty Steel Liège avait annoncé aux ouvriers renoncer à un plan de relance, pourtant validé par la justice belge un mois plus tôt , suite à son incapacité à trouver de l’argent frais (devant venir de la filiale roumaine du sidérurgiste) nécessaire à l’achat de matières premières pour l’approvisionnement des sites de production. Ce qui mettait en péril l’avenir de plus de 600 ouvriers.
Du fait des liens industriels avec le site de Liberty Steel à Dudelange, la situation liégeoise était également suivie de près par les syndicats et ouvriers au Luxembourg .
Ce vendredi, Liberty Steel a effectué un virage à 180° en confirmant le financement de la première étape du plan de transformation de Liège. «La direction de Liberty Liège annonce que le financement nécessaire à la réalisation de la première étape du plan de transformation de l’entreprise, qui comprend deux usines à Flémalle et Tilleur, a été reçu de Liberty Steel Group. Ce financement, combiné à l’aboutissement d’un certain nombre de négociations commerciales, permet d’envisager le redémarrage des usines pour la mi-février, conformément à l’engagement pris par Liberty auprès des autorités», indique le groupe sidérurgique, dans une communication officielle, avant de souligner que «le plan de transformation, qui assurera à l’entreprise liégeoise un avenir durable à long terme, devrait être bien avancé d’ici au printemps».
Un peu plus loin, Toker Ozcan, CEO de Liberty Steel Greensteel, a réaffirmé son engagement à voir les activités de Liberty Steel s’inscrire durablement à Tilleur et à Flémalle.
Le sidérurgiste a également rappelé avoir déjà apporté plus de 40 millions d’euros de financement dans ses deux sites liégeois depuis leur acquisition en juillet 2019, tout en soulignant avoir vu ses plans d’investissement à long terme freinés par la médiocrité du marché de l’acier en 2019, avant que l’activité ne subisse l’impact négatif de la pandémie et des perturbations de la chaîne d’approvisionnement.
Si l’annonce va rassurer du côté luxembourgeois, du fait de l’importance de l’activité liégeoise dans les approvisionnements du site de Dudelange, le manque de certitudes autour de la surface financière du sidérurgiste risque d’agacer encore un peu plus les syndicats liégeois.
Écrit par Jeremy Zabatta
Publié le 14.01.2022

Europe plate: Market slow to resume
London, 14 January (Argus) — Sentiment in the European plate market has been mixed this month, as Italian mills pushed for higher prices after offering discounts in late December, but competition remained high.
The Argus monthly ex-works Italy plate assessment fell by €20/t to €840/t, but ex-works plate in northwest Europe was flat at €970/t.
Italian producers lowered plate prices to €840-850/t ex-works for base grade in the second half of December in order to boost their competitiveness, but have started to lift offers to €860/t ex-works, reflecting increased energy costs and anticipating that slab prices will pick up. At the same time, some suppliers were heard willing to provide at least €10/t discounts to the latest workable prices to fill their order books, as well as in the face of cheap import offers and sufficient margins.
Plate offers from different Asian countries were heard at €820/t cfr and slightly below to main European ports. But complications with quotas and finances made imports from Indonesia and India less attractive, with a South Korean supplier targeting other markets, a European participant said. In particular, an offer of S355J2 grade was heard at $970/t cfr to north Africa from South Korea.
Northwest European producers were sold out in December and resisted the downward pressure. Actual trading is yet to resume, as many participants have only returned from holidays this week.


European HRC prices soften amid slowing demand as mills try to hold firm
European HRC prices declined marginally Jan. 13 as market participants reported a wide spread on coils, dependent on volumes relative to each mill. Sources have said they feel the market is in a state of uncertainty, with buyers holding back from purchasing material.
A large European mill announced Eur1,160/mt delivered Europe for North European HDG prices, with a range of Eur20-25/mt for other regions, which would constitute an overall increase of around Eur30-50/mt.
A Nordic buyer source cited a North European HRC tradable value at 920/mt ex-works Ruhr, with tendencies toward Eur900/mt growing closer for some based on a lack of demand.
An Italian mill source said price increases would be possible but was unsure if they would come to fruition.
The source told S&P Global Platts that majority of mills were trying to prevent any decline in price, but whether this was a sustainable option was doubtful.
“Right now, the supply is there but activity is low,” the source added. “… I don’t think buyers are persuaded of new price hikes from mills — it’s not certain for the moment.”
The same source said it was unclear about whether the market would soon strike a balance between supply and demand amid still-sluggish automotive demand.
Platts assessed North European HRC prices down Eur2.50 at Eur922.5/mt ex-works Ruhr, and in Southern Europe, prices remained stable at Eur835/mt ex-works Italy Jan 13.
— Catherine Brown


Klöckner eyes net zero emissions by 2040
Klöckner & Co plans to reduce directly controllable emissions to net zero by 2040, Kallanish learns from the German-based steel distribution group. Emissions that it can only control indirectly – primarily from bought-in steel products – are to be cut to net zero by 2050.
The company signed up in 2020 to the Science Based Targets initiative (SBTi) “Business Ambition for 1.5°”. The SBTi has now validated the near-term carbon reduction targets adopted by Klöckner as science-based targets.
With those targets, Klöckner says it will achieve by 2030 a 50% reduction in its scope 1 and 2 emissions, meaning emissions associated with the business itself, such as from company-owned vehicles and purchased energy. In Scope 3, the company will likewise reduce directly controllable emissions, such as from business travel, by 50% by 2030. Non-directly-controllable emissions, for example from bought-in products and services, will be cut by 30% by 2030. These near-term targets are in line with the Paris Climate Agreement, the firm says.
In Scope 1 and 2 alone, the company expects to save some 90,000 tonnes/year of carbon from its own emissions. The package of measures to this end has been titled “kloeckner takes action 2040”. Activities include further centralisation of energy procurement and a progressive switch to renewable energy sources. The group has also begun converting its car and truck fleet to innovative means of propulsion, including electric mobility and hydrogen.
In October, Klöckner was the first steel distributor to enter into partnership with the Swedish start-up H2 Green Steel (H2GS) to secure access to virtually carbon-emission-free steel (see Kallanish 7 October).
Christian Koehl Germany

Tenova tests hydrogen for steelmaking decarbonisation
Italian energy infrastructure operator Snam is teaming up with technology maker Tenova to decarbonise the steel production process using green hydrogen. The companies will collaborate to test Tenova’s solution fed by green hydrogen at steelmaker’s sites.
“The aim is to bring integrated, turnkey commercial solutions tested at industrial plants to implement a substantial reduction of CO2 and NOx emissions in the metals production process – from melting to processing of half-processed products,” Tenova says in a note. It adds it will contribute its experience in combustion systems for reheating and heating treatment, and in electric arc furnaces. Tenova’s combustion systems can function with either a blend of natural gas and hydrogen or with to 100% hydrogen, Kallanish notes.
Snam will share its hydrogen transport and technology know-how overseeing the integration of Tenova’s solutions across the hydrogen value chain. At the Italian equipment maker’s headquarters in Varese, the two firms will perform tests applying hydrogen solutions to steel production.
Natalia Capra France
Acciaierie d’Italia restarts equipment
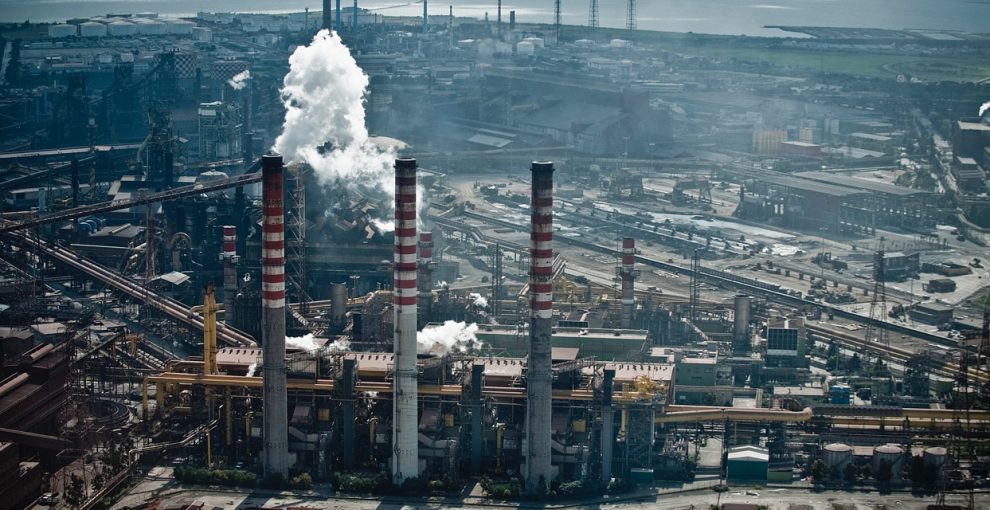
Acciaierie d’Italia, the joint venture between ArcelorMittal and state-owned Invitalia, is restarting equipment at the Taranto steelworks, Kallanish learns from trade unions.
Last month, the steelmaker mothballed blast furnace No.4 because of a technical issue. Meltshop No.1 is also idled, together with continuous casting units No.1 and 5.
This week, coke battery No.12 is resuming production, while from 17 January maintenance works will start at Meltshop No.1. This is a prelude to the resumption this month of BF No.4.
In October last year, the steelmaker restarted BFs 1 and 4. The latter was idled for about seven months and the company spent €70 million ($80m) on upgrade works.
Acciaierie d’Italia posted approximately 4.4 million tonnes of output in 2020 and had a production target of 5mt last year. Output for 2021 is yet to be announced.
The steelmaker will produce 8mt in 2025, its management confirmed last month during a meeting with unions and authorities at Italy’s Ministry for Economic Development in Rome.
Natalia Capra France

European coil contract parties develop new rules
European coil mills and their customers are devising ways to ensure tonnages taken up by buyers do not fall significantly under those contracted in annual agreements. Last year saw some trouble between mills and big customers, which in the second half of 2021 refused to call off the tonnages they had secured on the basis of their annual contracts.
The problem is not all-new, but was particularly pronounced in 2021. Annual contracts normally forecast the tonnages which customers anticipate they will need in certain months over the year. The shortage of semiconductor chips, however, put a radical break on the production of cars, meaning carmakers and many suppliers decided not to call off contracted tonnages.
This does not only force mills to pile up the shunned tonnages at their yards. It is also a bone of contention as to who carries the financial burden in such cases, as customers refuse to pay for the volumes they do not pick, despite the contract.
For better synchronisation, some players have started using a set of measures they refer to as “rolling forecast”. Essentially, both sides agree to meet more often throughout the year, normally monthly, to monitor if the short-term forecast deviates from the initial projection.
One buyer of an automotive supplier explains: “If BMW fails to buy my products in such periods, we cannot use the steel we meant to buy at that time.” He tells Kallanish that mills essentially have an understanding for such dilemmas, and are prepared to concede lower volumes temporarily. Such concessions do work for annual volumes mills do not want to miss out on, he notes.
Another point is that mills simultaneously want to make sure buyers do not go for spot purchases because steel prices have become friendlier. “We grant the mills’ accountants access to our books so that they can make sure we have not two-timed them, and bought elsewhere,” he explains. This concept of continuous monitoring plus control is relatively new and was thought up only in 2020 in view of the irregularities brought up by the coronavirus pandemic, he says.
Christian Koehl Germany

Buyers criticise annual EU coil contract prices
Many northwest European coil market players are finding that long-term coil supply contracts agreed in recent days have resulted in favourable terms for mills and do not reflect the current business environment.
Mills had initially targeted a plus of €600/tonne ($686) over prices signed in October 2020 for 2021 contracts, when the subsequent price surge could not be foreseen. ArcelorMittal even went somewhat higher with its first price targets of €1,080 for hot rolled coil and €1,200+ for hot-dip galvanized coil.
The agreements ultimately settled at a plus of around €500 for galv and cold rolled coil, and possibly somewhat less for HRC. Most HRC deals averaged at around €1,000/t, with peaks of €1,050 and lows of €950, depending on individual parameters.
Mills were heard entering negotiations with the understandable attitude of seeking compensation for the previous low-priced deals of late 2020 – at €500-550/t for HRC. This meant they wanted to “decouple them from the actual spot price which has softened considerably since autumn”, consultant Andreas Schneider wrote in December.
The HRC spot market price has in the meantime kept slipping well towards €900, so mills cannot complain about the outcome of the contract deals. But some buyers do. “This is a Christmas present for them,” a manager of an automotive supplier complains to Kallanish. “The facts don’t justify that. The increase of raw materials would allow for a year-on-year plus of €300 at best.”
A manager at a German cold-roller company buying in half-year instalments concurs that “we are not happy with the result”. He says buyers had expected prices to come out lower than in May/June, when they were close to an all-time high.
He argues that market supply is much better now than last year, demand has normalised, and so has order intake at mills. Still, mills eventually had the better cards, probably because time has progressed too far already for buyers to risk playing much longer. However, at the time of the next half-year negotiation in May, “this might backfire on them”, the cold-roller manager says.
Christian Koehl Germany

European HDG imports heat up on safeguards, anti-dumping
The European hot-dip galvanized coil import market is heating up. Most import opportunities are now closed for the first quarter due to exhausted safeguard quotas, while the upcoming anti-dumping decision could impact Q2.
During the first days of January, European importers of HDG exhausted most safeguard tariff-free quotas for HDG in the 4a sub-group (not for automotive). Indian quotas were fully used, as were “other countries” quotas of over 400,000 tonnes.
The “other countries” 4a quotas were filled mainly with Russian and Turkish material. The countries are being investigated for potential anti-dumping measures by the European Commission and sources in Turkey believe provisional measures could be imposed by end-March at as high as 20%, meaning new imports will become virtually impossible.
“The HDG import market in Europe is a mess and from Q3 we should also see some volumes arrive from Vietnam that will use available quotas,” a trader tells Kallanish. “European mills clearly have the upper hand for the coming months thanks to the total use of safeguard quotas in Q1 and upcoming AD measures.”
Earlier this week, ArcelorMittal started announcing a price increase of €30-60/tonne on its HDG – and cold rolled coil – across Europe (see Kallanish passim). It is understood the new reference offer level for Germany and northern Europe for HDG would be €1,160/t ex-works base. The Kallanish HDG index for northern Europe is yet to move following the announcement, but sentiment is picking up in terms of domestic prices.
In addition to HDG 4a quotas, Chinese HDG 4b quotas have also been fully used during the very first days of January, putting further pressure on the market for auto sheet.
Emanuele Norsa Italy