


EU industry demands skyrocketing energy cost policy support
European industry representatives, including Eurofer, have called for immediate support to address the skyrocketing energy prices that they say are jeopardising the post-pandemic recovery. Ahead of the European Council meeting, they are also calling for structural measures to secure affordable low-carbon energy.
Gas and electricity prices have risen exponentially in recent weeks, to a level 4-5 times up on last year, due mainly to the imbalances in the gas market. Also contributing are seasonal factors that have reduced renewable energy production, reduced nuclear energy production and increased carbon costs passed on in electricity prices, the industry associations say in a joint statement.
Energy-intensive companies that are most exposed to such price spikes have been forced to curtail production or temporarily close plants. Protracted high prices on spot markets are also being reflected in futures for the first semester of 2022. “Such a trend represents a major threat for the full post-pandemic recovery,” the associations comment.
Besides European steelmakers, the European Cement Association (Cembureau), European Aluminium, The European Lime Association, Eurometaux, Euromines, Fertilizers Europe and Glass Alliance Europe, among others, have lent their voices to the statement, Kallanish notes.
The European Commission’s toolbox presented last week should be fully utilised by national authorities. “However, it is clear that this unprecedented crisis requires additional, urgent initiatives,” the statement reads.
“In order to address the imbalances of the gas market, the EU should use fully its commercial and diplomatic pressure on the major gas suppliers,” the associations point out. “Furthermore, ad-hoc state aid rules are necessary to enable member states to react more prominently than currently allowed during periods of energy market stress. At the same time, a close monitoring mechanism of electricity and gas markets needs to be established to prevent further ‘outages’ during the upcoming winter.”
“Sudden increases of the carbon price under the EU Emission Trading System should be avoided and effective carbon leakage protection needs to be secured in the revised ETS Directive; long-term corporate Power Purchase Agreements (PPAs) should be promoted to facilitate access to competitive carbon free electricity at more predictable prices than spot markets,” the associations observe.
Adam Smith Germany


Energy-intensive industries’ joint statement ahead of EUCO: EU urged to take swift action in order to tackle unprecedented energy crisis
Ahead of the European Council meeting, industry calls for immediate support to address the skyrocketing energy prices which endanger the post pandemic recovery, coupled with structural measures securing the affordable low carbon energy required to meet the objectives of the EU Green Deal.

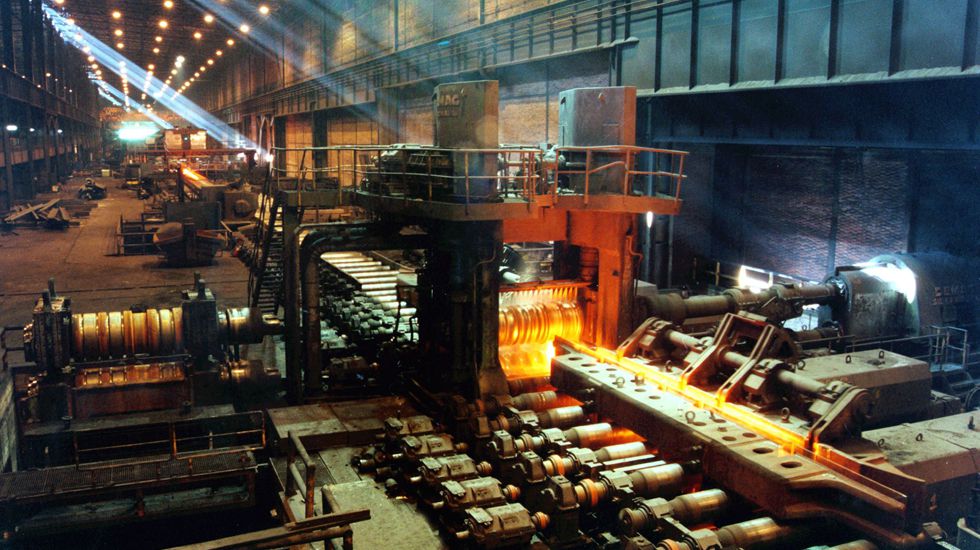
TK Materials to build new steel service center at SDI Texas plant
Thyssenkrupp Materials is setting up a new steel service center at the site of US steel producer Steel Dynamics’ new mill in Sinton, Texas, and is expanding further at existing service sites in the US, it said Oct. 19.
Thyssenkrupp Materials will manage the supply chain between the steel plant and individual OEMs — in particular for the automotive industry. The investment of around Eur28 million includes a building with an area of 14,000 sq.m and processing equipment for slitting and cut-to-length of flat steel.
The Sinton mill is still under construction and Steel Dynamics said steel output at the site is expected before the end of 2021 with production of 2 million-2.2 million st in 2022.
Thyssenkrupp Materials is investing over Eur70 million in the expansion of its service business in total in the US.
The company is also expanding capacities, processing and supply chain services at its steel service centers in Alabama, Wisconsin and Tennessee, looking to expand further to gain greater market share in the industry.
“We now want to use our affinity for services in particular to improve our market position even further — if possible also with further acquisitions. Today we are already number three in America. That is not enough for us,” the company’s chairman Martin Stillger said.
Business in North America alone accounts for around 25% of total sales of Thyssenkrupp Materials globally. The North America business sources material from local suppliers to keep transport routes and costs low, a Thyssenkrupp Materials spokesperson told S&P Global Platts.
Thyssenkrupp Materials in Europe sources around 10% of its steel from the Thyssenkrupp Steel Europe mills in Germany which are primarily distributed to the German market.
Thyssenkrupp Materials is the distribution arm of German’s Thyssenkrupp.
— Laura Varriale


Hyundai eyes semiconductors production to reduce shortages
South Korean carmaker Hyundai Motors plans to develop its own semiconductor production to reduce dependence on suppliers, says global chief operating officer Jose Munoz.
“The industry on chips is responding very, very quickly,” Munoz said in a Reuters interview. “Intel is investing a lot of money to expand capacity and in our case, too, we want to be able to develop our own semiconductors within the group, so that we are less dependent in another similar situation.”
Although Hyundai has suspended operations at some plants, Munoz said the worst of the crisis was over, adding that for the carmaker, the hardest months were August and September, Kallanish notes.
The Hyundai Mobis component unit will play a key role in the implementation of this plan. “Hyundai aims to increase car deliveries in the fourth quarter to the level of its business plan and to compensate for some of the production losses,” he added.
Along with Toyota and Tesla, Hyundai is among those carmakers that have increased global sales despite chip shortages.
In September, low semiconductor deliveries forced Ford, General Motors, BMW, Volkswagen Audi, Opel, Nissan and Volvo to halt some production sites (see Kallanish passim). Russian carmakers were also hit by the supply disruptions.
The global automotive sector has rebounded strongly since the initial Covid-19 lockdowns last year but supply chain disruption is constraining further growth, worldsteel said last week.
Global semiconductor shortages will cost the worldwide automotive industry around $210 billion in lost revenue this year, shows the latest forecast of consulting company AlixPartners. The consultancy is now forecasting that vehicle production of 7.7 million units will be lost in 2021.
Svetoslav Abrossimov Bulgaria

European stainless flats shortage pushes prices up again
Tight European stainless steel hot and cold rolled coil supply is worsening amid slow sheet and coil derivative deliveries. Prices are increasing again on account of costly nickel and alloy surcharges, ferrochrome and other raw materials, market participants tell Kallanish.
All European coil producers are now quoting lead times till May 2022, while only one steelmaker is quoting April but solely for its existing customers. Because of the high cost of energy, European producers are increasing their base prices versus September, and adding daily and monthly alloy surcharges.
European stainless HRC is offered at €3,800-3,900/tonne ($4,426-4,542) delivered on average. Stainless CRC contracts for European material now start at €4,100/t delivered, including alloy surcharges, depending on material quality and volumes.
There are no import offers reported that would ease the tight coil supply. Indonesian producers are supplying Chinese buyers and have very little availability for Europe, while Taiwan and other regions have no extra product to offer as they are dealing with tight supply in their own domestic markets. As prices escalate, European buyers’ main concern remains the ability to procure material.
Stocks of flats and tubes are said to be low throughout Europe. Moreover, Italian re-roller Marcegaglia’s main stainless pickling line at its Gazoldo degli Ippoliti facility caught fire earlier this week and will be idled for some time, the company confirms. While no fatalities were reported, production will be strongly affected and deliveries will be significantly slowed.
Natalia Capra France

EU traders highlight rising coil import sentiment
Traders active in coil imports into Europe have highlighted rising sentiment this week, mainly supported by the Turkish and CIS markets.
According to Kallanish price series, import transaction prices for hot rolled coil into southern Europe dropped during August and September. Levels are now seen recovering from the low reached at the start of October.
“Turkish suppliers are trying to raise their offers on a weekly basis, particularly for CRC and HDG,” a trader notes. He reports hearing CRC from Turkey quoted at €1,020/tonne ($1,188) cfr southern Europe, but adds this level could well move up in the coming days.
Another trader confirms the rising sentiment. He believes this will ease pressure on European domestic mills in the coming weeks.
Indian suppliers of HRC are reported to be silent at the moment, having rapidly filled EU import quotas for the fourth quarter. Turkish suppliers are offering HRC at €920-930/t cfr Italy, but some believe transaction prices might be somewhat lower. From Ukraine, offers for HRC are at below €900/t cfr Italy, but still recovering from lower levels registered in early October.
Emanuele Norsa Italy
How the EU CBAM will shape emissions costs
On 14 July 2021, the European Commission (EC) put forward a package of proposals in order to achieve its ambitions related to climate change.
These include a proposal to revise the EU Emissions Trading System (ETS) and a proposal to implement a Carbon Border Adjustment Mechanism (CBAM), which would both impact the primary aluminium sector. As scope 2 emissions are excluded from the CBAM coverage, the proposals impact primarily the outlook for scope 1 emissions costs calculations.
Free allocation to be gradually phased out from 2026
The CBAM addresses the so-called risk of ‘carbon leakage’ and is an alternative to the system of free allocation put in place in the EU ETS. As such, the proposals provide that free allocation under the EU ETS will be gradually phased out from 2026, as the CBAM is phased in. More precisely, a factor of 0.9 will be applied to free allocations in 2026, which will decrease by 0.1 each year as shown in the table below. This means free allocation will be completely phased out by 2035, and by this time, industrials will have to pay for all of their emissions.

This directly impacts the outlook for scope 1 emissions costs, as all the emissions that a smelter produces which are not allocated for free need to be auctioned.
The table below shows the average scope 1 emissions across smelters operating in the EU ETS, as well as the outlook for the average amount of free allocations, as calculated according to the EU ETS regulations and taking into account the CBAM factor. By 2031, free allocations would represent 36% of all scope 1 emissions, which means smelters would pay for 64% of their scope 1 emissions, on average. With an EU Allowance (EUA) price of $60/t CO2e, the average scope 1 emissions cost would be around $74/t Al.

The chart below shows CRU’s base case forecast for the average scope 1 emissions cost across European smelters out to 2031, as well as what would be the outlook if no CBAM factors were applied.

Benchmarks update for the 2025-2030 period
The proposal to revise the EU ETS does not change the basic rules for calculating the free allocations received by smelters. Free allocation is based on benchmarks representing the level of performance of the best-in-class installations, within the industry. Benchmark values have been published for the 2021-2025 period, i.e. the first sub-phase of the EU ETS phase 4. However, the benchmark values for the second sub-phase running until 2030 still need to be assessed and published.
The EC’s recent proposal to revise the EU ETS provides that the maximum annual reduction rate for the benchmark values will increase from 2026, to 2.5% instead of the 1.6% currently in place. This maximum rate applies to all industries, and the actual rates applying for the aluminium industry may be lower and depend on how best-in-class installations improve performances in terms of emissions. In CRU’s base case, as shown above, the values of 1.416 and 0.302 have been used for the electrolysis benchmark and pre-bake anode benchmark, respectively, for the 2026-2030 period. They correspond to a 0.7% annual reduction rate relative to the benchmark values applied during the 2021-2025 period.
Learn more about our emissions data and analysis.
Author: Caroline Alglave Senior Analyst

The future of green premia: A multi commodity perspective
Italian flats output surges in September
Italian crude steel output increased significantly again in September after rising in previous months, according to data issued by local steelmakers association Federacciai.
Last month, crude steel production rose by 28% year-on-year to 2.3 million tonnes, Kallanish notes. Output also hiked in the first nine months of the year, by 27.6% on-year to 18.6mt.
Italian flat steel production rose by as much as 50.8% to 1mt in September, and by 18.8% to 8.1mt in the first nine months of the year.
Longs output increased last month by 8.7% to 1.2mt, and by 29.6% to 10.2mt in January-September, Federacciai says.
Natalia Capra France

Assofermet asks EU to suspend coil anti-dumping duties
Italian distributors’ association Assofermet has asked the European Commission to recognise the coil supply/demand imbalance in Italy and adopt the same suspension of anti-dumping duties as implemented for aluminium flat-rolled products originating from China.
“Assofermet hopes that the recognition of the current market situation in the aluminium sector may also find confirmation in the case of the EU safeguard on steel imports, in the general interest of the Union and of the companies in the downstream supply chain, distribution, transformation and end-users, to fairly balance the economic interests at stake between the parties involved in the entire supply chain,” the association says in a note sent to Kallanish.
On 8 October, the Commission suspended duties on flat-rolled aluminium from China for nine months. According to the association, the decision does not represent a dangerous precedent for other trade defence cases, as maintained by European aluminium producers. It proves simply that a change of position may happen in “certain situations of recognised extraordinary nature” such as the current steel market situation of strong demand, short supply and extremely high prices.
Assofermet also formally lodged with Italian authorities a request for a review of the EU safeguard system. The association noted that the request was well received by Italian economic development minister Giancarlo Giorgetti. The minister reiterated last week during the Made in Steel show in Milan that the safeguard system no longer works properly and needs revision (see Kallanish 7 October).
Natalia Capra France
Steel prices won’t decrease anytime soon: Irepas committee
Steel prices will not significantly decrease at least until the second quarter of 2022, as high raw material, shipping and energy costs as well as production cuts in China have been supporting prices globally, said F.D. Baysal, president of Seba International Inc. and chairman of the Irepas traders committee.
Baysal and other participants expressed generally positive views about the market situation at the 85th Irepas meeting. Their outlook for the coming year was also positive.
Highlighting that most producers have been working at high capacity utilization following the ease of the pandemic, and margins have never been better, Michael Setterdahl, board member of GFG Alliance and Liberty Steel said: “It’s a great time to be in the steel business!”
Setterdahl is expecting the market situation will remain excellent in the first quarter of the next year, as steel consumption is growing globally and China is expected to continue to be out of the export markets.
Highlighting that especially high coal and energy prices have been pulling up mills’ input costs, the chairman of the Irepas committee said energy prices and China are important factors for the coming months.
The cost of producing steel is increasing, especially on the energy side, the chairmen said, adding that high freight rates are also another factor in higher costs.
Jens Bjorkman, head of ferrous trade at Stena Metal International, said they are expecting general conditions to continue to improve with the ease of the pandemic and the market will continue to perform well next year.
Highlighting that scrap prices started to improve as of October, from low points seen in September, due to seasonal factors, strong production rates and fairly balanced market conditions, Bjorkman is expecting demand levels will continue to be supportive for scrap prices. “We will see if this will be a trend or we will hit a bump in the road,” he said.
Turkish deepsea import ferrous scrap prices moved closer to $500/mt CFR at the end of last week, with further deepsea cargoes booked. S&P Global Platts assessed Turkish imports of premium heavy melting scrap 1/2 80:20 Oct. 15 at $497.50/mt CFR, up $7.50/mt on day, to reach the highest level since July 6, when the index also sat at $497.50/mt CFR. The index has risen $64.50/mt since a recent low Sept. 28.
Turkish mills have raised their prices gradually to $740-$755/mt in this bullish sentiment, up more than $70/mt since October.
However, imported scrap prices inched down on Oct. 18 as deepsea activity cooled amid mill uncertainty over near-term domestic demand and interest rates. S&P Global Platts assessed Turkish imports of premium heavy melting scrap 1/2 80:20 Oct. 18 at $495/mt CFR, down $2.50/mt on day.
— Cenk Can