


German rebar benders face diminishing profitability
Distributors and benders of rebar in Germany have had reason to complain about deteriorating prices throughout the whole year, especially on the selling end to builders.
A manager at one renowned bender group has now pointed out to Kallanish that many companies of its kind could also see their financial cushion diminish in the remainder of the year. “There is an essential difference in that the older jobs that generated some profit are now completed,” he explains. “Now, we will be handling orders from the second half of 2023,” when sales prices sunk to the level of rebar intake prices, and in some cases undercut them.
His group informed customers during the summer that it would not be able to work with sales prices of less than €700/tonne ($775). It asked customers “not to perceive this letter as a sign of weakness, but as a proof of trying to work as partners on the same footing.”
This calculation would apply a rebar intake price from mills of around €620/t delivered, where prices landed in May/June. Overall, values have hardly budged since.
According to benders, the price deterioration downstream is harder. Another manager, who has not read the former group’s letter, but agrees with its content and message, says: “I myself went down in an offer as far as €640 on the sale side – and I did not get the award. Someone else was cheaper.”
On the brighter side, the former group’s manager notes that some types of jobs are increasingly available, even if not profitable. According to him, job offers from big projects are coming in. But this is good news only for big benders that handle volumes of 3,000 tonnes and more. “And still, these jobs are not profitable either,” he bemoans.
Christian Koehl Germany

German steel industry to become major green hydrogen offtaker
Europe’s steel industry is set to be a significant consumer of renewable hydrogen and German steelmakers in particular have some of the most advanced plans in the region to tap the new green energy source.
Potential future demand from the German steel sectorcould amount to 850,000 metric tons per year by 2030, according to German steel association WV Stahl, with producers planning to connect to a national hydrogen pipeline network now under construction, as well as producing their own green hydrogen from electrolyzers onsite, saving 28 t of CO2 per metric ton of hydrogen.
The German government expects total hydrogen demand of 95-130 TWh (2.85 million-3.90 million t/y) by 2030, with 40-75 TWh from new demand.
Carbon-accounted hot-rolled coil steel commanded a $120/t premium to the Platts conventional HRC assessment of $615/t ex-Ruhr on Aug. 7.
Platts, part of S&P Global Commodity Insights, assessed the cost of green hydrogen production via alkaline electrolysis in Germany, backed by renewable power purchase agreements, at an average of Eur7.98/kg ($8.71/kg) in July.
“The steel industry offers one of the most encouraging new use cases for low-carbon hydrogen due to the amount of CO2 that can be abated per kilogram of hydrogen,” Commodity Insights senior hydrogen analyst Matthew Hodgkinson said. “However, switching to low-carbon steel production is expensive, with ETS prices of at least Eur150-200/t required to make it comparable to current production methods.”
Platts assessed nearest December EU ETS prices at Eur71.04/t Aug. 7.
Complete decarbonization of EU crude steel production would require around 6 million to 8 million t/y of low-carbon hydrogen, comparable with current total hydrogen demand, Hodgkinson said.
German steel producers, backed by national and EU government policies, aim for climate neutrality by 2045, targeting a 30-50% reduction in greenhouse gas emissions by 2030.

Greening steel
Steel production accounts for around 5% of European CO2 emissions, and 8% globally. Germany is Europe’s largest steel producer and seventh biggest in the world, and the sector accounts for around 30% of the country’s industrial emissions.
Steel is produced through two main production routes that both emit CO2 — the blast furnace/basic oxygen furnace (BF/BOF), and the direct reduction iron/electric arc furnace (DRI/EAF) routes.
The predominant BF/BOF route removes oxygen from iron ore using a carbon reducing agent, such as coking coal, leading to around 1.6-2 t of CO2 emissions per metric ton of crude steel produced. The basic oxygen furnace then converts molten iron from the BF into steel.
Meanwhile, DRI plants can use natural gas, hydrogen or a mixture to remove oxygen from iron ore. Using only renewable hydrogen produces zero greenhouse gases. The EAF melts scrap steel or DRI to produce steel using electric arcs.
Around 60% of European steel production is via BF and around 40% via EAF, according to industry association Eurofer. Germany produced about 35.4 million metric tons of steel in 2023, down 4% year on year, of which 9.8 MMt was produced via EAF and 25.63 MMt via BF.
Steelmakers plan to replace BFs with hydrogen-based DRI, with most DRI plants in Germany to be paired with an EAF (see map).
Salzgitter, Stahl-Holding-Saar and Thyssenkrupp have all issued tenders to source large volumes of low-carbon hydrogen for their steel production from later in the decade.
These companies, along with ArcelorMittal, received state funding commitments in 2023 and 2024 under the EU’s Important Projects of Common European Interest program on hydrogen and low-carbon technologies.
Powering up
The switch will see a huge leap in renewable power demand.
The German steel industry’s current electricity demand from the grid is 12 TWh, according to WV Stahl. This could double by 2030 to 24 TWh, with crude steel production estimated around 42 MMt/y. Further green electricity will be required to power electrolysis, of around 28-29 TWh.
While being a large increase, those figures are a relatively small fraction of German power demand of around 500 TWh in 2023, forecast to rise to 649 TWh in 2030, according to Commodity Insights data.
European steelmakers are already marketing low-carbon steel products. Platts launched its daily carbon-accounted steel premium assessment in May 2023, which reflects any differential achieved for spot sales of hot-rolled coil on an ex-works basis, with total accounted carbon emissions of 2.1 t of CO2, or less, for every metric ton of steel produced.
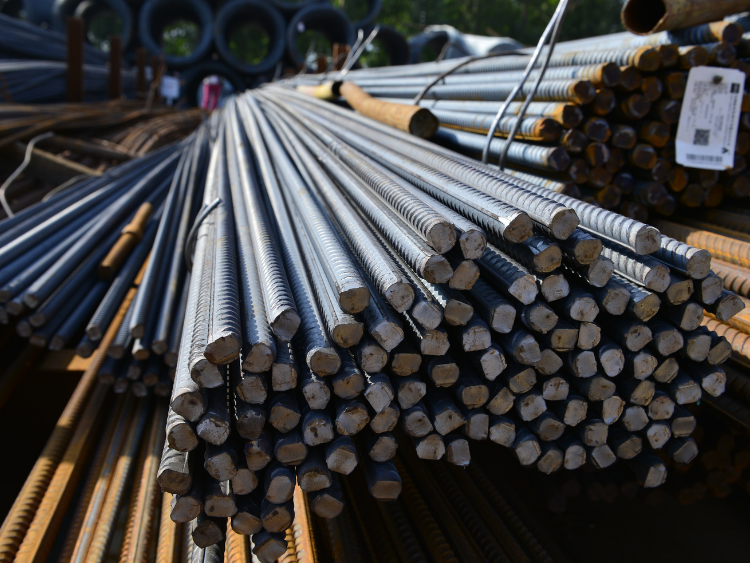
Feralpi’s new rebar mill in Germany will work with zero direct emissions
The unit was expected to address the need for long steel materials produced with reduced carbon emissions.
“For the first time in Germany, [rebar] in coils weighing as much as 8 tonnes will be produced for the construction industry, using an innovative, fully electric process with zero direct [carbon] emissions,” Feralpi said.
The construction of the new rolling mill is part of the company’s 2021-26 industrial development plan, which was intended to reduce its environmental effects through electrification.
According to Fastmarkets’ information, the new facility will have capacity for about 500,000 tonnes per year of rebar.
The company added that the technical investment related to its industrial development plan reached €169 million ($183.3 million) in 2023.
As well as the new rolling mill, the funds were invested in a new scrapyard in Germany, and technical improvements to existing facilities in Italy.
According to Feralpi Group, the investments helped the company to address the “need to offer low-emissions steel for both the infrastructure and mechanical engineering industries.”
Currently, the demand for carbon-reduced and green steel was stronger in flat steel products such as hot-rolled coil, trade sources told Fastmarkets. Such products are more expensive due to the premiums charged by producers, with the automotive industry being the main consumer.
Fastmarkets’ weekly assessment of the green steel domestic, flat-rolled, differential to HRC index, exw Northern Europe, was €170-250 ($184-271) per tonne on July 25, stable week on week.
And the assessment of the flat steel reduced carbon emissions differential, exw Northern Europe, was €40-60 per tonne on July 25, unchanged since May 30.
Regarding carbon-reduced and green long steel products, the practice of charging premiums was not widespread, trade sources told Fastmarkets. The construction sector was usually the main consumer of long steel products such as rebar and wire rod, but many companies in this field were not ready to pay additional costs.
Premiums have been charged sporadically for particular investment projects that required carbon-reduced and green steel products.
“We still need to educate the market about the advantages of green long steel products,” a producer source said.
Ambitious green goals
Feralpi Group planned to decrease its emissions of CO2 and other climate-affecting gases by 50% by 2030, the company said, adding that this referred to the Scope 1, 2 and 3 emissions related to its hot-drawn products. This goal has already been approved by the International Science-Based Targets Initiative SPTi.
In 2023, Feralpi Group reduced its Scope 1 and Scope 2 emissions by 24% year on year, the financial report said.
Challenging environment for steel products
In 2023, Feralpi Group produced 2.42 million tonnes of steel, down by 1.06% from the previous year.
But revenue dropped to €1.73 billion, compared with €2.40 billion in 2022. The decrease in revenue resulted in a significant reduction in earnings before interest, taxes, depreciation and amortization (EBITDA), which fell to €83.2 million compared with €501.7 million in 2022.
Feralpi noted that several factors weighed on the reduced steel demand, including the shift in consumption from goods to services, the weakening of European industry, and the more difficult conditions for investments.

Cogne expands German distribution network
Cogne Edelstahl says it is expanding its distribution network in Germany, along defined chapters – North, West, South – plus a new area, East, Kallanish learns from the speciality steelmaker’s German unit.
Cogne Edelstahl operates sites in Neuss in western Germany (North Rhine-Westphalia), Rudersberg in the south (Baden-Württemberg) and Stuhr in the northern city state of Bremen. They supply customers with products made in Italy, Taiwan and Sweden.
In addition, the company is establishing in July representatives in Leipzig to serve the East chapter. It total, Cogne Edelstahl will have 37 representatives in the country.
”The nationwide expansion will facilitate the availability of bar and bright bar at locations close to customers, including processing services, cutting, and certification,” says managing director Bernd Grotenburg. He notes the company has perceived rising demand from the east in recent years, and that it plans to establish a new warehouse there.
Christian Koehl Germany

Germany: May steel sales, stocks decline on year amid economic slowdown
German steel sales in May fell year on year and month on month, as demand remained low amid an economic slowdown, according to data from sales and stockholder association BDS.
Steel product sales in the German distribution and stockholding system in May totaled 770,914 mt, down 4% year on year and down 8.9% from April.
Sales of flat products totaled 469,922 mt in May, down 6.5% year on year and 8.6% lower from April. Sales of long products totaled 238,557 mt in May, falling 0.3% year on year and 7.4% month on month.
Sales of all other products totaled 62,435 mt in May, up 2.2% year on year but 16.4% lower than April.
Steel product stocks fall
Stocks of all steel products in the German stockholding and distribution segment in May totaled about 1.92 million mt, down 3.7% year on year and 5% month on month.
Flat stocks last month totaled 1.24 million, up 2.3% year on year but down 5.3% from April.
Stocks of long products in May fell 13.2% year on year and 4.2% month on month to 633,138 mt.
Stocks of other products totaled 42,589 mt, down 9.7% year on year and 7.4% month on month.
In a broader context, Germany has the largest steel production in Europe, at 35.4 million mt in 2023. Recent data has showed the German market is weak; in May output declined for the first time this year, falling 1.9% year on year to 3.2 million mt, according to data published June 20 by German steel federation WV Stahl.
In the January-May period, Germany produced around 16.2 million mt of liquid steel, up 3.7% compared with the same year-ago period.
Platts, part of S&P Global Commodity Insights, assessed Northwest Europe hot rolled coil prices at Eur630/mt ($674.45/mt) base ex-works Ruhr June 25, down Eur5 on the day.


Kloeckner Metals Germany nimmt neues Lasersystem in Betrieb
Kloeckner Metals Germany hat in Velten, Brandenburg eines der hierzulande modernsten Lasersysteme für Stahlbearbeitung in Betrieb genommen. Damit wird der Standort als High-Tech Kompetenzzentrum für mechanische Bearbeitung und Rohrlasertechnik etabliert.
Das neu in den Regelbetrieb überführte, automatisierte Lasersystem „Tube 5000“ des Herstellers Trumpf komplettiert den in Velten seit 2014 aufgebauten Groß-Lasermaschinenpark mit jetzt insgesamt fünf Systemen zum Schneiden und Gravieren von Stahl. Die Stahlendprodukte kommen im Landmaschinen-, Kran- sowie im Fahrzeugbau bei Herstellern in ganz Deutschland zum Einsatz.
„Diese Inbetriebnahme ist ein weiteres, industrieweit herausragendes technologisches Beispiel für unsere Innovationsführerschaft in der Stahlindustrie und ein zentraler Baustein auf unserem Weg zum Technologiepartner unserer Kundinnen und Kunden für höherwertige Stahlanarbeitung“, sagt Felix Schmitz, CEO Kloeckner Metals Germany. Darüber hinaus seien die Investitionen in den Standort Velten ein „deutliches Bekenntnis zum Industriestandort Deutschland“ und zum Land Brandenburg. „Hier können unsere Mitarbeiterinnen und Mitarbeiter an einer der fortschrittlichsten Anlagen auf dem Markt ihre ganze Expertise zum Tragen bringen“, so Schmitz.
Kloeckner Metals Germany: „eine der modernsten laserbasierten Anlagen“
Das neue Lasersystem ist Kloeckner Metals Germany zufolge die schnellste Laser-Rohrschneidmaschine der Welt und mit Ausmaßen von circa 16 x 7 Meter eine der größten und modernsten laserbasierten Anlagen für die Metall- und Stahlbearbeitung. Das System erweitere die Bearbeitungsmöglichkeiten mit Technologien wie unter anderem Fließ- und Spiralbohren, Gewindeschneiden sowie -formen und erlaubt Schrägschnitte von bis zu 45 Grad. Kunden und Partner von Kloeckner Metals Germany profitierten durch den Einsatz der Lasersysteme in Velten von besserer Leistung und mehr Effizienz, weil unnötige, bislang manuell erfolgte Arbeitsschritte vermieden würden. Darüber hinaus erlaubten die Systeme eine Just-in-Time Produktion und eine flexiblere und kosteneffizientere Logistik.
Der seit 1995 bestehende Standort Velten ist mit knapp 70 Mitarbeitenden neben Landsberg bei Leipzig und Zwickau einer von drei Standorten des Unternehmens im Osten Deutschlands. Über die Lasersysteme hinaus bietet der Standort mit seinen Hochleistungsmaschinen für den ersten und zweiten Produktionsschritt alle für die moderne Stahl- und Metallbearbeitung wichtigen Dienstleistungen an. Hierzu zählt beispielsweise ein kombiniertes Drehfräszentrum inklusive Lagerung, Sägen und CNC-Drehen. Das Leistungsportfolio reicht dabei vom Abspulen und Schlitzen über das Biegen von Flachstahl sowie dem Plasma- und Autogenschneiden bis hin zum Fräsen, Bohren sowie Kugelstrahlen und Beschichten.
Die Inbetriebnahme des neuen Lasersystems ist der jüngste Meilenstein von Kloeckner Metals Germany bei der Fokussierung auf höherwertige und hochqualitative Anarbeitungsservices, -lösungen und -dienstleistungen. Das Unternehmen hat darüber hinaus in den vergangenen Monaten bereits verschiedene zukunftsweisende Projekte umgesetzt. Hierzu zählen die Inbetriebnahme einer europaweit einzigartigen, roboterbasierten Entgratungsanlage am Standort Bremen, der Einsatz des deutschlandweit ersten eActros E-LKW von Daimler Truck im unternehmenseigenen Fuhrpark am Standort Würzburg sowie die Ersteinführung eines VR-basierten Schulungssystems für Kranführer in der Stahlindustrie am Standort Nürnberg.

German steel market sees prices remaining strong, production weaker
German steel traders and producers expected prices to remain strong during February, though the expectation was less firm month on month as mills tried to aim for higher prices but buyers held back, according to an S&P Global Commodity Insights survey.
The February index for traders’ sentiment stood at 60 points, compared to 68.75 points in January, data from S&P Global’s German Steel Sentiment Survey showed.
The index for producers’ sentiment was 62.50 points, compared with a January index of 87.50 points, showing that producers were significantly less firm compared to traders regarding near term price increases.
The overall index for prices was at 61.25 points, compared with 78.13 points for January.
Overall, steelmakers in Europe were aiming for higher prices for steel products.
One European long steelmaker expected prices in Germany for long steel products to remain stable or firm up. “We could cut down capacities rather than lowering prices,” the source said, adding there did not seem to be any fundamental reason for prices to go down.
“Medium sections prices are the lowest level in the last three years,” the source said. “Energy prices are still high. Not at [Russia-Ukraine] war levels but still high. Scrap seems to be still strong, but market is not ready to accept current high prices which is not workable for mills.”
One long steel distributor in the Benelux region expected prices to remain stable during February. “Demand is overall too weak, for prices to be able to increase.”
Platts assessed European medium sections price (category 1, S235 JR) unchanged week on week on Feb. 7 at Eur780/mt ($840/mt) delivered, according to S&P Global Commodity Insights data. Platts assessed Northwest Europe Rebar down Eur2.50/mt week on week at Eur632.50/mt ex-works.
On the flat steel side, sources reported strong prices, though trading activity in the European hot-rolled coil market remained muted. Platts assessed domestic prices for hot-rolled coil in Northwest Europe unchanged day on day at Eur745/mt ex-works Ruhr on Feb. 8.
The overall index for German inventory sentiment reflected that the market unanimously expected stock levels to remain stable during February. The index for the month stood at 50 points compared with 46.88 points in January.
The index for steel producers for February was at 50 points, compared with 37.50 points in January. The index for traders’ sentiment stood at 50 points, compared with 56.25 points for the previous month.
One European long steelmaker said while inventory levels were low, “everyone is waiting for prices to cut down”, so he expected inventory levels to remain stable at current levels.
The long steel distributor also expected inventory levels to remain stable at low levels “due to weak demand and near-term uncertainty regarding price direction.”
“The market is very quiet, buyers do not need material as they have enough coil in stocks,” a German service-center source said. “And prices are rather high now, distributors often struggle to transfer the rising prices to their clients.”
Production to fall
Market sources expected production levels to either be cut or maintain low capacities due to weak demand.
Some long steel producers had already cut production, sources said. The Benelux-based long steel distributor source also expected that mills might cut production levels during the month due to weak demand.
The index for production outlook was around at 38.75 points, compared with 46.88 points for January. The index for traders’ sentiment was 40 points, down from 43.75 points. The index for producers’ sentiment was at 37.50 points, down from 50 points as producers were more bullish regarding production activity than traders.


German states form ‘Stahlallianz’, demand safeguard extension
Representatives of the 11 German states home to steel mills met on Monday with federal economy minister Robert Habeck in Berlin to found a new national steel initiative.
The so-called ”Stahlallianz” intends to combine the common interests of the states, most of them represented by their minister presidents, in order to form one voice to the federal government. They are essentially asking the government for strong support for the domestic steel industry, in view of future investment prospects.
In its statement, the alliance highlights European safeguard measures against imports as a key theme. It asks the German government to advocate at EU level for an extension until mid-2026, “to prevent a diversion of trade routes that distorts competition”.
At the national level, the partner states address high costs for power and the resulting disadvantages in international competition. They approve the Berlin government’s decision to lower the electricity tax for manufacturing industries, but caution this is not sufficient. They maintain their demand, for example, for a stabilisation of grid fees and a period of bridge financing of electricity for power-intensive industries (see Kallanish passim).
Another main theme is the technical transition following last year’s court decision that blocked €60 billion ($66 billion) in reserve funds from the Covid period from being used to de-carbonise industrial processes. In that context, the alliance highlights the importance of medium-sized companies along the production chain, which must not be overlooked for public support. That point was earnestly addressed earlier by WSM, the federation of steel-using industries.
The alliance consists of Baden-Württemberg, Bavaria, Brandenburg, Bremen, Hamburg, Lower Saxony, North Rhine Westphalia, Saarland, Saxony, Sachsen-Anhalt and Thuringia.
Christian Koehl Germany


German steel product sales and stocks dip amid manufacturing slowdown
Steel product sales in the German distribution and stockholding system totaled 776,079 mt in July, down 0.7% from a year earlier, German steel stockholders’ association BDS reported Aug. 22
The July total was down 6.5% from the 829,612 mt sold in June, as the slowdown in German industrial production and weak demand weighed on the market.
Germany’s industrial output fell for a second consecutive month in June, with a drop of 1.5% on a monthly basis, worsening from the previous month’s dip of 0.1%.
Within the overall sales figures, monthly sales of long products totaled 244,917 mt, down 6.4% year on year and little changed from the prior month. Monthly sales of flat products were reported at 476,850 mt, up 3.9% on the year but down 9.1% on the month.
Weaker demand from stockists was also evident in the monthly steel inventories which fell 11.8% on the year to 2 million mt. Stocks of long products were reported at 684,005 mt, down 14.3% on the year and 2.1% lower on the month, while those of flat products were reported at 1.29 million mt, down 10.7% on the year but up 5.9% on the month.
Platts, part of S&P Global Commodity Insights, assessed domestic hot-rolled coil prices in Northern Europe at Eur635/mt ex-works Ruhr Aug. 21, down 35% since March 30.
Author: Euan Sadden
Germany’s Saarland steel sector to use 200,000 mt/year green hydrogen
Green steel production in Germany’s Saarland state could require up to 200,000 mt/year of renewable hydrogen, the head of Saarland’s hydrogen agency Bettina Hübschen told S&P Global Commodity Insights in a recent interview.
The steel industry in Saarland could account for 150,000-200,000 mt/year of hydrogen, while a further 100,000 mt/year of demand could come from other industry, Hübschen said.
“A lot of companies are now considering switching their production from gas-based heating or from gas-based other processes to either electrification or hydrogen,” Hübschen said. Depending on technological constraints, the switch to hydrogen “is a much smaller investment, because they just need to exchange the burner technology and not the whole furnace.”
Saarland offers a case study of how the steel sector is moving to decarbonize operations, integrating with renewables, gas networks and other potential hydrogen users.
The state is home to Saarstahl and Dillinger steel plants, both owned by holding company Stahl-Holding-Saar (SHS).
SHS is Germany’s fourth-largest steel producer by volume, with annual output of 5 million mt, according to a company presentation.
SHS is planning a 2.5 million mt/year direct-reduced iron plant at Dillinger, which would use large volumes of hydrogen, Hübschen said.
SHS’s production is based on traditional blast furnace technology, although the company has said that by 2030 it wants to produce 3.5 million mt — around 70% of its total output — with lower emissions.
The Saarland Hydrogen Agency was established in May as a state subsidiary, and Hübschen is building a team to develop and implement the state’s hydrogen strategy, starting with a local demand analysis.
The focus is to develop hydrogen projects along the value chain, with infrastructure to connect supply and demand nationally and across borders, and steel plants will be the major offtaker for renewable hydrogen in the region, Hübschen said.
“They have their targets they need to fulfill, and they need to be climate neutral by 2045, and they need to have a certain reduction by 2030 already,” she said. “They can only do it by either cutting production or by switching to hydrogen.”
Coal history
The region in the southwest of Germany, bordering France, is home to a number of coal-fired power plants, and shares existing gas pipeline infrastructure across the border.
Hübschen said the former coal plants made good sites to develop for clean hydrogen production, with high-capacity power grid connections, designation as industrial sites and access to water.
Several gas transmission operators are working on a planned 100-km hydrogen pipeline network, comprising around 70 km of repurposed gas pipes and 30 km of new hydrogen pipelines, to connect the Saar region with France’s Grand Est and Luxembourg.
The MosaHYc (Moselle Saar Hydrogen Conversion) pipeline will transport up to 20,000 cu m/hour (60 MW) of pure hydrogen, connecting regional clean hydrogen production with industrial offtakers in the area, converting pipelines to link the German towns of Perl and Voelklingen with Carling and Bouzonville in France.
Several hydrogen projects in Saarland have applied for state aid under the EU’s Important Projects of Common European Interest scheme, including SHS’s H2SYNgas project, STEAG’s HydroHub Fenne electrolyzers and the TraficHdeux transport infrastructure project.

Hydrogen supplies
Meanwhile, French green hydrogen production company Lhyfe is to develop a 70-MW renewable hydrogen plant in Perl, producing up to 30 mt/d to be delivered into MosaHYc.
However, Hübschen acknowledged that the region would have to import substantial volumes of hydrogen to decarbonize industry while electrolytic hydrogen production ramped up in the coming years.
Local hydrogen supplies from 10-50-MW electrolyzers backed by solar and onshore wind power would play a “niche” but important role, as it would take time to build large-scale supply infrastructure, she added.
Hydrogen supplies are expected to come online around 2027-30, with the price paid highly dependent on the structure of contracts to be negotiated, she added.
Steel decarbonization
Hydrogen is used to convert iron oxide into metallic iron, replacing natural gas in the DRI process. Blast furnaces, by contrast, use mainly met coke and other coal-based fuels to convert iron ore. Metallic iron products are then processed into steel.
SHS plans to decarbonize progressively by 2045, commissioning its Dillingen DRI plant by 2030 and using two electric arc furnaces in Voelklingen and Dillingen with around 3.5 million mt/year crude steel capacity, and closing one blast furnace, with CO2 emissions reductions of around 55%. Hydrogen demand in this phase could be 55,000 mt/year.
The company plans to commission a third EAF by 2045 at the latest, with capacity of around 1.2 million mt/year of crude steel.
Hübschen said the upfront investment costs for steel plants to switch to DRI and EAF processes were high, in the region of Eur1 billion ($1.1 billion) for a DRI plant, plus there was a large cost arising from hydrogen purchases.
“They need to invest billions of euros to be hydrogen ready and then to pay a high price for the hydrogen,” she said.
Platts, part of S&P Global Commodity Insights, assessed the cost of producing renewable hydrogen via alkaline electrolysis in Europe at Eur5.91/kg ($6.46/kg) Aug. 14 (Netherlands, including capex), based on month-ahead power prices. Proton exchange membrane electrolysis production was assessed at Eur6.96/kg, while blue hydrogen production by steam methane reforming (including carbon, CCS and capex) was Eur2.95/kg.
Hübschen noted blue hydrogen could be an option for Germany, and while French nuclear-powered hydrogen production would not be acceptable to German steel producers, nuclear electricity generation could power German EAFs.
Platts assessed Northwest European hot-rolled coil carbon-accounted steel at Eur735/mt ($803/mt) ex-works Ruhr, down from a peak of Eur885/mt at the start of July. The Platts European carbon-accounted assessment is for HRC with a maximum of 2.1 mt of carbon emissions through steel production and from the supply and processing of feedstocks, covering Scopes 1, 2 and 3.
Author James Burgess