


German steel groups criticise IAA proposals
Germany’s steel association Wirtschaftsvereinigung (WV) Stahl and workers union IG Metall have criticised the Industrial Accelerator Act (IAA) proposal presented by the European Commission last week for failing to implement a general “Buy European” rule.
In contrast to other materials, namely aluminium and concrete, the Commission’s 25%-quota for carbon-reduced materials in public tenders stops short of seeking mandatory European origin for steel as well.
“War and protectionist moves have made Europe’s dependency in strategic regards painfully visible,” says managing director of WV Stahl, Kerstin-Maria Rippel, and IG Metall’s deputy chairman Jurgen Kerner. “Resilience of Europe’s economy is becoming a necessity for security,” they are reported as saying in a guest article in Welt.
The failure of linking the green steel quota to domestic sourcing “means a surrendering of Europe as a producer region,” which ultimately is “a political error of historic dimensions,” they conclude. They clarify that their claim “is not about raising walls, it’s about self-assertion.”
Pointing at the policies of the USA and India, they note that “only a naïve continent refrains voluntarily from linking demand to domestic production, to support its own strength.”
The country’s largest steelmaker, thyssenkrupp Steel, finds that the IAA helps imports more than it helps domestic steel. In its current draft, the proposal greenlights procurement from any overseas region. “That way, we support investment outside of Europe, rather than within,” the company’s ceo, Ilse Jaroni, says in a statement sent to Kallanish.
Meanwhile, the economy minister of state Saarland, Jürgen Brake, has called on the federal government to push the Commission for amendments of the proposal. Federal economy minister Katharina Reiche, too, has expressed criticism of the IAA, but mainly about the bureaucracy it causes. “This is the 50th proposal on domestic content, that comes on top of 49 others, which nobody can oversee anymore,” she is quoted as saying in Welt. She is reserved about requirement of buying European over concerns that it could drive away trusted international trade partners.
The additional bureaucracy that could come with European measures such as the IAA is also of concern to some steel using industries like the German mechanical engineering industry. Its association VDMA also questions local content requirements and warns that these could be an additional burden for its mostly medium-sized machinery builders (see Kallanish 5 March).


Italy scrap weakens amid uncertainty: Assofermet
March is expected to be a weak month for scrap purchasing in Italy. However, the new war scenario in the Middle East, continued weakness in finished steel sales and limited availability of quality scrap are preventing any clear forecast for March, according to a recent note by Italian trade association Assofermet.
The association notes that it will be necessary to closely monitor developments in finished product sales and, above all, production levels amid the prospect of rising energy costs linked to the new US-Iran conflict, for which repercussions remain highly uncertain.
In February, the market started off strong before stabilising later in the month. The first part of the month saw average price increases of around €15/tonne ($17.60/t), confirming the upward trend already observed in January. This pushed domestic scrap sales to high levels, allowing steel mills to cover their raw material requirements.
“Towards the end of the month, limited production schedules, the stagnation of the Turkish market and the further deterioration of the situation in the Middle East partly cooled the market and triggered the risk of further price reductions, which for now have not materialised,” the note states.
In the pig iron segment, there is increasing concern about the lack of alternative supply sources to Russia and Ukraine, which also face very high CBAM costs. At the same time, Brazilian producers are seeking higher prices in the first days of March.
These increases reflect a rapidly evolving geopolitical situation that is inevitably pushing up both energy and insurance costs, Kallanish notes.
“The entry into force of the CBAM regulation, difficulties in understanding the cost calculation mechanism, which varies depending on the origin of the material, and the fact that most steelmakers are already well stocked have weighed on new negotiations. This comes despite some signs of buying interest, particularly for Brazilian pig iron, for which CBAM cost is expected to be lower than that of other sources,” Assofermet concludes.
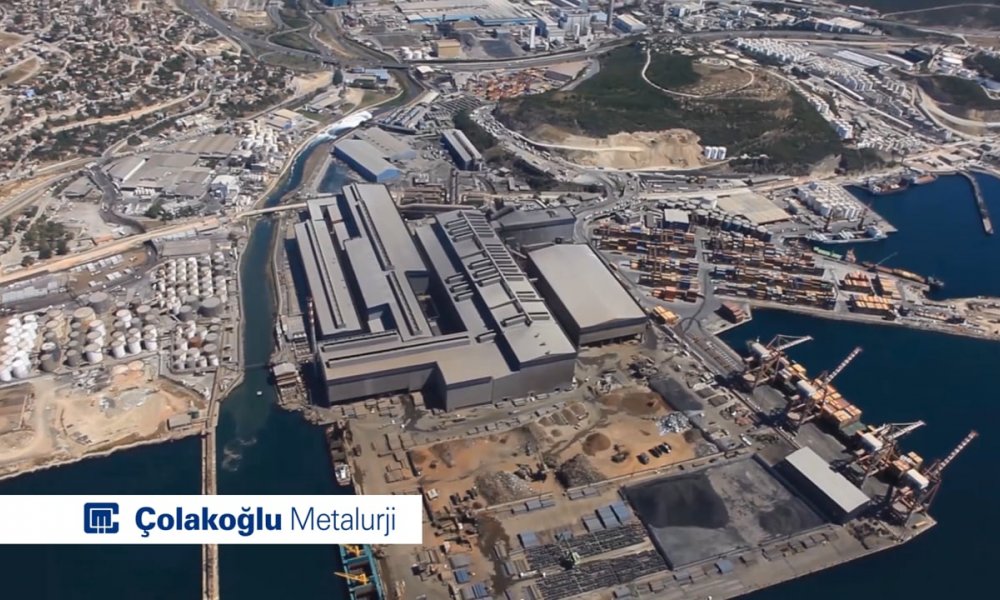
Primetals Technologies modernized Çolakoğlu Metalurji’s electric arc furnace


Turkish Koç Group has partnered with the Swedish green steel producer Stegra

Türkiye’s ‘Made-in-EU’ recognition bodes well for steel: Uğur Dalbeler
The European Commission’s proposal to grant Türkiye, among other partners, trusted partner status as part of the “Made in EU” mandate for various items, including electric vehicles, bodes well for Türkiye’s position in future EU steel trade negotiations. So says worldsteel chair and Turkish Steel Exporters’ Association vice president Uğur Dalbeler.
As announced by the Commission during its presentation of the Industrial Accelerator Act last week, the local content mandate will apply to aluminium, cement, electric vehicles and their components, batteries, battery energy storage systems (BESS), solar PV, heat pumps, wind, electrolysers, and nuclear technologies. It will not apply to steel, with the forthcoming steel trade regime, due to come into force from July, considered sufficient to restrict imports.
For the time being, Türkiye remains subject to EU safeguard quotas, with the long-term future of these measures uncertain, Dalbeler, also chief executive of Colakoglu Metalurji, tells Kallanish.
He argues that Türkiye should be assessed differently within the EU framework due to its deep economic integration with the bloc through the EU-Türkiye Customs Union and earlier arrangements linked to European coal and steel cooperation structures. Industry representatives are currently working with national authorities and seeking further engagement with the European Commission to advance discussions on a differentiated approach.
Dalbeler also raises concerns regarding how emerging EU carbon mechanisms evaluate Turkish steel production. Default emission values assigned to Türkiye appear significantly higher than those applied to countries such as Japan or South Korea. This is despite the fact that roughly 75% of Türkiye’s steel production is based on scrap-fed electric arc furnace technology, which is widely recognised as a lower-emission production route.
Closer cooperation between the EU and Türkiye could support Europe’s decarbonisation goals. While the EU has limited scrap-based flat steel capacity, Türkiye hosts several facilities capable of producing flat products using EAF technology. Producers such as Colakoglu, Tosyalı, and Habaş operate such facilities, although trade barriers and policy uncertainty often limit their ability to fully utilise capacities.
Dalbeler notes that expectations surrounding hydrogen-based steelmaking are gradually becoming more cautious. While hydrogen was initially presented as a key solution for decarbonising steel production, many policymakers now acknowledge it may not be scalable in the near term.
Renewable-energy-based solutions also face infrastructure constraints. As a result, iron ore-based production will continue to play an essential role in global steelmaking for the foreseeable future.
Rather than attempting to rapidly replace existing technologies, Dalbeler suggests the industry should prioritise reducing emissions within current production systems. Several Asian steelmakers are already pursuing this strategy by investing in technologies designed to lower emissions from blast furnace operations.
Another structural challenge is the limited global availability of high-quality scrap. Although EAF production is widely regarded as the most environmentally efficient steelmaking route, scrap supply remains insufficient to fully replace iron ore-based production.
Most scrap is already consumed in long steel production, both in Europe and globally. Flat steel production, particularly for manufacturing industries, therefore continues to rely heavily on iron ore.
Dalbeler also warns against the growing trend towards protectionist trade policies in the steel sector. Safeguard measures and tariffs have become increasingly common, even though such instruments were originally intended to be temporary under WTO rules.
Nevertheless, the current wave of protectionism may eventually normalise, as the economic consequences become clearer. Excessive protectionism can raise costs for downstream industries and contribute to inflation, which governments are simultaneously trying to control.
Industrial production has historically been based on specialisation and economies of scale, making full localisation of supply chains unrealistic.
Despite the challenges, discussions between Turkish industry representatives and European institutions are continuing. The aim is to ensure that Türkiye’s role as a major supplier of relatively low-emission steel to Europe is properly recognised within evolving EU industrial and climate policies.
“Türkiye and Europe are already deeply integrated. Recognising that reality would benefit both sides as the steel industry moves towards a lower-carbon future,” Dalbeler concludes.

Digitalisation enables transition, data transparency needed: Primetals’ Herzog
The big hype seen around digitalisation last decade has gone, but digital processes will be critical in supporting the steel industry’s transition to electric arc furnace-based steelmaking, as well as ensuring scrap quality and closed loop systems. Transparency in the sharing of data will be crucial. Artificial intelligence will meanwhile play an increasing role in process automation, but the human component will remain indispensable.
So said Primetals Technologies head of industrial digitalisation Kurt Herzog during an exclusive interview with Kallanish at the technology supplier’s flagship location in Linz.
Europe an old hand at digitalisation
There was a time when people believed big data would solve many problems in manufacturing, but how to utilise this data is the critical next step to ensuring improved industry performance.
European steelmakers have been integrating digital processes in production for decades, but their often tailor made software is ageing and the people who developed it are retiring. “So, maintenance of the software is a huge issue,” Herzog said.
Compared to China, whose approach is build huge data infrastructure, collect data and then “start thinking about what to do with the data”, Europe says: “There is already a lot [of data available]. How can we expand that, and how can we generate the quick benefit of everything we are doing?” he asked.
Digital processes support competitiveness but software investment hesitant
In the current low-margin steel industry climate, digitalisation can support steelmaker competitiveness and reduce cost per tonne.
“How often is a slab produced with a defect which is not detected or considered, but it’s still going through the rest of the production process, and at the end, the final product needs to be scrapped? There is a huge amount of energy and other costs to finalise this product, although I know the slab is not good,” Herzog noted.
Digital tools can be used to implement counter actions, to, for example, repair the product, reassign the slab to another customer, or scrap the slab if it is deemed unusable.
Intralogistics are another important digitalisation lever. This may “sound rather boring” but digital processes can help navigate the “trade off” between mills wanting to offer short delivery times but therefore needing to have sizeable material in stock, “which comes with a lot of money, bound capital”, he continued.
However, while mills are spending big sums on the equipment, they hesitate to spend relatively smaller sums, amounting to a low one digit percentage of the asset cost, on the right software solution to ensure the best use of the hardware and return on investment, he noted. “There is a KPI when equipment is bought, which is, what’s the cost per tonne of equipment? It’s a KPI that’s hardly applicable to software, and that’s the traditional thinking in the steel industry,” Herzog said.
Production route transition neutralises human knowhow
Digitalisation will also support the process of steelmaking decarbonisation in two ways, directly and indirectly, as an enabler. Directly, it can optimise the production process to, for example, reduce fuel consumption, or increase the yield by better steering the product quality along the production chain – these result in a reduction in carbon footprint.
“If I have to cut off pieces, because the quality is bad, the CO2 footprint of these cut off pieces is projected to the sellable [steel] pieces,” he noted. Quality control can ensure the amount of sellable products “stays high or gets higher by early identification of quality issues and recommending counter actions”.
These measures provide a quick return on investment but their scope for emissions reduction is limited. The indirect support provided by digital processes enables production route transition, which yields the biggest emissions reductions.
“Is an operator of a blast furnace capable to operate the direct reduction plant? No. Is a BOF operator capable to operate an electric arc furnace? No. So all the experience collected in the past, the value is zero. I mean, they are still operating those aggregates in the transition phase. But for the electric arc furnace, the value is not there. So what digitalisation can do is support operations in operating these new plants by providing a high degree of automation, digital assistant systems, that the high level of skills to operate these aggregates is not that necessary,” Herzog noted.
Moreover, it can provide training simulators to prepare teams to operate new plants, he added.
Hybrid BF-EAF operation presents a challenge
The combined operation of BOFs and EAFs on the same steelmaking site, a scenario envisaged at some European mills, including voestalpine, in the coming years, will require heavy support from digitalisation due to the challenges of planning and scheduling in this hybrid model.
“You cannot produce – if it’s a scrap based electric arc furnace – all the steel grades you can produce on the BOF … What is produced on the electric arc furnace, what is produced on the BOF? How not to break casting sequences, how to manage transitions, product transitions … If a steel grade can be produced on a BOF and the electric arc furnace, where is the lowest price of production? Is it on the arc furnace or on the BOF?” Herzog pointed out.
“Scheduling this hybrid production, managing this hybrid production from a timing point of view and the quality point of view is something where, I think, if you want to have a certain flexibility, it is not manageable by humans. This cannot be done by Excel. You need some very elaborate digital tools to manage this production,” he added.
AI will drive automation but human element remains
Artificial intelligence will not have complete autonomy over the production process because it cannot be trusted to avoid making a critical mistake. “Generative AI is something that will be implemented or used in support functions. When it comes to production, I still believe that data analytics will be the major lever to better understand the processes, and based on this analysed data, consistent decision making will support, or will happen in the production,” Herzog said.
Individual decisions made today by operators or process engineers every 30 minutes regarding, for example, needing to increase or decrease the coke rate in the blast furnace, can be defined by humans and then automated.
“If you digitise the knowhow of your best operator, in this way, your best operator defines how decisions are made. And this is automated. This means your best operator is on duty, 24/7, and by analysing the results of these decisions with AI tools, you can even improve this decision-making, and that’s where I see that the benefit will be generated in the next decade,” he noted.
“But when it comes to really steering, controlling the production, I think that there will always be this, call it intermediate step, which is still understandable by humans. Otherwise, I think it will not be acceptable,” he continued.
Scrap treatment, closed loop systems gain importance
A lot of research & development is already being done in Europe into solutions that ensure the removal of residuals from scrap so that the material is the right quality, but that costs are kept down. This involves metallurgical models on EAFs that make pre-calculations. “So I need to … simulate before I start to charge the furnace. Okay, what does this input material mean for the quality of the final product and optimise them? This is definitely something that will be necessary,” Herzog suggested.
One way to support this is ensuring data travels with the steel product all along its life cycle, from producer to end user. If 50 metres of a 200-metre coil have quality issues, the provision of the data to the buyer means he can cut off the defective section, not pay for it, and use the rest.
“The scrap would be sent back, which has the beauty that the scrap is well defined – if data travels back with the scrap. So if the steel producer knows exactly what the composition of the scrap is, it’s good to be used in the electric arc furnace,” he said.
Supplying transparent data does have its challenges, however. “Steel producer and car producer could jointly optimise the production process or the product specification. There would be huge potential, but sharing too much data risks intellectual property. So there are challenges; if these can be solved in an elegant way, in a feasible way, in the sense that both parties can live with it, I think that there will be huge potential,” Herzog concluded.
Auto a key market to drive steel decarbonization: SteelWatch Published by: Alesha Alkaff
The auto industry is well positioned to accelerate the use of lower emissions steel and automakers are increasingly using the material to boost competitiveness in the electric vehicle (EV) market, according to a global climate-focused watchdog.
“We’re in the beginning of a new era where green premiums and market demand are beginning to support the first wave of green or low-emissions steel,” Roger Smith, Asia lead at non-governmental organization SteelWatch, told Fastmarkets on Friday March 6.
The auto sector is a key sector for the decarbonization of the steel industry because of its ability to support a green premium, Smith said. He estimated a 20%-30% premium per tonne of green steel produced by hydrogen-based direct reduced iron (DRI) compared with traditional coal-based blast furnace steel.
The effect on the final price of an automobile is minimal, typically adding “a few hundred dollars” to the cost of the vehicle based on the vehicle weight and the amount of steel used, Smith explained.
Automakers are increasingly using low-carbon steel and aluminium to increase competitiveness in new EV models, according to the fourth edition of the Lead the Charge Auto Supply Chain Leaderboard report.
The leaderboard ranks and assesses the supply-chain sustainability of 18 carmakers globally, including Tesla, Ford, Volvo, Mercedes and Hyundai.
The report, published on Wednesday March 4, showed that demand for green steel among automakers has increased in recent years. The number of automakers taking action to decarbonize the steel used in their vehicles rose from 7 out of 18 in 2023 to 13 out of 18 in 2026.
The analysis was published by a network of climate, human rights and investor groups, including SteelWatch.
“The Lead the Charge leaderboard is only a few years old. At the beginning, most companies scored 0 on the steel section. There was really no procurement, no talk about procuring low-emission steel and that’s changed,” Smith said.
“Today, green steel is likely getting used in what [automakers] see as the greenest cars. [Automakers] ultimately need to transform their production of everything that they make,” Smith said.
The volume of steel consumption in the auto sector is large enough to support new green steel projects, spurring scalability and long-term offtake commitments for low-carbon steel, Smith added. “That’s what’s going to actually get new facilities built and become investable.”
“The demand for genuine green steel continues to grow,” the report said. “Automakers such as BMW Group, Mercedes-Benz AG, Volkswagen and Volvo Group are continuing to stick with credible sources of green steel.”
What automakers around the world are doing
Tesla, the largest producer of EVs in the US, disclosed that it is “working with mainstream steel mills for a mid-term transition away from blast furnace production and toward direct reduction without coal that will systematically reduce emissions,” the report said.
Asian automakers Hyundai and Kia disclosed intentions to expand their use of low-carbon steel but did not provide additional details, according to the report.
Notably, Hyundai has begun mass production of lower-emissions steel sheet at its Dangjin plant in South Korea, Fastmarkets reported in February.
In the US, Hyundai’s integrated electric-arc furnace (EAF) facility in Louisiana is under construction and scheduled to begin production in 2029, specializing in automotive steel sheets.
In Europe, Volvo published a paper on sustainable steel outlining the challenges in steel decarbonization and how the Sweden-based company intends to use its leverage to address those challenges.
Meanwhile, German automaker Mercedes has signed multiple offtake agreements for low-carbon and fossil-free steel and aluminium across several regions and has disclosed specific quantities for some of these agreements.
“To remain competitive, other automakers must disclose disaggregated emissions and sourcing information on their steel, aluminium and battery supply chains,” Abhilasha Bhola, director of the Auto Supply Chain Campaign at nonprofit group Public Citizen, said.
Decarbonization technology already exists, raising scalability question
Technology to produce low-carbon steel already exists, Smith said, highlighting the DRI steelmaking route, which reduces carbon emissions by replacing coal with cleaner gases. The cleaner the reducing gas, the lower the emissions.
For example, Swedish joint venture Hydrogen Breakthrough Ironmaking Technology (HYBRIT) aims to replace coal with fossil-free electricity and green hydrogen.
The collaboration was launched in 2016 by steelmaker SSAB, iron ore miner LKAB and energy company Vattenfall.
As of early 2026, the project has demonstrated the technology and is extending pilot operations for hydrogen storage to prepare for full-scale industrialization, targeting commercial-scale production by 2027.
The challenge, Smith said, is scaling the technology to produce low carbon steel at a commercial scale.
“Some of the real lead markets for purchasing low-emissions steel include the automotive sector, the tech sector and even some of the construction industry. I think that’s enough to get a first wave of projects globally,” Smith said. “The real question then is, how do they take that to scale?”
A key component in scaling decarbonization operations is government incentives, Smith said, which can really play a role in helping build those markets and put a price on emissions.
The European Commission (EC) approved €200 million ($232 million) in grants to strengthen the EV supply chain in Spain in early February.
The funding aims to accelerate the production of EV batteries and energy storage, as well as hydrogen technologies, according to Teresa Ribera, executive vice president for Clean, Just and Competitive Transition at the EC.


Rising production costs, limited imports sustain European domestic HRC uptrend
European domestic hot-rolled coil prices extended gains on Monday March 9 as difficult import conditions reduce competitive pressure, while growing cost burdens continue to underpin mills’ pricing strategies.
In Northern Europe, most recent deals for HRC were said to be varying within the range of €690-710 ($800.83-824) per tonne ex-works with “most reported indications clustering around €700–710 per tonne ex-works”.
This is when at the end of the last week sellers said that they were getting their first orders at €700 per tonne ex-works.
A source on sellers’ side said that, despite general demand situation leaving much to be desired, there are more buying intentions now than in the previous weeks.
Meanwhile, a buyer source said that freight problems and delays in delivery terms diverted customers’ interest from import material to domestic supply even more, which was already a case following the introduction of the Carbon Border Adjustment Mechanism and looming changes in safeguard system.
Fastmarkets’ daily steel hot-rolled coil index, domestic, exw Northern Europe was €701.46 ($814.14) per tonne on Monday, up by €1.14 per tonne from €700.00 per tonne on March 6.
The index was up by €8.96 per tonne week on week and by €48.13 per tonne month on month.
Similar tendency was noted in the Italian market, with workable level gradually moving from €680 per tonne ex-works to €680-700 per tonne ex-works.
“In Southern Europe, €700 per tonne base is starting to be established in new deals, as US-Iran conflict impact on freight costs and logistics along with tighter safeguard measures from July 1, 2026, reduces interest in imports,” a buyer source said.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €685 per tonne ex-works on Monday, up by €4.17 per tonne from €680.00 per tonne on March 6.
The index was also up by €8.75 per tonne week on week and by €40.00 per tonne month on month.

Polish long steel producers withdraw offers amid cost uncertainty; rebar prices increase
Polish rebar and wire rod producers withdrew offers from the market over the week to Friday March 6 amid mounting concerns with rising costs for energy, especially for gas, and for raw materials, Fastmarkets heard.
According to market sources, assessing current market levels for Polish long steel products remains challenging following the recent escalation of the conflict in the Middle East, which has had a cascading impact on international markets.
“What I hear from the market is that steel mills do not want to show offers while they check the situation with energy and raw materials,” a source said, adding that freight costs are also increasing because of the conflict.
As of Friday afternoon, Fastmarkets heard that several producers had withdrawn their offers from the market. Another source said that everything “got crazy” during the week, with mills not giving any offers or looking to cancel current orders.
During the week, offers for rebar were reported at around 2,670-2,820 zloty ($723-763) per tonne CPT, but sources said that they were later withdrawn. Despite that, some sources indicated that current mill delivery times remain around four weeks.
Some market participants expect that producers might soon re-enter the market with higher offer levels because of shifting geopolitical dynamics and rising uncertainty, Fastmarkets heard.
Meanwhile, other market participants said that while demand levels in the country remain low, there are some early signs that the situation is beginning to improve after months of cold weather.
“The weather is improving and construction sites are also ordering, so I expect that the demand for rebar will also increase — but right now I can confirm that trading activity is still slow,” a source said.
Despite reports of low liquidity in the market, some rebar transactions by stockists were reported at 2,700 zloty per tonne CPT on Friday.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar) domestic, cpt Poland was 2,550-2,700 zloty per tonne on Friday, widening up from 2,550-2,600 zloty per tonne in the previous week.
Meanwhile, drawing quality wire rod price levels remained unchanged, with no new trading reported during the assessment period.
Fastmarkets’ weekly price assessment for steel wire rod (drawing quality), domestic, delivered Poland was stable week on week at 2,700-2,780 zloty per tonne on Friday.

Volvo expands SUV production with SSAB Zero
Volvo Cars is using SSAB’s Zero Steel material in the production of its electric SUV.
The auto maker is seeking to increase production volumes for the fully electric vehicle known as EX60 in 2026 on the back of strong customer demand in Sweden and other key markets such as Germany, Kallanish hears from the carmaker.
According to SSAB, the agreement, signed last year, made Volvo the first automaker to commit to using decarbonised steel in serial production.
While Volvo is currently only taking orders for the vehicle in Europe, it hopes to open the order book in the US later in spring.
Volvo Cars is now planning an increase in production of the EX60 at its Torslanda plant in Sweden. The company is currently engaged in a dialogue with relevant labour unions, with the aim of keeping the Torslanda open for one extra week in the summer. This would be the first time in the company’s history, it notes.