


Steel heavy plate demand stays limited across Europe as Italian slab import prices move higher
European steel heavy plate prices were largely unchanged this week, with Italian mills reporting steadier sales despite ongoing weak demand. Meanwhile, slab import prices into Italy increased on firmer Asian offers, lifting the market higher week on week, sources told Fastmarkets on Thursday October 8.
Italy
In Italy, a producer said it was selling more regular volumes of base-grade plate in the market during the last 10 days, closing deals at €750 ($840) per tonne ex-works even for bigger orders of 500-1,000 tonnes.
The same source also said they achieved some project-related deals for the rest of the year and early 2027 at €780-790 per tonne ex-works for base-grade plate, but these were discarded from Fastmarkets spot price assessment.
Meanwhile, a trader said that €740 per tonne ex-works was still possible to achieve in the market, while €750 per tonne ex-works was “the maximum deal price.”
A second trader said workable levels for plate were at €730-750 per tonne ex-works on Thursday, but the lower end of the range was not strongly corroborated among other market participants, therefore it was not included in the final assessment.
As a result, Fastmarkets’ weekly price assessment for steel domestic plate 8-40mm, exw Southern Europe was €740-750 per tonne on Thursday October 8, stable week on week.
Slab import prices into Italy increased week on week, with latest offers from China heard at $590-595 per tonne cost, insurance and freight (CIF). Indications of workable levels were reported in the same range, which was higher than those heard in the market at $580-590 per tonne CIF on October 1.
Chinese mills were slowly returning to the market after public holidays, which took place on October 1-7, so no active deals happened during this period, sources said.
“Unlike the period of active bookings some 2-3 weeks ago, today I can’t confirm that they [Chinese mills] still accept $580 [per tonne CIF] after negotiations,” a buyer said.
Meanwhile, Vietnamese mills were heard offering material to Italy at $530 per tonne free on board (FOB), which is equivalent to around $600 per tonne cost and freight (CFR) after adding freight of $70 per tonne, a trade source said, but no transactions were confirmed at these levels yet.
Fastmarkets’ weekly price assessment for steel slab import, cif Italy was $590-595 per tonne on Thursday, up from $580-590 per tonne a week earlier.
Northern Europe
In Germany, sources indicated workable levels for base-grade plate at €850-880 per tonne ex-works, unchanged from a week earlier. No major buying activity was reported during the week, as mills were offering longer delivery times, a trade source said.
A second trade source said levels for plate in the Benelux area were within €840-860 per tonne ex-works, saying the commodity market was “lousy”. The same source added that German mills were well booked, while Benelux mills were “hungry for commodity”.
Thus, Fastmarkets’ latest weekly price assessment for steel domestic plate 8-40mm, exw Northern Europe was €840-880 per tonne on October 8, widening downward by €10 per tonne from €850-880 per tonne on October 1.


Italian rebar producers maintain upward pressure on prices amid elevated costs, weak demand
Italian rebar prices narrowed upward on Wednesday, October 7, with producers continuing to push for higher price levels in response to elevated oil and energy costs, while demand remained subdued across the region.
Market participants noted that recent price increases have been driven primarily by production cost pressures rather than any meaningful improvement in consumption.
“Demand remains very weak, while energy and diesel costs show no signs of decreasing. This issue is becoming increasingly significant as we are also seeing a general contraction in national consumption,” a buyer source told Fastmarkets.
High living costs and elevated prices across multiple sectors were said to be affecting purchasing power.
The construction sector also remained under pressure despite ongoing infrastructure activity.
“Despite the presence of a significant number of ongoing public infrastructure projects, the high cost of raw materials and energy is making it difficult for construction activity to progress at a fast and consistent pace. At the same time, residential construction activity remains significantly down,” a market participant said.
In Italy, indications were heard across a wide range, depending on the region. In the North, workable levels were heard at €730-750 ($820-843) per tonne ex-works and €750-780 per tonne ex-works in Southern Italy.
Deals were heard at €740-760 per tonne ex-works, while offers were heard at €770 per tonne ex-works.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, exw Italy, narrowed upward to €730-780 per tonne on October 7 from €720-780 per tonne a week earlier.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, delivered Spain, remained unchanged at €750 per tonne on October 7.
Workable levels for Northern European rebar were heard at around €720 per tonne delivered.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, delivered Northern Europe, was €715-720 per tonne on October 7, narrowing downward from €715-730 per tonne the previous week.
Workable levels for Southern European wire rod were heard at €670-680 per tonne.
Fastmarkets’ weekly price assessment for steel wire rod (mesh quality), domestic, delivered Southern Europe, narrowed upward to €670-680 per tonne from €660-680 per tonne previously.
Meanwhile, Fastmarkets’ weekly price assessment for steel wire rod (mesh quality), domestic, delivered Northern Europe, was unchanged week on week at €705-715 per tonne on October 7.

Cinzia Vezzosi: Companies have reached their limits, Europe now needs a competitiveness strategy
On the occasion of the autumn conference titled ‘Markets at risk and companies’ potential’ of Assofermet, the Italian association representing companies active in the steel, scrap and non-ferrous metals sectors, SteelOrbis interviewed the association’s president Cinzia Vezzosi about the main factors currently putting pressure on the Italian and European metals supply chain: from the risk of deindustrialization to new trade measures, from shrinking margins to the regionalization of supply chains, as well as the future of European scrap exports.
During the conference, Vezzosi identified the ability to react quickly as one of the key strengths of Italian SMEs, which are capable of adapting to change “in months, not years”. However, as emerged from the interview, companies’ ability to adapt may no longer be sufficient in an environment characterized by rising costs, increasingly stringent regulations and persistently weak demand.
In February, during EUROMETAL’s Southern Europe Meeting, you spoke of a “systemic” risk of deindustrialization and of the need to put competitiveness back at the heart of European policies. Several months later, do you see any signs of a reversal in this trend?
Unfortunately, no. In fact, I would say that the process of deindustrialization and relocation has now reached an even more advanced stage. The introduction of what we call, perhaps somewhat improperly, the “new safeguard measure”, with quotas being halved and the out-of-quota duty doubled, has further constrained companies’ ability to operate competitively.
This is making it increasingly difficult for companies to remain competitive in the domestic market and, consequently, in international markets as well. I therefore see no sign of a reversal in the trend; if anything, the situation is continuing to deteriorate.
Italian companies have shown a remarkable ability to adapt in recent years. However, with tariffs, geopolitical tensions, logistics, energy costs and new EU requirements, have we reached the point where this ability is no longer sufficient without structural measures to improve competitiveness?
Absolutely. Companies have essentially already done everything within their power. What is missing today is a broad-based strategy capable of genuinely restoring the competitiveness of the manufacturing sector and, above all, providing a sufficiently stable and predictable framework on which companies can base their planning and investment decisions.
Companies will certainly continue to respond and adapt, but there is one factor we can no longer ignore: margins have fallen to levels that are now materially limiting companies’ ability to invest. The willingness to invest may still be there, but, if the financial capacity to do so is no longer available, the issue becomes structural and ultimately jeopardizes the growth prospects of entire segments of the supply chain.
Another unusual feature of the current market is the disconnect between prices and demand: costs continue to rise while consumption remains weak. How much does this affect companies’ decision-making?
It is one of the most worrying aspects of the current situation. Traditionally, a market characterized by rising prices is also accompanied by stronger demand. Take, for example, metals traded on the London Metal Exchange: normally, higher prices also reflect stronger underlying demand.
Today, however, these two dynamics have become disconnected. Costs are rising while demand is weakening, and this is fundamentally changing companies’ expectations. When prices increase without being supported by consumption, it becomes much more difficult to pass higher costs downstream, protect margins and, above all, have sufficient confidence to plan new investments.
Supply diversification is often cited as one of the main responses to increasing geopolitical instability. However, given higher logistics costs, longer lead times and new regulatory constraints, to what extent is diversification really a solution?
We are entering a phase of increasing market regionalization, with supply chains increasingly tending to develop within specific geographical areas. However, the companies we represent had already made enormous efforts to diversify, building strong relationships over the years with suppliers and partners located far beyond the European market.
The issue today is not so much finding new sources of supply as making them economically sustainable. On the one hand, we ask companies to diversify; on the other, instruments such as CBAM and safeguard measures effectively restrict their ability to do so.
Companies are therefore faced with insufficient quotas, high costs, increasingly expensive logistics and longer lead times, all in a market where demand is already weak. Diversification can therefore increase resilience, but without adequate competitive conditions it risks becoming an additional cost burden.
Access to ferrous scrap has become a strategic issue for the decarbonization of the European steel industry. What is your view of the possibility of introducing further restrictions on exports to non-OECD countries? Could such measures increase raw material availability for European steelmakers?
In my view, no, because the material we currently export is not being taken away from European demand; it is material that the domestic market is unable to absorb. Europe collects almost 100 million mt of scrap, while ferrous scrap consumption amounts to approximately 78-79 million mt.
Restricting exports to non-OECD countries does not automatically create additional domestic demand. On the contrary, the risk is that it would reduce the value of the material and, consequently, the incentive to collect it. Some grades could become economically unviable to recover and process.
That would represent a very serious step backwards. Over the years, Europe has built an extremely efficient collection, sorting and recycling system, which is one of the most tangible examples of the circular economy. Restricting commercial outlets when there is insufficient domestic demand risks weakening the very system we have built over time.
And this is precisely the point: companies must continue to take responsibility for building their own future, but they must also be given the conditions needed to do so. If the mechanisms supporting collection, recycling and, more broadly, the competitiveness of the supply chain are weakened, it becomes increasingly difficult to translate that responsibility into investment and growth.
What is therefore needed is an economic and regulatory framework that provides companies with greater visibility and allows them to plan and invest with greater confidence.
Author: SteelOrbis Editorial Team

Norwegian Steel Association to hold course on steel and aluminium structures under extreme loads
The Norwegian Steel Association will offer an English-language course on “Behaviour of Steel and Aluminium Structures subjected to Extreme Loads” on 17 November 2026. Participants can attend at Thon Hotel Slottsparken in Oslo or join remotely via Microsoft Teams.
Developed by Magnus Langseth, Professor Emeritus at the Norwegian University of Science and Technology (NTNU), the continuing education course is offered in collaboration with the Norwegian Steel Association and DYMAT, the European research association focused on the dynamic behaviour of materials and its applications.
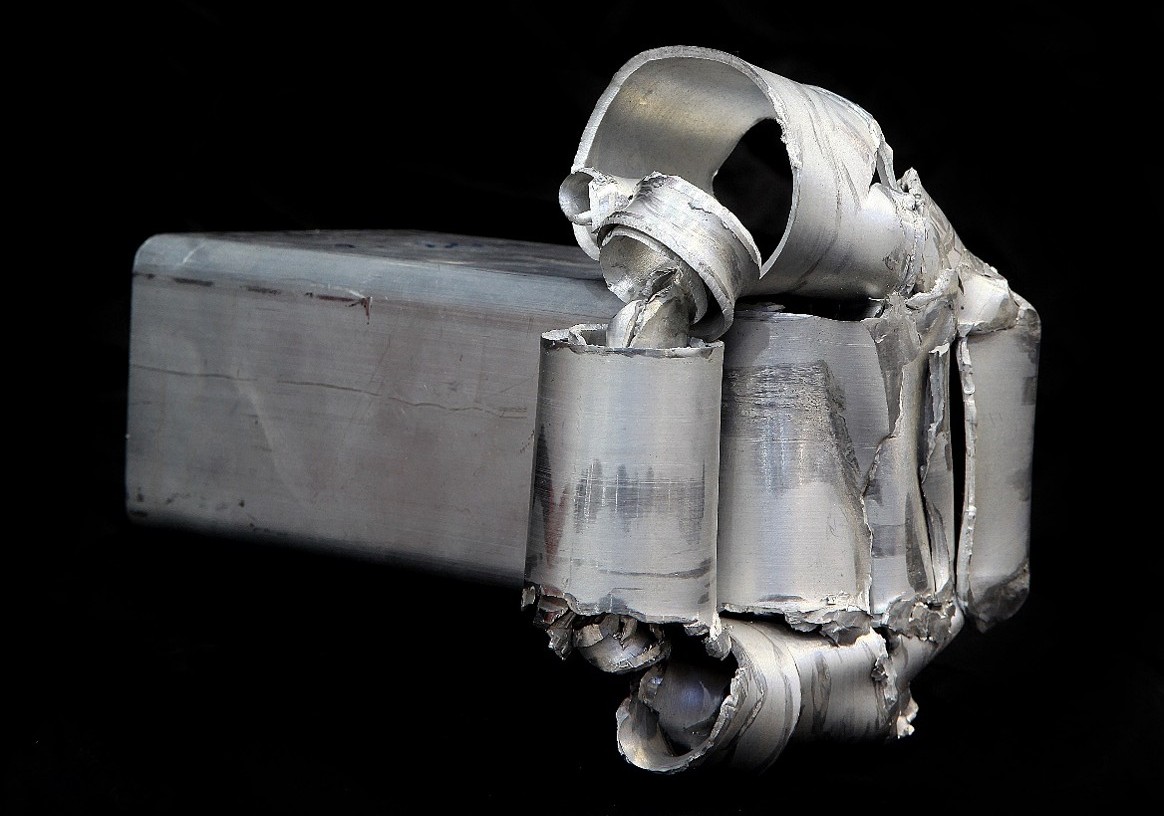
The course addresses structural response to extreme, short-duration loads associated with events such as industrial accidents, explosions, impacts and climate-related incidents. These loading conditions create particular challenges for engineers designing robust structures and protecting critical infrastructure.
Using basic examples, the course aims to explain how steel and aluminium structures respond to impact and blast loads. The knowledge is intended to support structural design, simplified calculations during early design stages and the assessment of numerical simulation results.
The course is aimed at professionals working in defence, protection, civil, mechanical, materials, naval, ocean and transportation engineering, as well as related disciplines dealing with impact, blast and high-rate loading. According to the organisers, participants with a mechanical or structural engineering background will benefit most from the specialised content.
Langseth’s research has focused on the impact behaviour and crashworthiness of steel and aluminium structures, alongside lightweight ballistic protection and structural response to blast loading. He previously directed the SIMLab and SFI CASA research centres at NTNU.
The course fee includes a digital technical compendium, the PLastic CApacity (PLCA) computer programme and copies of the presentations.
Registration closes on 12 November 2026 at 16:00.
Further details, the programme and registration are available on the Norwegian Steel Association’s course page.

7 Steel signs expanded rail transport deal
7 Steel has signed a new deal to increase the use of rail transport in its UK supply chain, Kallanish learns from the Wales-based steelmaker.
The steelmaker has signed an 11-year agreement with operator GB Railfreight to transport scrap steel into Cardiff and distribute finished products, including rebar and coiled steel, across the UK.
Vorn O’Hennessy, head of supply chain management, says: “Having a long-term logistics partner that understands our operation and can support the movement of both raw materials and finished products is important as we continue to plan for the future, and we look forward to continuing our partnership with GB Railfreight to deliver a reliable, efficient service for our customers across the UK.”
Purpose-built wagons and expanded rail operations will support a more efficient, resilient, and sustainable supply chain from October onwards, it adds.

German water levels remain critical in autumn
Germany’s waterways continue to suffer with low water volumes and levels. The bottlenecks for industrial transports on rivers, especially the Rhine, have not recovered by much, or only temporarily.
In fact, after record lows were seen in August for the Rhine, those values have been undercut at some locations along the river in September, according to the national water authority Bundesamt für Gewässerkunde. “An alleviation is not in sight in the first half of October,” it warns.
Rain has been forecast to fall in the coming days, “but too little and, too short to take sustainable effect on the levels of the national waterways.”
The raw materials supply and steel deliveries to and from the country’s largest steelmaker, thyssenkrupp Steel, on the junction of Rhine and Ruhr, remains problematic, the company tells Kallanish.
“Operation of our own barge fleet remains suspended. We keep chartering vessels from third parties with a lesser draught, which are able to go at low levels. On the basis of the measures we have taken, we can keep supplying customers. Our in-house low-water task force is continuously evaluating the impacts on deliveries and production,” the company says.
Other mills have transferred cargoes to freight trains. In order to maintain supply chains for coal and ore, private operator Captrain has provided additional transport capacities. Captrain was represented at the recent MBI Stahltag conference with a speaker on the overall potential of train operators for steel mills.
Since August, Captrain has been running three to four extra journeys per week between the port of Wilhelmshaven and the Ruhr, thus adding 4,000 tonnes of coal. It furthermore added four-to-five journeys for coke transport between Germany and France, with a total of 2,000t/week, the firm says in a statement.
Other local operators, too, have lifted their capacities for steel mills, according to information service Verkehrs-Rundschau. Rhein-Cargo, for example, is running additional trains for iron ore transports from Rotterdam to Hüttenwerke Krupp-Mannesmann (HKM) in Duisburg on the Ruhr.
Most scrap transport that needed to find alternatives will have been transferred to “trucks, trucks, trucks,” Sebastian Will of recyclers organisation BVSE told MBI Stahltag delegates.
The situation on the waterways has given the truck transport prices another push, in addition to the earlier increases during the year. Rates could inch towards €100/tonne ($111/t) for border-crossing steel routes like Italy-Ruhr, some market players say. According to a manager of a distribution company, the prices by August were still around €80/t. “I have not heard €100/t yet, but I would not be surprised,” he says.
EU construction growth to strengthen in 2027
EU construction output is expected to grow 1.5% on-year in 2026 and accelerate to 2.9% in 2027, following 1.3% growth in 2025, according to the European Steel Association (Eurofer) outlook.
Construction, which accounts for 37% of EU apparent steel consumption, continues to provide the strongest support for steel demand. The sector contracted 1.6% in 2024, despite support from NextGenerationEU-related schemes and monetary easing, before returning to modest growth in 2025.
Output growth slowed to 0.4% year-on-year in the first quarter of 2026 from 3.1% in Q4 2025, most probably reflecting the usual seasonal slowdown in construction activity during the first quarter, Eurofer says.
Growth should accelerate later in 2026 despite higher interest rates, before picking up more speed in 2027, thanks to a recovery in housing demand and a pick-up in infrastructure spending, the association adds.
Overall, EU steel-using sector output, measured by the Steel Weighted Industrial Production (SWIP) index, is forecast to grow 1.5% in 2026, following a marginal 0.1% decline in 2025 and a 4.1% contraction in 2024. Growth is expected to accelerate to 2.5% in 2027, supported by construction, mechanical engineering and a recovery in automotive output, Kallanish notes.
| Sector | 2021 | 2022 | 2023 | 2024 | 2025 | 2026f | 2027f |
| Construction | 6.2 | 3.3 | 1.9 | -3.3 | 1.2 | 1.8 | 2.9 |
| Mechanical engineering | 12 | 4.7 | 1.6 | -5 | -0.7 | 1.9 | 1.8 |
| Automotive | 6.1 | 5.4 | 8.8 | -9.6 | -4.1 | -0.9 | 3.5 |
| Domestic appliances | 12.6 | -4.6 | -4.5 | -4.9 | 0.8 | 0.3 | 0.8 |
| Other transport | 3.8 | 7.3 | 10.3 | 5.7 | 2.4 | 7 | 2.3 |
| Tubes | 10.3 | -1.3 | -1.4 | -2.4 | 0.1 | 1.3 | 1.2 |
| Metalware | 12 | 1.2 | -3.9 | -3.3 | -0.3 | 2.1 | 2.1 |
| Others | 12.1 | 3.9 | 2.8 | -1.6 | 2.5 | 1.6 | 1.6 |
| SWIP | 8.2 | 2.8 | 2.3 | -4.1 | -0.1 | 1.5 | 2.5 |
Source: Eurofer outlook September 2026, f = forecast
Author: Elina Virchenko

Klöckner agrees to sell Becker Group to Accura and BCB consortium
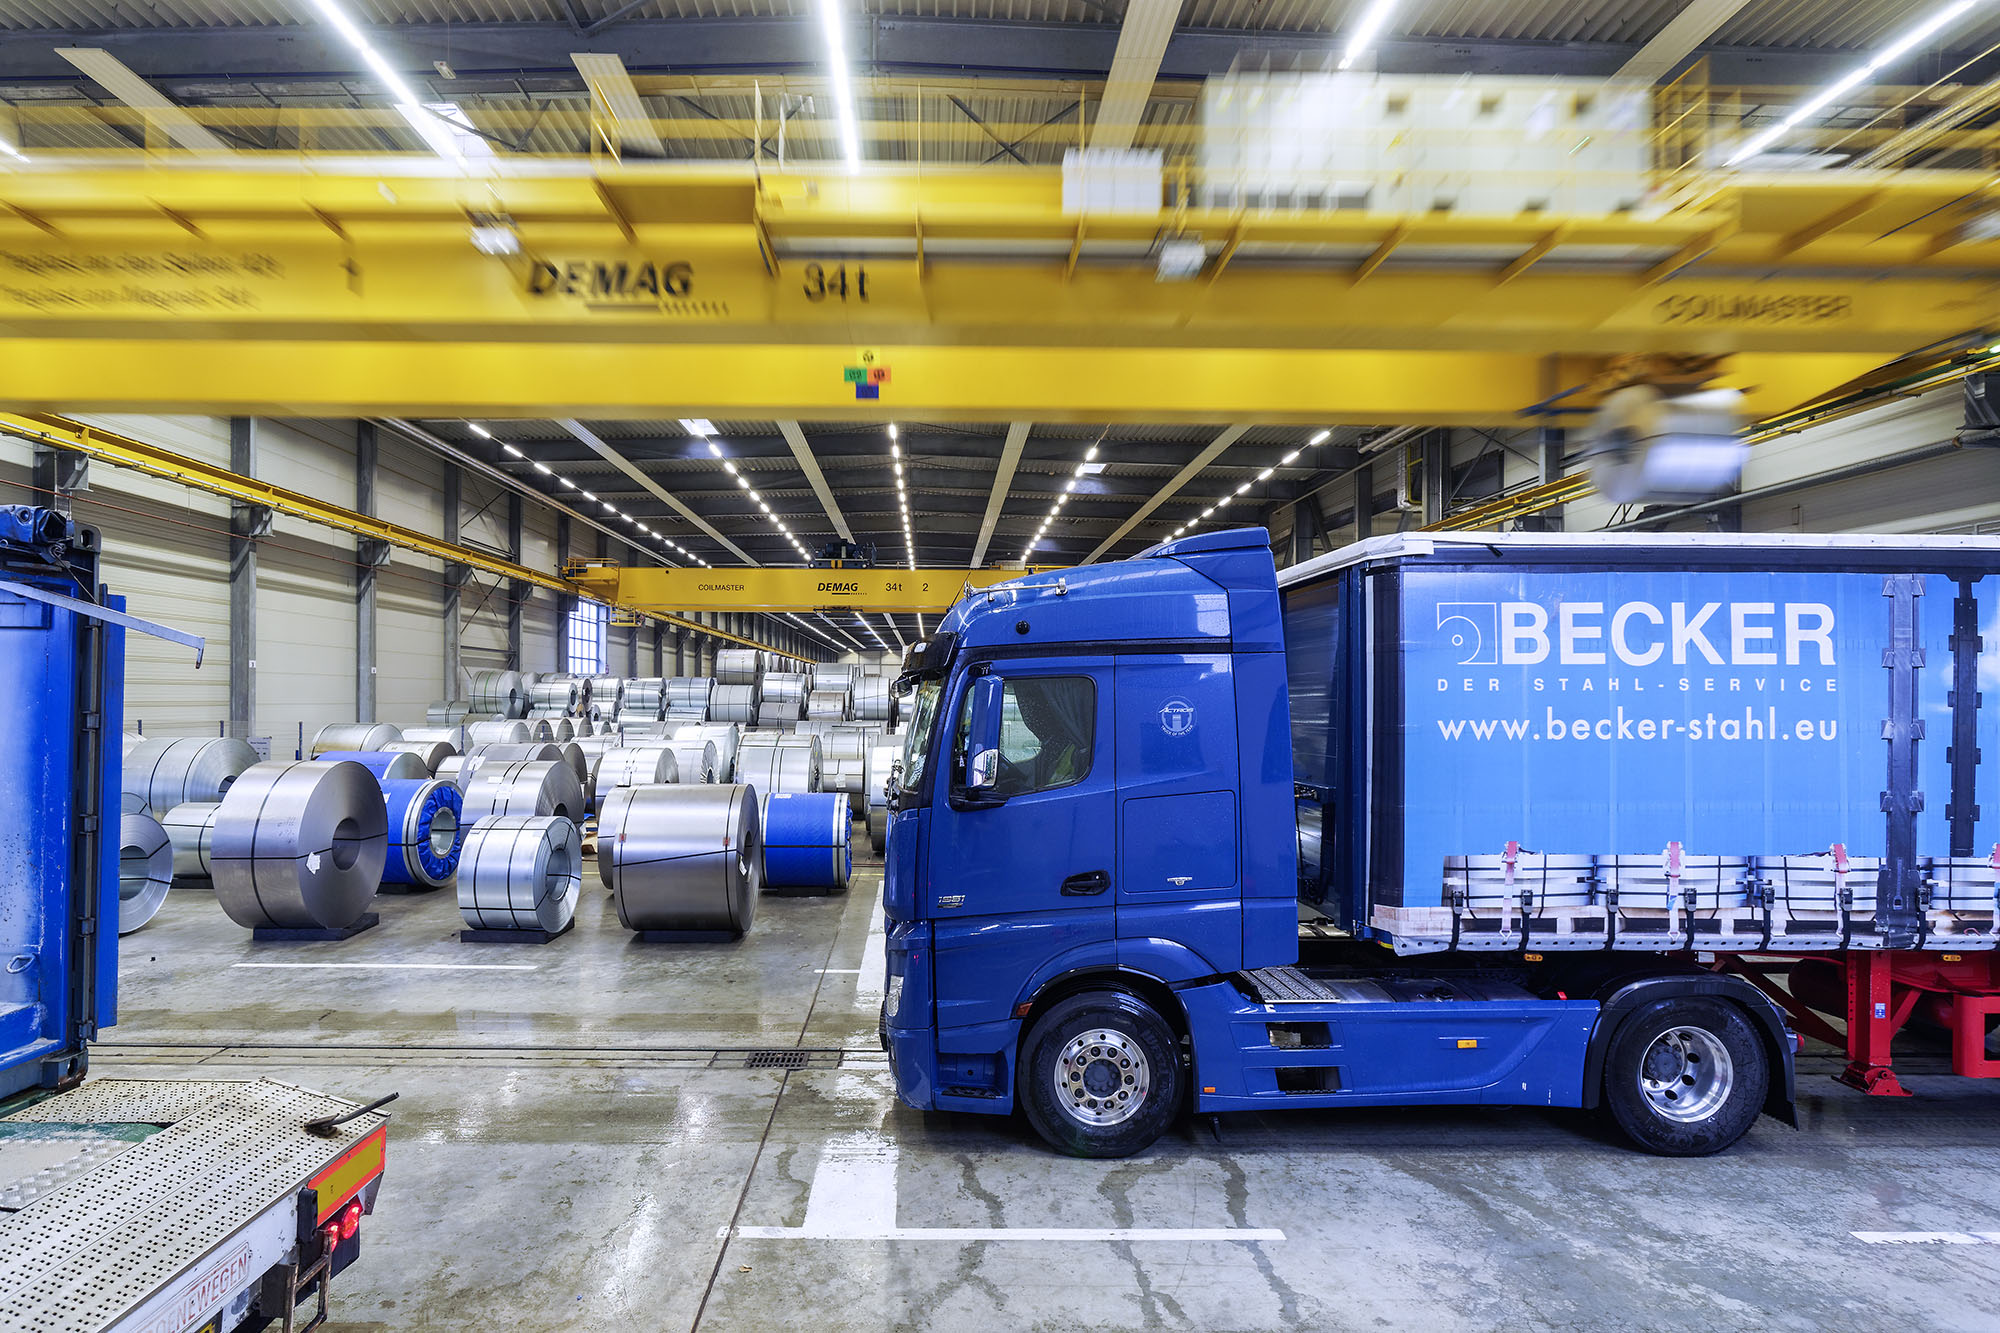
Klöckner & Co has signed an agreement to sell Becker Group to a consortium comprising Accura Investment Partners GmbH and Becker Consult + Beteiligungs-GmbH (BCB), the company announced on 8 October 2026.
The transaction is subject to customary regulatory approvals and is expected to close before the end of 2026. The parties have agreed to keep the purchase price confidential.
Becker Group is an independent service centre of steel, stainless steel and aluminium in Europe, serving customers including the automotive and metal processing sectors. Klöckner & Co first announced its intention to divest the business in January 2026, following a review of strategic options. The company said the sale supports its focus on higher value-added products and services.
Guido Kerkhoff, CEO of Klöckner & Co SE, said: “With the sale of Becker Group, we have reached another milestone. The consortium of Accura and BCB is deeply rooted in the industry and brings the expertise needed to develop Becker Group on a sustainable basis. The realignment concept initiated by us and Becker Group will be further developed by Accura and BCB, determining the future direction of Becker Group. Through the sale, Klöckner & Co will place an even greater focus on higher value-added business and consistently drive its own profitable growth in this segment.”
Ulrich Becker, Senior Managing Partner of Becker Consult + Beteiligungs-GmbH, said: “Becker Group has a strong market position and a team that truly knows the business. With our own extensive background in the steel and metal industry, we look forward to building on this foundation together with the management team and the entire workforce to drive long-term growth.”
Under the planned ownership change, Becker Group will continue to be led by its existing management team, headed by CEO Torsten Gieseke. The consortium intends to further develop the realignment programme jointly initiated by Klöckner & Co and Becker Group.
The programme will focus on improving sales, procurement and business processes, alongside inventory management and liquidity. According to the announcement, the buyers aim to stabilise the business and support its long-term development in Europe.
No immediate headcount reductions or site closures are planned at closing. However, the consortium intends to review Becker Group’s strategic positioning and the contribution of individual business units as the programme progresses. Any subsequent decisions will take account of market and cost developments and be coordinated with the relevant employee representative bodies.
Accura is an independent investment company focused on traditional industries in the European mid-market. BCB is a consultancy and investment firm specialising in industrial mid-market businesses, led by Ulrich Becker, a former member of Klöckner & Co’s Management Board.

Northern European HRC rises slightly on higher mill offers; Italian prices decline despite tight supply
Local steel hot-rolled coil (HRC) prices in Northern Europe edged up slightly as mills tried to achieve higher levels, while prices in Italy declined on the latest deals despite limited supply in the market, sources told Fastmarkets on Wednesday October 7.
In Northern Europe, sources said demand was still subdued, so price increases were not accepted as quickly as mills expected.
A buyer source reported an indication of workable prices in the Benelux area at €730 ($821) per tonne ex-works, saying this level was still possible to achieve. The same source said offers from mills in the area were at €740-750 per tonne ex-works.
A second buyer reported an offer at €760 per tonne ex-works. No other price points were received during the day.
Due to one source accounting for more than 50% of the input on Wednesday, prices collected in the previous day were copied over to the latest index calculation, in line with Fastmarkets methodology.
On Tuesday, a seller source reported deals within the range of €740-760 per tonne ex-works, and a buyer reported an indication of tradable level at €740 per tonne ex-works.
Thus, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €746.88 per tonne on Wednesday, up by €1.88 per tonne from €745 per tonne on Tuesday.
The index was stable week on week but up by €4.38 per tonne month on month.
In Italy, a producer in the market said that the latest prices confirmed in transactions were within €750-760 per tonne delivered for November-December delivery, which nets back to around €730-745 per tonne ex-works after deducting delivery costs of €15-20 per tonne.
The same source said that they were not seeing higher levels achieved in the market yet, “even if the offers are definitely higher.” The producer added that it was offering minor December allocation at €750 per tonne ex-works, with bids €10-20 per tonne below this level.
However, this fell outside the Fastmarkets methodology delivery window of up to six weeks, so the December prices were not considered in Wednesday’s index calculation.
Despite the statement from the producer about limited increases achieved in the market, a buyer indicated workable HRC prices in Italy within the range of €740-750 per tonne ex-works, in line with previous transactions heard in the market on Monday October 5.
As a result, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €741.25 per tonne on October 7, down by €3.75 per tonne from €745 per tonne on October 6.
The index was down by €2.50 per tonne week on week but up by €13.75 per tonne month on month.

EUROFER: EU steel pipe and tube output to grow by 1.3 percent in 2026
EU steel pipe and tube production is expected to increase by 1.3 percent in 2026, following marginal growth of 0.1% in 2025, according to the European Steel Association’s (EUROFER) third-quarter Economic and Steel Market Outlook 2026-2027, which points to a gradual recovery amid persistent uncertainty across European manufacturing.
The projected expansion follows three consecutive years of contraction, with EU tube output falling by 1.3% in 2022, 1.4 percent in 2023 and 2.4 percent in 2024, before stabilizing in 2025. EUROFER forecasts a further increase of 1.2% in 2027, indicating that the sector’s recovery will remain modest.
Tube production growth is expected to lag behind the overall recovery in EU steel-using industries, whose steel-weighted output is forecast to increase by 1.5 percent in 2026 and 2.5 percent in 2027, following a decline of 0.1 percent in 2025.
Author: SteelOrbis Editorial Team