


Assofermet: Tariffs and CBAM redraw metals markets – “Geopolitics is now a cost factor for companies”
Tariffs, geopolitical tensions, new trade barriers, high energy costs and the reshaping of supply chains are redefining the environment in which Italian steel and metals companies operate. These were the key issues addressed at the autumn conference of Assofermet, held on Friday, October 2, at the headquarters of Confcommercio in Rome, under the title “Markets at risk, and potential for companies.”
Opening the event, following a video message from Confcommercio president Carlo Sangalli, Assofermet president Cinzia Vezzosi noted that the title chosen by the association several months ago had proved, in light of recent international developments, “almost uncomfortably topical”. Alongside ongoing conflicts and geopolitical instability, companies are now facing new trade restrictions, tighter measures affecting steel imports and the transition of CBAM into its most economically significant phase. However, Vezzosi’s message was not solely one of concern. She highlighted the ability to react quickly as one of the main strengths of Italian SMEs: the capacity to anticipate change, address difficulties and adapt their strategies “in months rather than years”.
Tariffs and geopolitics redraw the global trade map
The first roundtable, moderated by Sissi Bellomo, commodity and energy markets editor at Il Sole 24 Ore, brought together Natalino Loffredo, ministerial adviser for International Trade Policy at Italy’s Ministry of Foreign Affairs and International Cooperation (MAECI); Antonio Villafranca, vice president for research at ISPI; and Alessandro Panaro, head of the Maritime & Energy Department at SRM – Studi e Ricerche per il Mezzogiorno.
One of the main themes to emerge was the increasing use of economic tools as instruments of political pressure. According to Villafranca, the deterioration of the international order has been under way for at least 15 years, while trade, tariffs, raw materials and infrastructure are increasingly becoming part of a broader power dynamic. “Everything is becoming a weapon, including the economy,” he said, pointing in particular to the role of so-called chokepoints, strategic passages through which goods, energy and hydrocarbons flow.
Tensions surrounding the Strait of Hormuz have shown how the concentration of trade flows through a limited number of strategic routes can affect global supply chains. According to Villafranca, alternative routes and infrastructure can reduce some of these vulnerabilities, but inevitably at a higher cost.
This point was echoed by Alessandro Panaro, who said companies now have to factor a new item into their costs: the cost of geopolitics. “Logistics is like water: costs may rise, but it will always find a way through,” he said. Longer routes, surcharges and port congestion have pushed transportation costs higher, while supply chain reliability has deteriorated. Panaro cited a 112 percent increase in freight rates and vessel schedule reliability of around 50 percent. Despite this, the Mediterranean has continued to show considerable resilience: in 2025, Italian ports handled around 510 million mt, 30 million mt more than in the previous year.
According to Panaro, the response lies primarily in greater logistics efficiency, digitalization and sustainability, which are becoming increasingly important competitive factors. He took a different view of the EU ETS as applied to shipping, arguing that it risks becoming a competitive disadvantage if confined to the European market alone.
On the trade front, Natalino Loffredo described the United States as a “difficult-to-replace” partner for Europe, despite the sharp tightening of US tariff policy. Italy and Germany have supported an approach aimed at avoiding further trade escalation, while Section 232 remains a key issue for the metals sector, covering steel, aluminum and copper as well as a broad range of semi-finished and downstream products.
At the same time, relations with China remain another major issue. Loffredo stressed the need to keep dialogue with Beijing open while also promoting greater diversification of sourcing. However, such a process comes at a cost and, in his view, should therefore be supported by appropriate incentives for companies.
China’s presence, moreover, extends well beyond trade flows. Panaro noted that Beijing has invested around $20 billion in Mediterranean ports since 2013, including through long-term infrastructure concessions. At the same time, SRM has recorded a 13 percent increase in intra-Mediterranean routes, further evidence that supply chains are already undergoing a gradual reconfiguration.
CBAM, energy and margins put European competitiveness to the test
The second roundtable, entitled “Energy for companies amid the complexity of global challenges,” featured Marco Gay, CEO of ZEST SpA and president of the Turin Industrial Union; Andrea Di Sotto, partner at SO.DE.MI Srl and AluGlobalBro Srl; and Riccardo Gabrielli, sales & area manager of the heavy plate division at Gabrielli SpA.
Andrea Di Sotto highlighted the difficulties facing the aluminum semis sector as it reshapes its sourcing strategies amid reduced Russian supply, antidumping measures, logistics constraints and new European regulatory requirements. From an importer’s perspective, he described CBAM as “a hidden tariff,” stressing the uncertainty surrounding its initial implementation. “This is year zero for CBAM: we are importing material without yet knowing with certainty what the final cost will be,” he said. This uncertainty is complicating purchasing strategies and margin management at a time when companies are already being forced to rethink established supply chains and absorb higher costs throughout the value chain.
Focusing more directly on the steel sector, Riccardo Gabrielli stressed that CBAM is not merely an administrative compliance issue, but one with direct financial and commercial implications. Uncertainty over the actual carbon cost makes it difficult to value material that has already been purchased: for several thousand metric tons of imported steel, different cost assumptions can result in discrepancies running into hundreds of thousands of euros.
Gabrielli also pointed to the growing spread of carbon pricing systems outside the European Union, citing China, the United Kingdom and South Korea among others. In Italy, the growing complexity of imports is compounded by the decline in domestic steel production capacity. The downsizing of the former Ilva has increased the country’s dependence on foreign supply just as sourcing from international markets is becoming more expensive and less predictable.
The central issue, therefore, remains competitiveness. Marco Gay stressed that the energy cost gap has been a structural problem for Italian industry for several years, while high logistics costs, interest rates and increasingly squeezed margins are adding further pressure. In Gay’s view, the EU ETS cannot be seen simply as an economic issue, but as a factor that directly affects European industry’s ability to compete and continue investing.
Against this backdrop, innovation and artificial intelligence can offer new levers for efficiency. Gay argued that the key issue will not be whether AI replaces jobs, but rather whether companies and workers are able to integrate it effectively into their processes. Gabrielli agreed on the need to focus on internal optimization, particularly at a time when many of the main cost drivers are increasingly beyond companies’ direct control.
The debate ultimately returned to its starting point: in a market environment in which geopolitics, trade, logistics and energy are increasingly intertwined, resilience and the ability to adapt quickly remain essential, but they are not enough if the competitiveness of Europe’s industrial system is undermined.
Closing the event, Cinzia Vezzosi declared, “I firmly believe that, as we move forward through this complex process, companies have a real responsibility, with the hope and conviction that the decisions we make today can concretely help build the future.”
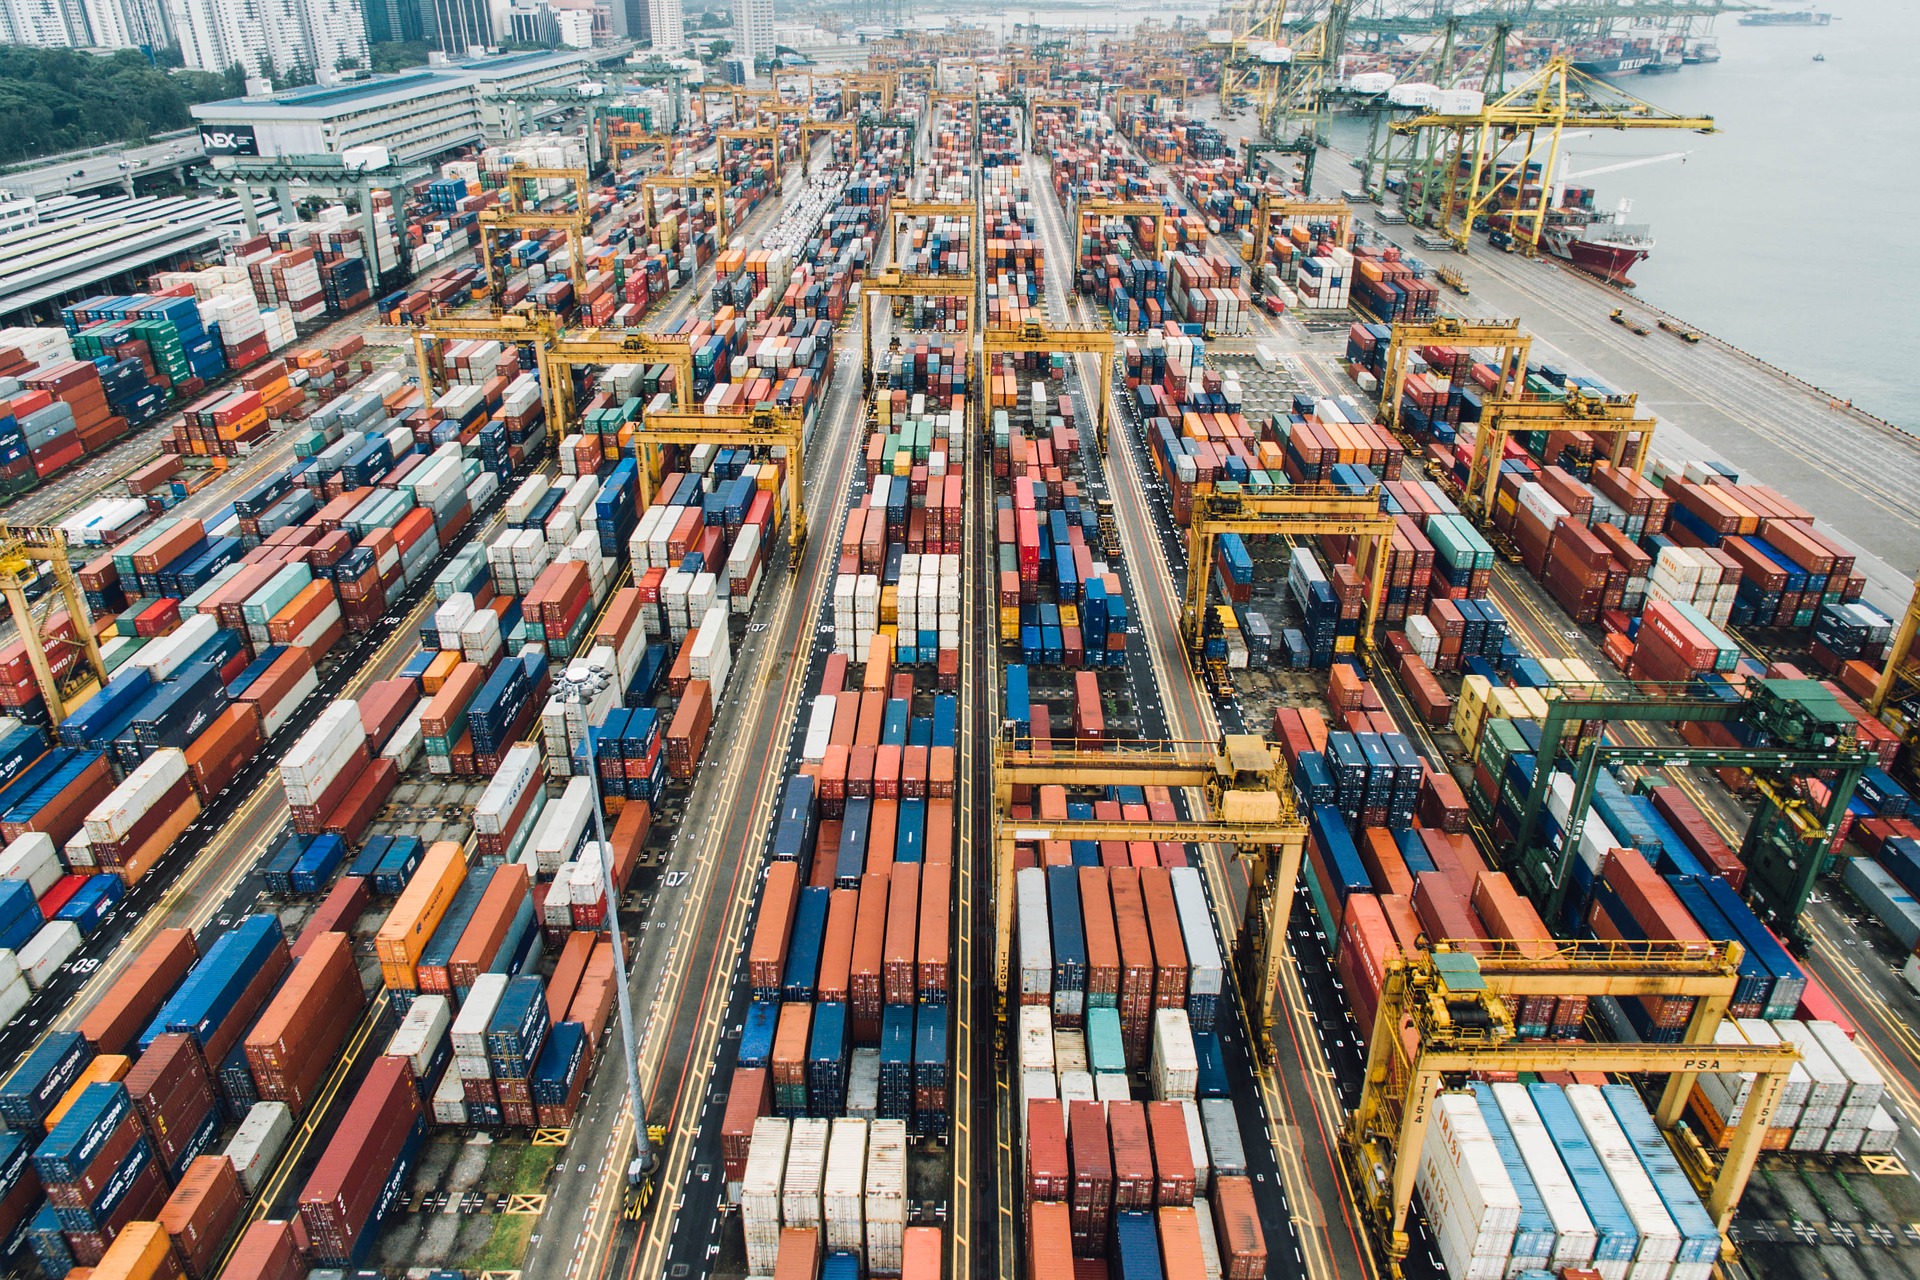
EU steel import quotas rapidly exhausted in opening days of Q4 period
In the first 5 days of the new EU quota period from October 1 to December 31, some of the import quotas for certain steel products allocated for Turkey, China, India, Australia, Taiwan, Macedonia and “other countries” have been exceeded, while over 70 percent of quotas for some steel products have been used up, according to the European Commission’s data.
Regarding the exceeded quotas, Turkey has exceeded its quotas of 160,573 mt for HRC, 63,925 mt for metallic coated sheets (4A), 26,019 mt for metallic coated sheets (4B) and 11,568 mt for organic coated sheets, 7,007 mt for quarto plates, with 378,822 mt, 96,084 mt, 26,577 mt 16,073 mt and 15,474 mt of the given products respectively waiting for customs clearance. In addition, the country has also exceeded its quotas of 59,919 mt for rebars, 61,147 mt for wire rods, 28,163 mt for gas pipes, 59,849 mt for hollow sections and 22,453 mt for other welded pipes, with 78,088 mt, 70,698 mt, 45,891 mt, 112,046 mt and 25,420 mt of the given products respectively waiting at the EU ports.
The quotas of 11,837 mt for electrical sheet (3B), 45,749 mt for metallic coated sheets (4B), 13,158 mt for other seamless pipes and 14,298 mt for non-alloy wire allocated for China has been exceeded with 41,793 mt, 111,256 mt, 23,947 mt and 28,888 mt of the given products respectively waiting for customs clearance.
Looking at the quotas allocated for India, the country has exceeded its quotas of 52,709 mt for quarto plates, 23,139 mt for stainless bars and light sections, 10,036 mt for gas pipes and 3,832 mt for seamless stainless tubes, with 64,454 mt, 39,641 mt, 13,166 mt and 4,859 mt of the given products respectively waiting at the EU ports.
Australia and Taiwan have exceeded their quotas of 11,830 mt for HRC and 5,322 mt for organic coated sheets, respectively, while Macedonia has exceed its quota of 10,958 mt for hollow sections.
Meanwhile, the quotas of 5,564 mt for HRC, 24,933 mt for CRC, 33,338 mt for metallic coated sheets (4A), 6,446 mt for tin mill products, 18,829 mt for quarto plates and 7,174 mt for hollow sections allocated for “other countries” have been exceeded. In addition, the quota of 5,149 mt for hollow sections allocated for “FTA-Others” has also been exceeded.
The quotas with utilization rates above 70 percent can be seen in the table below.
| Product | Country | Quota volume (mt) | Usage (%) |
| Organic coated sheets | India | 54,334 | 75.50 |
| South Korea | 41,828 | 86.76 | |
| Merchant bars and light sections | China | 39,484 | 85.15 |
| Rebars | Algeria | 15,940 | 71.86 |
| Angles and sections | Turkey | 13,455 | 73.31 |
| Hollow sections | China | 3,680 | 80.82 |
| Ukraine | 6,640 | 94.32 | |
| Other welded pipes | China | 3,220 | 99.75 |
| India | 6,158 | 80.85 |
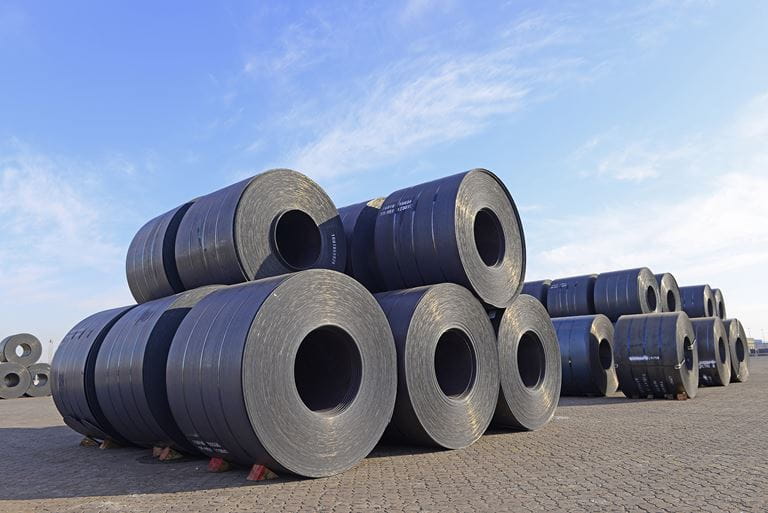
Northern European HRC prices edge down; Italian prices firm on tight supply
Domestic hot-rolled coil prices in Northern Europe edged lower on Monday October 5, while Italian prices continued to firm amid exceptionally tight domestic supply and uncertainty over import availability, sources told Fastmarkets.
In Northern Europe, one buyer reported workable levels at €740 ($833) per tonne ex-works.
No other fresh points were recorded during the day. On Friday October 2, one supplier indicated workable levels at €730-740 per tonne ex-works. Due to the limited fresh input, this information, along with Thursday’s data, was carried over into Monday’s calculation in line with Fastmarkets’ index methodology.
This included a buyer indication of workable levels at €750 per tonne ex-works, as well as information from a second buyer reporting workable levels at €740-750 per tonne ex-works alongside an offer at €760 per tonne ex-works.
Regional demand remained sluggish, with buyers reporting sufficient stock coverage.
Thus, Fastmarkets’ daily steel hot-rolled coil index, domestic, exw Northern Europe, was calculated at €741.88 per tonne on Monday October 5, down by €1.45 per tonne from €743.33 per tonne on Friday October 2.
The index was up by €3.12 per tonne week on week and down by €6.87 per tonne month on month.
Meanwhile, in Italy, two buyers told Fastmarkets that workable levels were reported at €740-750 per tonne ex-works. One of the buyers indicated that bookings of around 200-500 tonnes were concluded in that range.
Domestic supply options in Italy were reported to be exceptionally constrained, with Acciaierie d’Italia (AdI) remaining absent from the market, and Ferriera Valsider also on the sidelines with only minor potential availability for December.
Market participants also pointed to mounting uncertainty over imports following the opening of the fourth-quarter tariff-rate quota on October 1. The Turkish quota was already heavily oversubscribed, with around 380,000 tonnes reported against a quota of approximately 160,000 tonnes, according to one of the buyers.
As a result, some Italian buyers were adopting a wait-and-see stance until the end of the week to assess the full customs clearance picture across various import origins before committing to fresh domestic volumes. Those needing immediate material were largely dependent on the country’s sole active domestic producer, which firmly held its ground at €740-750 per tonne ex-works.
“If you need to buy, you pay and shut up,” one distributor source said.
The buyer told Fastmarkets that the dominant domestic producer was comfortable with its November order book following recent operational disruptions on a rolling line.
Fastmarkets’ daily steel hot-rolled coil index, domestic, exw Italy, was calculated at €745 per tonne on Monday October 5, up by €2.50 per tonne from €742.50 per tonne on Friday October 2.
The index was up by €3.75 per tonne week on week and up by €22.29 per tonne month on month.


Trasteel moves closer to Nasdaq listing via SPAC
Steel trading and industrial group Trasteel has taken another step towards a Nasdaq listing through its planned merger with special purpose acquisition company (SPAC) Sizzle Acquisition Corp. II, the companies say in a joint note.
On 30 September, Trasteel S.A, a new Luxembourg holding company set up for the deal, submitted a draft registration statement on Form F-4 to the US Securities and Exchange Commission (SEC). The document relates to the business combination agreement the parties signed on 13 April 2026, which has since been amended.
The registration statement has not yet been formally filed or declared effective. It remains subject to SEC review, Kallanish notes.
Under the deal, the new holding company will acquire all of Trasteel’s shares in exchange for its own ordinary shares. Its wholly owned subsidiary, Trasteel Merger Sub Limited, will merge into Sizzle II. Both Trasteel and Sizzle II will then become subsidiaries of the holding company.
The transaction, expected to close by end of 2026, still needs the SEC to declare the registration statement effective, and Sizzle II shareholders must approve it, among other conditions. After closing, the new holding company is expected to trade on Nasdaq under the ticker TSTL.
Trasteel is headquartered in Lugano, Switzerland, and in Luxembourg. Sizzle Acquisition Corp. II is a Cayman Islands-based special purpose acquisition company listed on Nasdaq under the ticker Szzl. Trasteel intends to use proceeds from this transaction for strategic acquisitions and investments.
The transaction values Trasteel at a pre-money equity value of $800 million. The value of the combined company is expected to be approximately $1.3 billion, assuming no redemptions by public shareholders of Sizzle II. (see Kallanish passim).

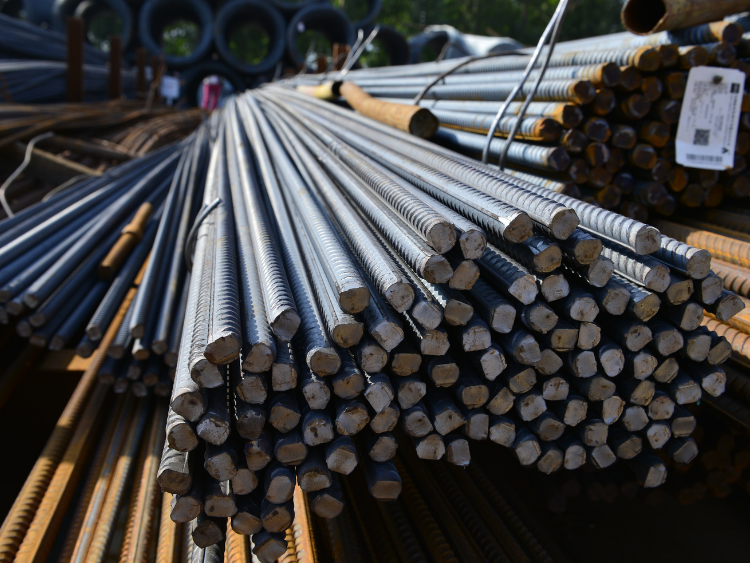
Italian rebar prices rise in recent deals
Italian rebar contracts have ticked higher in recently concluded deals, with producers pushing prices up further in October, asking for €480-490/tonne ($545.8-557.2/t) base ex-works.
The increases, however, are struggling to take off with buyers who are adopting a cautious stance considering the weak market activity, sources tell Kallanish.
Some sources say they are starting to feel the impact of EU-funded infrastructure projects coming to an end. One distributor reports weak demand for rebar and mesh in recent weeks. A construction company is more positive, however. It expects a good October as new orders are coming in.
“Payment delays persist, and despite a slightly better demand in the second half of September, the market remains challenging,” another source comments.
Rebar contracts implemented last week were concluded at €430-440/t base ex-works on average.
The level of €460/t is heard being charged for a truckload, equivalent to 30 tonnes. Kallanish assesses Italian rebar at €690-730/t ex-works on Friday, including size extras of €260-270/t.
Mesh prices are reported at €520-540/t delivered, excluding €300/t for size extras.

CBAM certificate price rises in Q3
The price of Carbon Border Adjustment Mechanism (CBAM) certificates for the third quarter of 2026 has been set at €82.32 ($92.3), rising steeply, by €7.04 from the previous quarter, Kallanish notes.
This comes as EU carbon permit (EUA) prices increased on-quarter in Q3, peaking at above €88 in mid-September as increased coal use boosted demand for EUAs. However, they still did not reach the Q1 peak in excess of €93.
The Emissions Trading System (ETS) is being reviewed by EU lawmakers amid intense debate within the steel industry. Early decarbonisation investors want high EUA prices to ensure a business case, while other mills are asking to ease the cost pressure until conditions enabling decarbonisation are in place.
The European Parliament recently voted to maintain the invalidation of allowances in the Market Stability Reserve (MSR), but raise the threshold from 400 million to 650 million allowances. Eurofer said the phaseout of free allowances should be slower than planned, with focus also given to providing low-carbon energy, effective trade measures and lead markets for low-carbon steel.
CBAM is also coming under attack. The World Trade Organisation (WTO)’s Dispute Settlement Body (DSB) has established a panel at Russia’s second request to determine whether the EU’s CBAM and alleged ETS export subsidy are consistent with the bloc’s WTO commitments.
EUROFER: EU steel imports decline, trade deficit narrows

EU HRC prices up slightly amid output issues, fewer import negotiations due to risks
Domestic HRC business activity in the EU has remained at moderate levels this week with some price increases being seen in certain regions, mostly due to some production issues faced by a few mills, particularly in Italy and Germany.
The general stocks of HRC across Europe is still at medium to high levels, but sentiment remains firm as regards pricing remains due to strong market fundaments and high risks facing imports. The import activity for HRC has diminished this week in Europe since many believe the quota for some origins has been already closed and exceeded for Q1 2027 while others prefer to refrain from imports due to CBAM uncertainties to be faced in Q1-Q2 next year.
In Italy, according to sources, amid the issue with production at Arvedi, local HRC prices have moved up by €20-30/mt in the latest targets to €760-780/mt delivered, while the transportation cost is estimated at roughly €10-25/mt depending on the region. In Spain, the workable price level has improved by €5-10/mt to €740-745/mt ex-works, while in the northern part of the EU the price levels are at €740-760/mt and up to €770/mt ex-works. Meanwhile, a source has reported that one mill in the Benelux region has been selling at as low as €725-730/mt ex-works, but the level is not widespread in the EU. In eastern Europe, some of the producers have increased offers by €20-30/mt to €760/mt delivered, while others remained at €765-775/mt and up to €790/mt CPT.
In the import HRC segment, duty paid offers from Turkey have been reported at $700-710/mt or €625-635/mt CFR, up by €5-10/mt over the past week. The latest offers from India have been reported at $730-740/mt and up to $750/mt CFR (€650-670/mt) CFR, up from the latest deals at $715-725/mt CFR. “Both India and Turkey seem to have sold a lot [of HRC] for Q1 2027. They will fight for the FTA [CSQ] and it is going to be a mess,” a European trader told SteelOrbis. “So, we have decided not to import any HRC,” he added.
Most of the HRC import offers continue to be heard on DDP basis since the buyers are aiming to minimize their risks as much as possible. Japan and Taiwan are at €770/mt while South Korea is offering at as high as €790/mt, while the workable levels are still considered to be closer to €730-750/mt DDP.
€1 = $1.12
Author: SteelOrbis Editorial Team


Italian longs prices still under upward pressure, but sales volumes remain low
According to market participants in the Italian long steel segment, attempts to raise sales prices have continued this week, although sales volumes remain modest.
As for prices, sources have reported list prices at €470-490/mt ex-works base (€735-755/mt ex-works including regular extras), around €50/mt higher than the levels at the beginning of September. However, sales continue to be reported at €460/mt ex-works base (€725/mt ex-works including regular extras) and even at lower levels for limited tonnages.
End-users state that they are unwilling to build up inventories during the remainder of the year and are limiting purchases to immediate requirements to avoid ending the year with excessively high stock levels.
In the wire rod segment, sales forecasts for October indicate a slight month-on-month increase of around €5/mt, with the increase remaining limited due to the substantial lack of demand. This would bring drawing-quality wire rod prices to €675-685/mt and mesh-quality wire rod prices to €665-670/mt, both delivered.
According to one market participant, this slight increase is mainly driven by rising production costs, while demand from end-users continues to be restrained by the impact of the international situation and the depletion of European funds for construction and infrastructure.
No wire rod export offers have been reported from Italy, while rebar offers have been heard at around €590-600/mt FOB, although one source stated that it had also heard offers at levels around €20/mt lower.
In conclusion, it could be said that the Italian market – as well as the broader European market – is facing a paradox: producers have to cope with higher costs and therefore seek to raise prices, but at the same time these higher prices are passed on to downstream consumers, which are unable to bear them.
Author: SteelOrbis Editorial Team
Rosseel acquires Aleja’s steel distribution business in Belgium
Belgian steel distributor NV Rosseel, based in Tielt, has acquired the business of NV Aleja in Welle-Denderleeuw from Marc De Winter and his family, effective 1 October. Day-to-day operations will initially remain unchanged, with the existing team continuing at the same location.
The acquisition adds production capacity and technical expertise to Rosseel’s operations in Tielt and Ruddervoorde, where it has been active since 2021. Aleja specialises in steel beams and reinforcing steel, bringing capabilities that complement Rosseel’s existing activities.
“What makes Aleja interesting for us is that it is not simply more of the same,” said Johan Rosseel, Managing Director of Rosseel. “Aleja is strong in steel beams and reinforcing steel and brings production capabilities that we do not currently have in the same form.”
Rosseel highlighted the technical knowledge and experience of Aleja’s team as a key benefit of the acquisition. Aleja will, in turn, gain access to the stock and customised processing services available at Rosseel’s Tielt and Ruddervoorde sites.
Source: HLN