

Long steel market becoming increasingly regional, despite global GDP growth: IREPAS
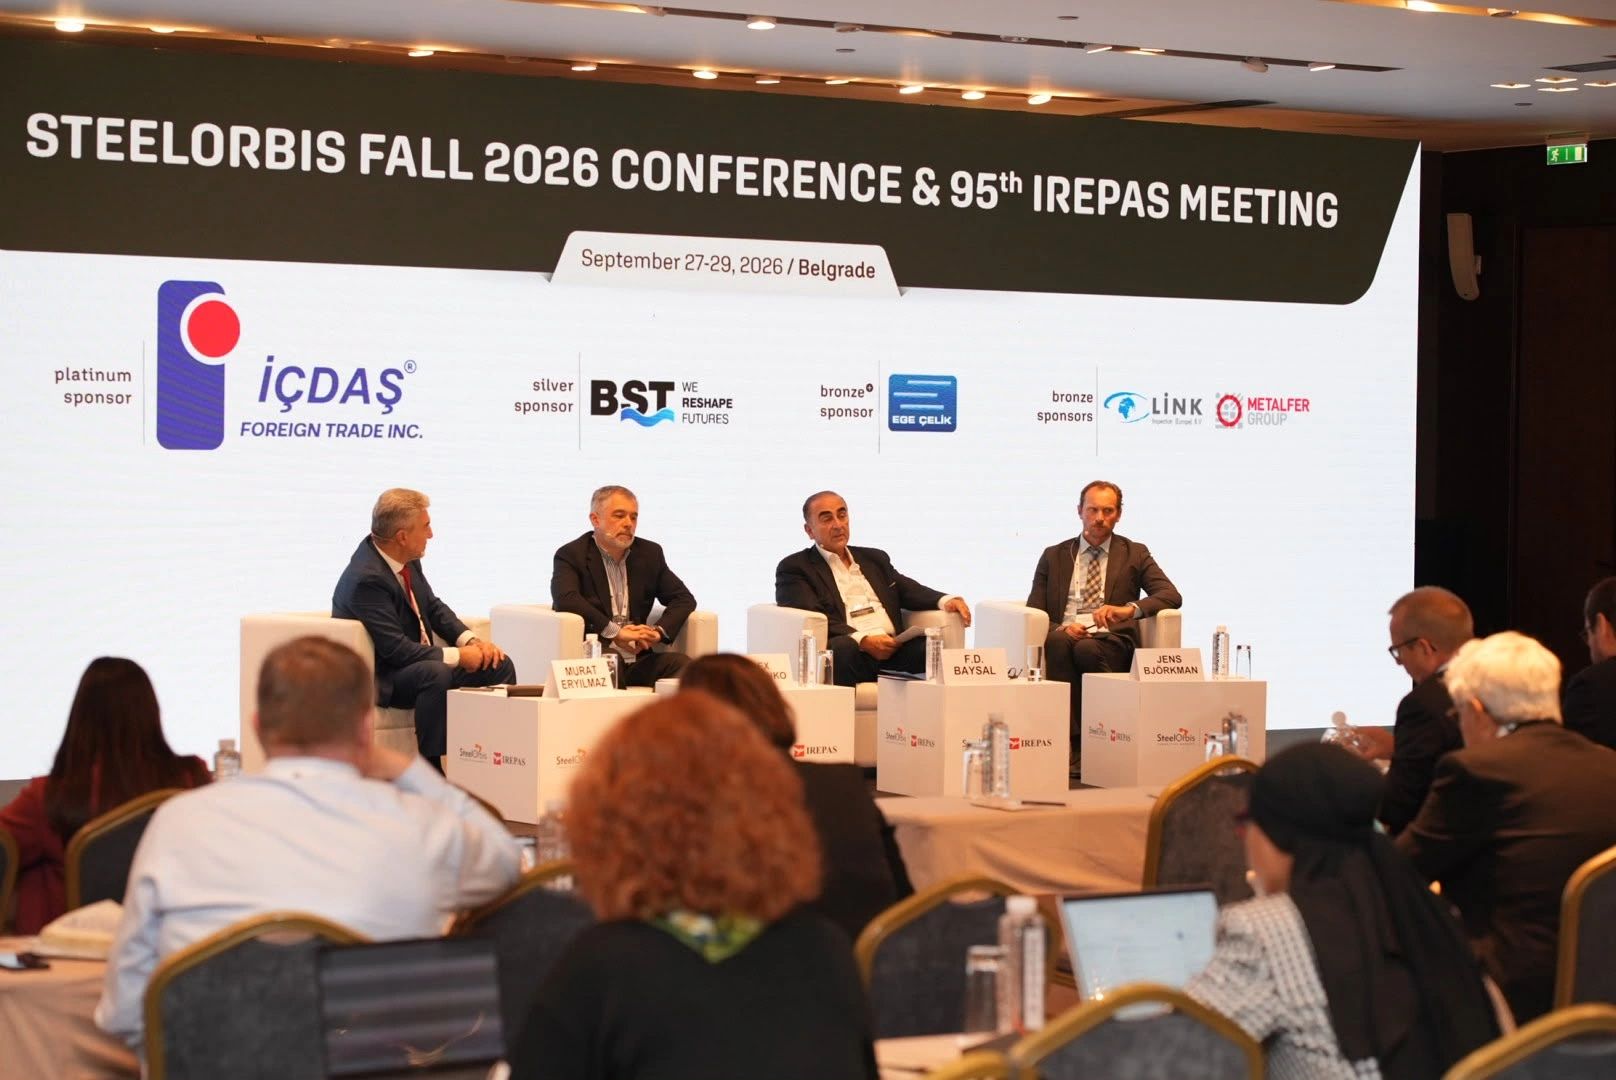
Global GDP growth of 3.1%, according to the International Monetary Fund (IMF), has not translated into stronger steel demand, Alexander Gordienko, export director of Spanish electric-arc furnace (EAF)-based steelmaker Celsa Group, said during his presentation.
“This is not the kind of growth which creates growth in demand,” Gordienko said.
While the global economy continues to expand, the distribution of that growth has become increasingly important for steel markets. Stronger economic growth remains concentrated in Asia, particularly India, which recorded GDP growth of 6.5%, while Europe grew by just 1.3%.
Gordienko said that despite solid global GDP growth, the steel market remained oversupplied and highly competitive. Faster-growing economies were also expanding their own steelmaking capacity; however, GDP growth somewhere in the world does not automatically become export demand for steel.
Construction remains key steel-consuming sector
Construction remains the most important end-use sector for steel, but regional trends differ significantly.
Europe’s construction sector remains constrained by weak residential activity despite persistent housing shortages. Infrastructure projects provide some support, but according to Gordienko, the challenge is not the absence of demand for housing, but the difficulty of converting that need into actual projects through faster planning, approvals and reduced bureaucracy.
In contrast, the United States is witnessing significant investment in infrastructure linked to artificial intelligence (AI), including data centers, power generation and transmission networks. While residential construction remains relatively soft, AI-related infrastructure investment has emerged as a key source of steel demand growth.
China remains main structural weakness
China, meanwhile, remains the main structural weakness for global steel consumption, according to Gordienko. The country’s property sector has yet to show a meaningful recovery, leaving domestic demand unable to absorb the country’s steelmaking capacity and maintaining pressure on export markets.
“The problem is that if Chinese demand is not saved, then the Chinese domestic market cannot absorb the enormous Chinese steel production. It has to go for export.”
India presents the opposite picture, with infrastructure investment continuing to support genuine steel demand growth. However, Gordienko cautioned that increasing domestic steel production means India should not automatically be viewed as a major future import market.
Regional divergence becoming more visible
Global steel production remains close to pre-pandemic levels, but production trends are increasingly diverging by region.
While output has declined in China and Russia, production has increased in countries including India and the US.
At the same time, Chinese steel exports continue to exert pressure on international markets. While trade measures may alter trade flows and destinations, Gordienko said they do not eliminate export pressure.
Long steel consumption declined by around 2% in the first half of 2026, according to estimates by CRU Group presented during the conference.
While such a decline may appear modest, it is enough to intensify competition in a market with significant available capacity, said Gordienko.
The decline in rebar consumption remains concentrated in Asia, particularly China, while Europe has remained broadly stable and North America has recorded stronger demand.
From a global steel cycle to regional cycles
While technologies such as AI are spreading globally, the physical infrastructure required to support them is concentrated in regions with access to capital, energy and project development capabilities.
As a result, investment growth is becoming increasingly concentrated geographically.
This trend, combined with growing trade barriers and diverging regional demand patterns, suggests that steel markets are becoming increasingly fragmented.
“On some level, the world is moving very rapidly into the future. On another, physical level, it appears to be returning to the past. Our business is operating in both worlds at the same time,” said Gordienko.
Raw materials continue to trade globally, while finished steel markets are becoming more regional.
Demand growth is concentrated in specific regions such as India, while large-scale AI-related investment is concentrated in the US.
Gordienko argued that traditional global steel cycles may be breaking down into multiple regional cycles, where one market can remain oversupplied while another experiences tighter conditions.
“Maybe we should stop talking about the global steel cycle, and we should start talking about regional cycles,” Gordienko said.

European HRC prices edge higher despite sluggish demand
In Northern Europe, a buyer indicated mill offers at €760 ($862) per tonne ex-works.
“The market is very quiet. Small bookings are being done at €740 per tonne ex-works,” the source added.
No other fresh price points were reported during the pricing session. Thus, in line with Fastmarkets’ methodology, seller data from Tuesday indicating workable levels at €740-750 per tonne ex-works was carried over into Wednesday’s calculation. On Tuesday, a buyer had indicated workable levels at €745-760 per tonne ex-works and a second buyer had reported tradable levels at €735-750 per tonne ex-works.
Consequently, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €746.88 per tonne on Wednesday September 30, up by €0.63 per tonne from €746.25 per tonne on Tuesday September 29.
The index was up by €6.88 per tonne week on week and by €5.63 per tonne month on month.
In Italy, trading activity remained constrained by cautious downstream buying.
A buyer source reported an indication within €740-745 per tonne ex-works.
“We hear workable levels have come closer to the Northern European level,” the source added.
A second buyer source indicated achievable levels slightly higher, at €740-750 per tonne ex-works.
As a result, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €743.75 per tonne on Wednesday September 30, up by €1.25 per tonne from €742.50 per tonne on Tuesday September 29.
The index was up by €8.75 per tonne week on week and by €26.25 per tonne month on month.

Stahl-Holding-Saar announces new construction phase for Power4Steel project
Author: SteelRadar Editorial Team


European steel giant downsizes with 4,000 job cuts
Thyssenkrupp Steel provided an update on the progress of its restructuring process at its Capital Markets Day on September 28. The employment plan is based on an agreement signed with the IG Metall trade union at the end of 2025. The agreement envisages reducing or outsourcing approximately 11,000 positions. Therefore, the 4,000-person reduction already implemented does not entirely represent direct job cuts.
The company plans to adjust its annual production capacity of 11.5 million tonnes to an annual shipment target of 8.7–9 million tonnes. Another step in the restructuring, the separation from Hüttenwerke Krupp Mannesmann (HKM), was completed in summer 2026.
Thyssenkrupp Steel CEO Marie Jaroni said significant milestones had been reached in the restructuring process and that the first effects of the measures were beginning to show in the company’s performance. Jaroni said the company’s goal was to develop thyssenkrupp Steel into a more profitable and resilient producer.
Thyssenkrupp Steel expects restructuring and cost-efficiency measures to contribute more than EUR 800 million to adjusted EBITDA. The company said agreements had been reached for more than half of these measures and implementation was ongoing. Its medium-term targets include adjusted EBITDA of at least EUR 1.2 billion, an EBITDA margin of at least 11% and positive free cash flow.
Philipp Conze, the company’s Chief Financial Officer, said the profitability targets are largely based on measures under thyssenkrupp Steel’s own control. Conze highlighted the restructuring agreement with the trade union, the cost-efficiency program and the separation from HKM in this regard.
The company plans to focus on product value rather than production volume. According to the company, approximately two-thirds of its portfolio consists of premium steel grades. Having invested more than EUR 1 billion in modernizing its production network in recent years, thyssenkrupp Steel is also continuing its transition toward low-carbon steel production with the direct reduction plant under construction in Duisburg.
Marco Richrath, the company’s Chief Operating Officer, said modernization investments support the production of high-quality steel products. Richrath added that the direct reduction plant in Duisburg is advancing the company’s transition to low-carbon production.
The separation of thyssenkrupp Steel Europe from thyssenkrupp AG remains one of the company’s strategic objectives. The possibility of the parent company retaining a minority stake is also being considered.
Thyssenkrupp Steel said demand in the markets where it operates has generally remained stable. According to the company, trade measures in place since July 2026 are supporting the European steel market, with more than 80% of the European flat steel market covered by the new quota and tariff arrangements.

European HRC prices rise amid muted trading activity
Steel hot-rolled coil prices in Northern Europe and Italy edged higher on Monday September 28, although trading activity remained subdued in both markets amid cautious buying, sources told Fastmarkets.
In Northern Europe, market participants reported an absence of fresh bookings at the start of the week, with high stock levels keeping distributors and steel service centers on the sidelines.
A buyer source reported mill offers quoted within €760-770 ($866-877) per tonne ex-works, but characterized these targets as unreasonable.
“There is absolutely no activity. This is just wishful thinking from the mills,” the source said.
As a result, those offers were discarded from the daily index calculation.
The same buyer pegged workable levels at €740-750 per tonne ex-works, noting that €750 per tonne represented the absolute ceiling for any negotiations under current conditions.
A seller source also indicated realistic workable levels at €740-750 per tonne ex-works.
“The stock overhang in the market is still pretty large, and that takes more time to get cleared out. It obviously reduces the need for fresh steel from mills or from imports,” the seller source told Fastmarkets. “It remains a bit of a wait-and-see situation.”
Consequently, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €745 per tonne on Monday September 28, up by €3.33 per tonne from €741.67 per tonne on Friday September 25.
The index was unchanged week on week and up by €3.75 per tonne month on month.
In Italy, trading activity remained constrained by cautious downstream buying.
A buyer source indicated workable price levels within €730-745 per tonne ex-works.
“This is the limit that mills have reached. It will be difficult to further increase the prices,” the buyer told Fastmarkets.
A seller source indicated achievable levels slightly higher, at €740-750 per tonne ex-works.
As a result, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €741.25 per tonne on Monday September 28, up by €3.75 per tonne from €737.50 per tonne on Friday September 25.
The index was up by €7.50 per tonne week on week and by €23.75 per tonne month on month.
Geopolitical disruptions push up freight costs and alter steel trade flows
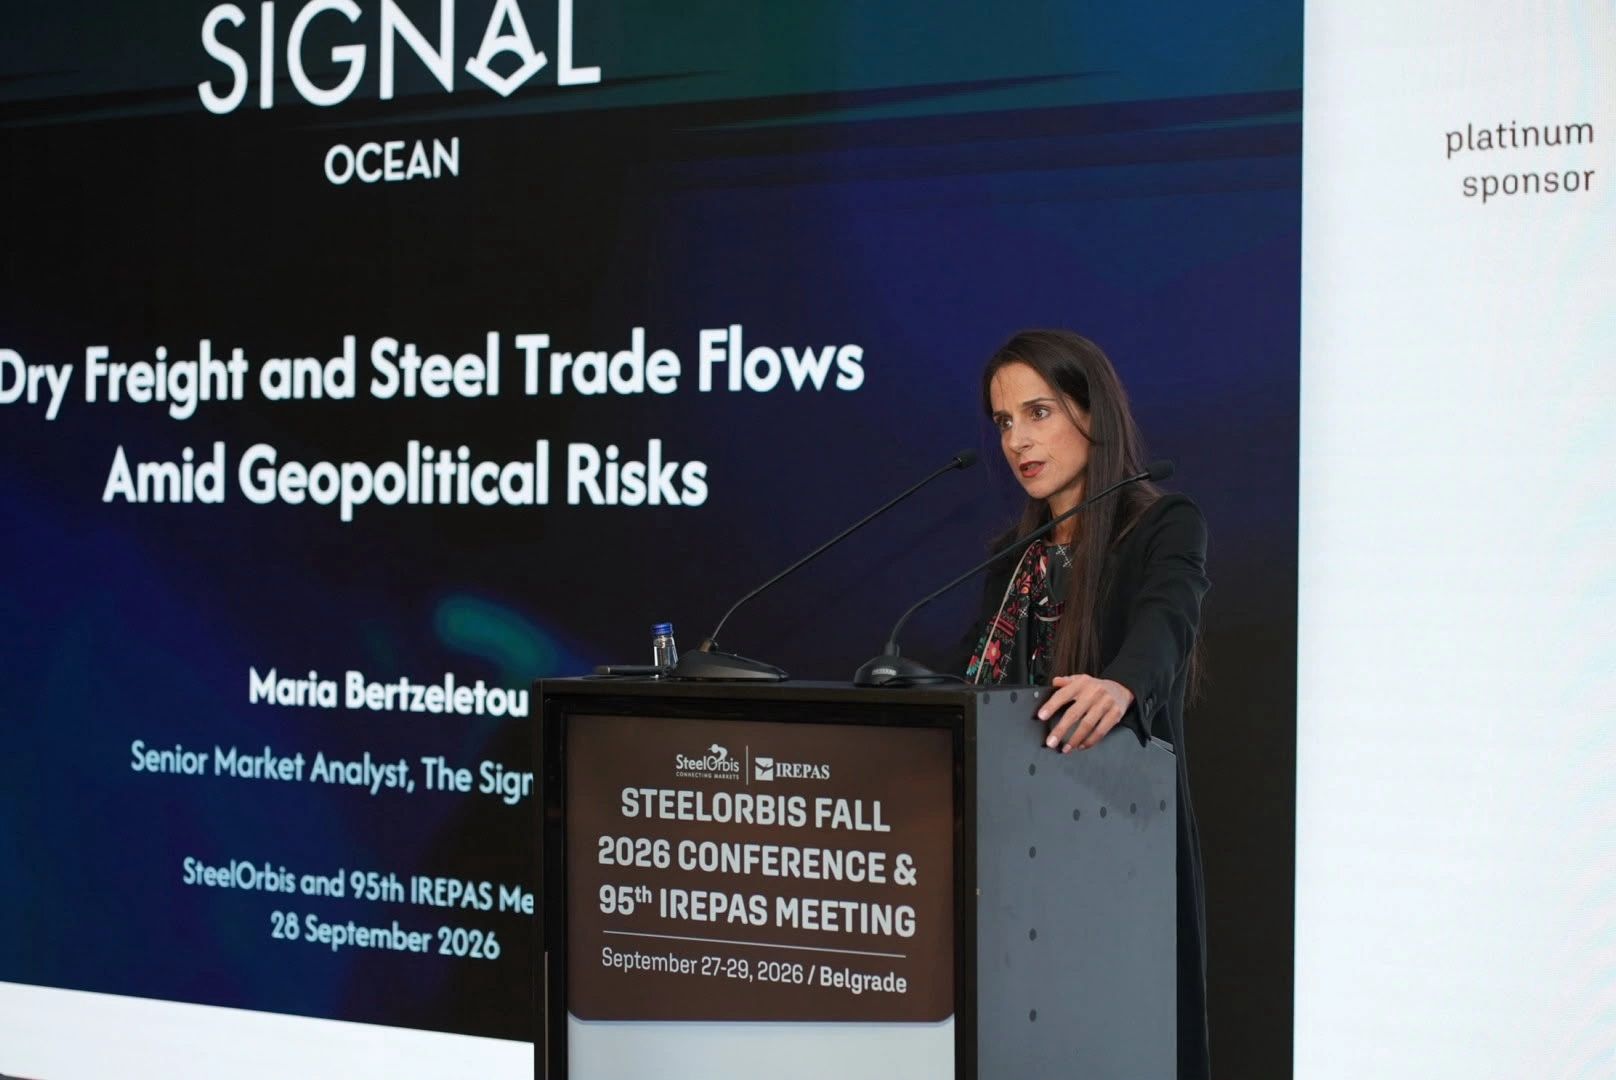
Geopolitical disruptions are increasingly affecting steel trade flows, voyage lengths and freight costs, according to Maria Bertzeletou, senior market analyst at The Signal Group, speaking at the SteelOrbis Fall 2026 Conference & 95th IREPAS Meeting in Belgrade on September 28.
Ms. Bertzeletou stated that dry bulk freight earnings have increased significantly. During September 1-23, average Capesize earnings reached $50,300/day, up 96 percent year on year, while Panamax, Supramax and Handysize earnings averaged $21,300/day, $19,700/day and $16,900/day, respectively. She stressed that, for individual steel shipments, freight costs also depend heavily on whether a suitable vessel is available in the required region.
Black Sea risks add to freight and insurance costs
In the Black Sea, the expansion of the London-based Joint War Committee’s listed war-risk zone has added to shipping risks and insurance costs. Bertzeletou cited estimates indicating that war-risk insurance could reach three to five percent of a vessel’s value. Higher freight quotations have been reported for Black Sea billet shipments to Turkey, although she noted that she had not seen completed fixtures confirmed at those levels.
Meanwhile, scrap cargoes are competing with steel for available tonnage. Scrap demand has supported Mediterranean voyages, and cargo demand combined with limited vessel availability has strengthened Handysize rates in the US Gulf. Bertzeletou also cited indications of strong rates for scrap shipments into the eastern Mediterranean, while stressing that these were market indications rather than confirmed fixtures.
China accounts for 41.6 percent of recorded seaborne steel volumes
Turning to steel trade, China accounted for 41.6 percent of seaborne steel volumes recorded by Signal Ocean, followed by Japan with 10.8 percent and South Korea with 9.2 percent. Destinations were considerably more fragmented.
Overall global seaborne steel loadings declined by 3.3 percent year on year in January-August 2026, while August volumes increased to approximately 23.2 million mt from 21 million mt in August 2025.
Black Sea steel-related shipments fall sharply
The effects of geopolitical disruptions were particularly visible in the Black Sea. For the selected Russian Black Sea and Azov Sea ports and steel-related cargoes, July-August loadings fell by approximately 79 percent year on year, while recorded voyages decreased to 21 from 135. No voyages for the selected ports and cargoes were recorded during September 1-22.
Russian Baltic steel-related loadings also weakened, averaging 0.62 million mt per month in July-August, compared with 0.73 million mt in January-June. Russian steel and related cargoes discharged in the eastern Mediterranean fell by 39 percent year on year to 3.64 million mt in January-August. Ukrainian seaborne trade has also fallen sharply. For the selected steel and mineral cargoes, January-August loadings declined from 7.7 million mt in 2021 to just 0.5 million mt in 2026.
Steel intake through Strait of Hormuz declines 65 percent
Disruptions were also evident around the Strait of Hormuz. A selected AIS waypoint indicator remained significantly below its 2023-25 seasonal average after February 2026. Nevertheless, a separate transit log recorded 98 passage events by bulk carriers and multipurpose vessels during September 1-23, demonstrating that vessels continued to transit the strait.
Selected steel intake through the Strait of Hormuz totaled approximately 3.8 million mt in January-August 2026, down around 65 percent from 10.95 million mt in the corresponding period of 2025.
Higher bunker prices add pressure to freight quotations
Higher fuel costs have added further pressure to freight. The global 20-port average price for very low sulphur fuel oil increased by approximately 62 percent, from $543.5/mt on February 27 to $881/mt on September 24.
Bertzeletou stated that higher bunker prices increase voyage costs and put upward pressure on freight quotations, although the impact varies according to fuel grade, port and contractual terms. She concluded that freight levels for individual steel shipments ultimately depend on the specific cargo, route and vessel availability at the time of fixing. According to Bertzeletou, geopolitical risks are expected to play an increasingly important role in determining freight costs alongside the underlying balance between vessel supply and cargo demand.
Author: SteelOrbis Editorial Team

IREPAS chairman: Geopolitical tensions and higher costs reshape global steel markets
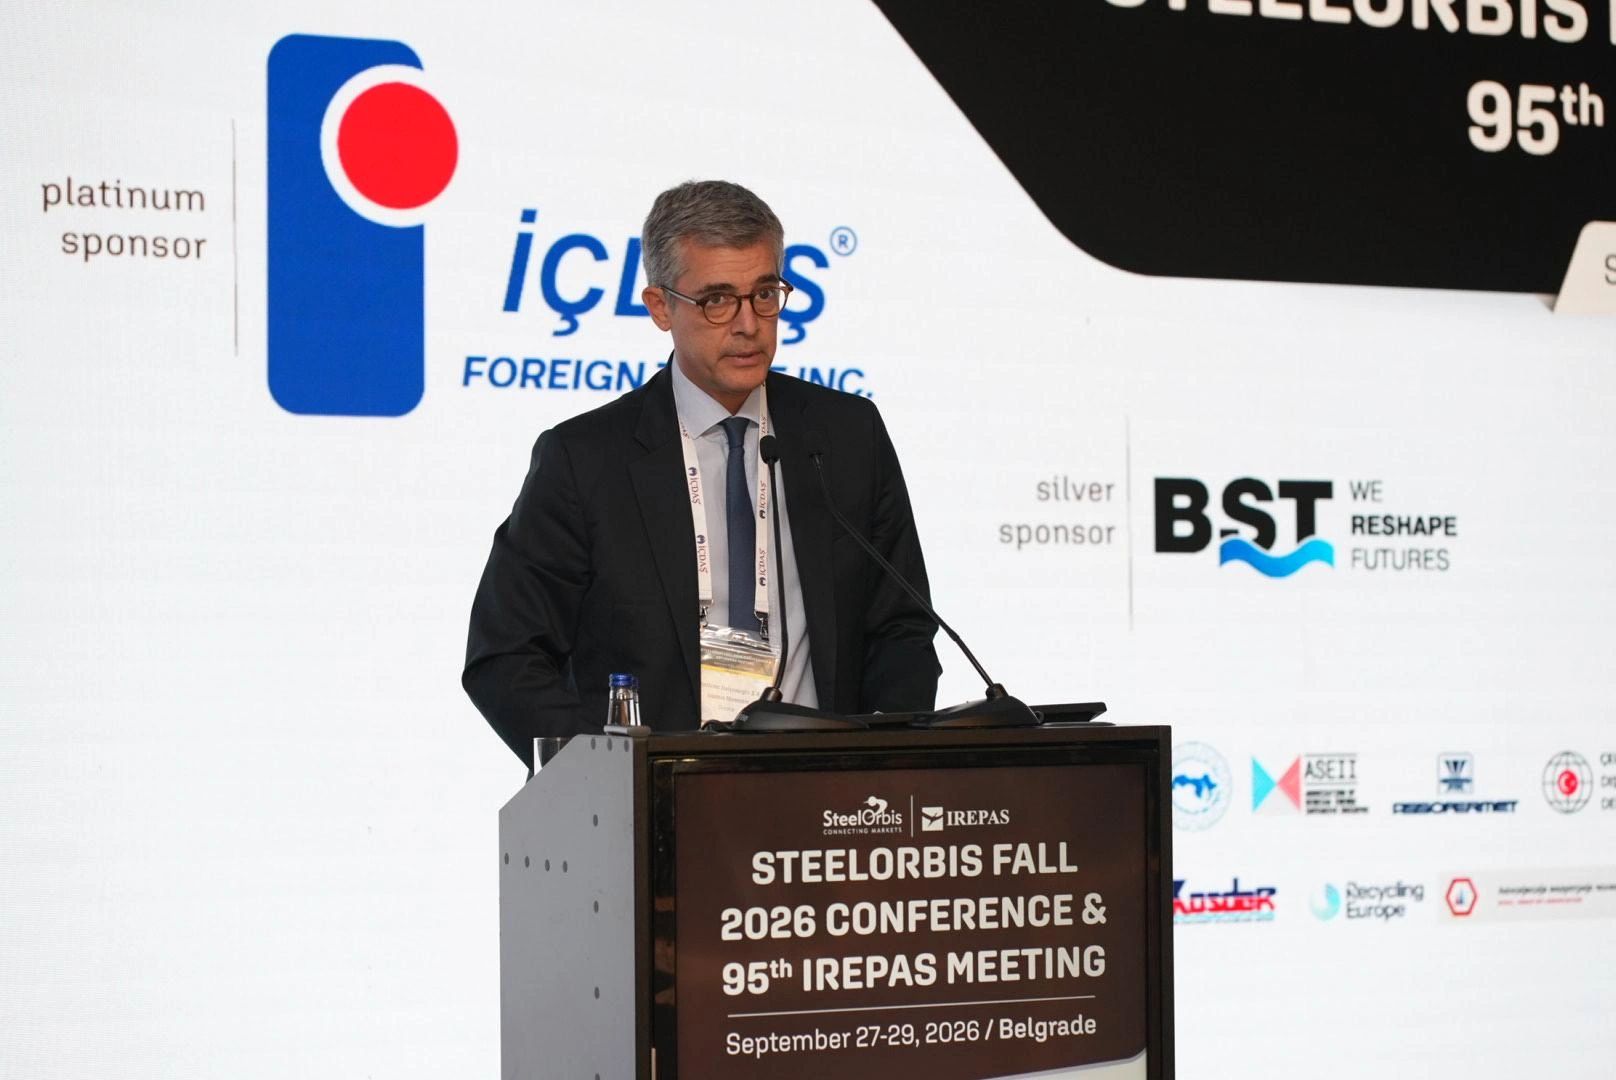
Ioannis Manessis, chairman of IREPAS, the global association for longs producers and exporters, has delivered the welcome speech at the SteelOrbis Fall 2026 Conference & 95th IREPAS Meeting, being held in Belgrade, Serbia, on September 27-29.
Mr. Manessis stated that the global steel industry is operating in an increasingly challenging environment characterized by geopolitical conflicts, shifting trade flows, higher costs and relatively weak demand. According to the IREPAS chairman, the deteriorating situations in the Black Sea and Iran are having a significant impact on steel markets and international trade. Damage to ports and vessels’ reluctance to sail have made trade in the Black Sea extremely difficult, while attacks on bulk carriers and oil tankers have also created significant challenges for trade in the Middle East.
Higher energy prices increase costs across steel value chain
Against this backdrop, energy prices, including oil, natural gas and coal prices, have increased, in some cases significantly. Manessis noted that these increases are raising costs for steel producers, scrap suppliers and shipping companies, affecting the entire steel value chain.
At the same time, the industry is facing an increasingly restrictive global trade environment. The IREPAS chairman highlighted the EU’s Carbon Border Adjustment Mechanism (CBAM) and its safeguard measures implemented after July 1, US tariffs, scrap trade restrictions in around 40 countries worldwide and other trade measures affecting steel markets. He also pointed to China’s recent efforts to prevent its steel industry from offering products at excessively low or loss-making prices, stating that these measures already appear to be having an impact on the market.
Rising costs drive steel prices despite weak demand
Meanwhile, higher interest rates are putting additional pressure on consumers as authorities seek to contain inflation. Manessis stated that, apart from demand related to the expansion of artificial intelligence data centers, global demand for steel products remains relatively weak.
According to the IREPAS chairman, demand is therefore not currently determining the direction of the market, with rising costs instead becoming the key factor. As a result, steel prices are increasing in almost all markets despite weak demand. Manessis added that, although the current environment remains difficult to navigate, higher prices are allowing trade to continue and creating opportunities for market participants.
Author: SteelOrbis Editorial Team
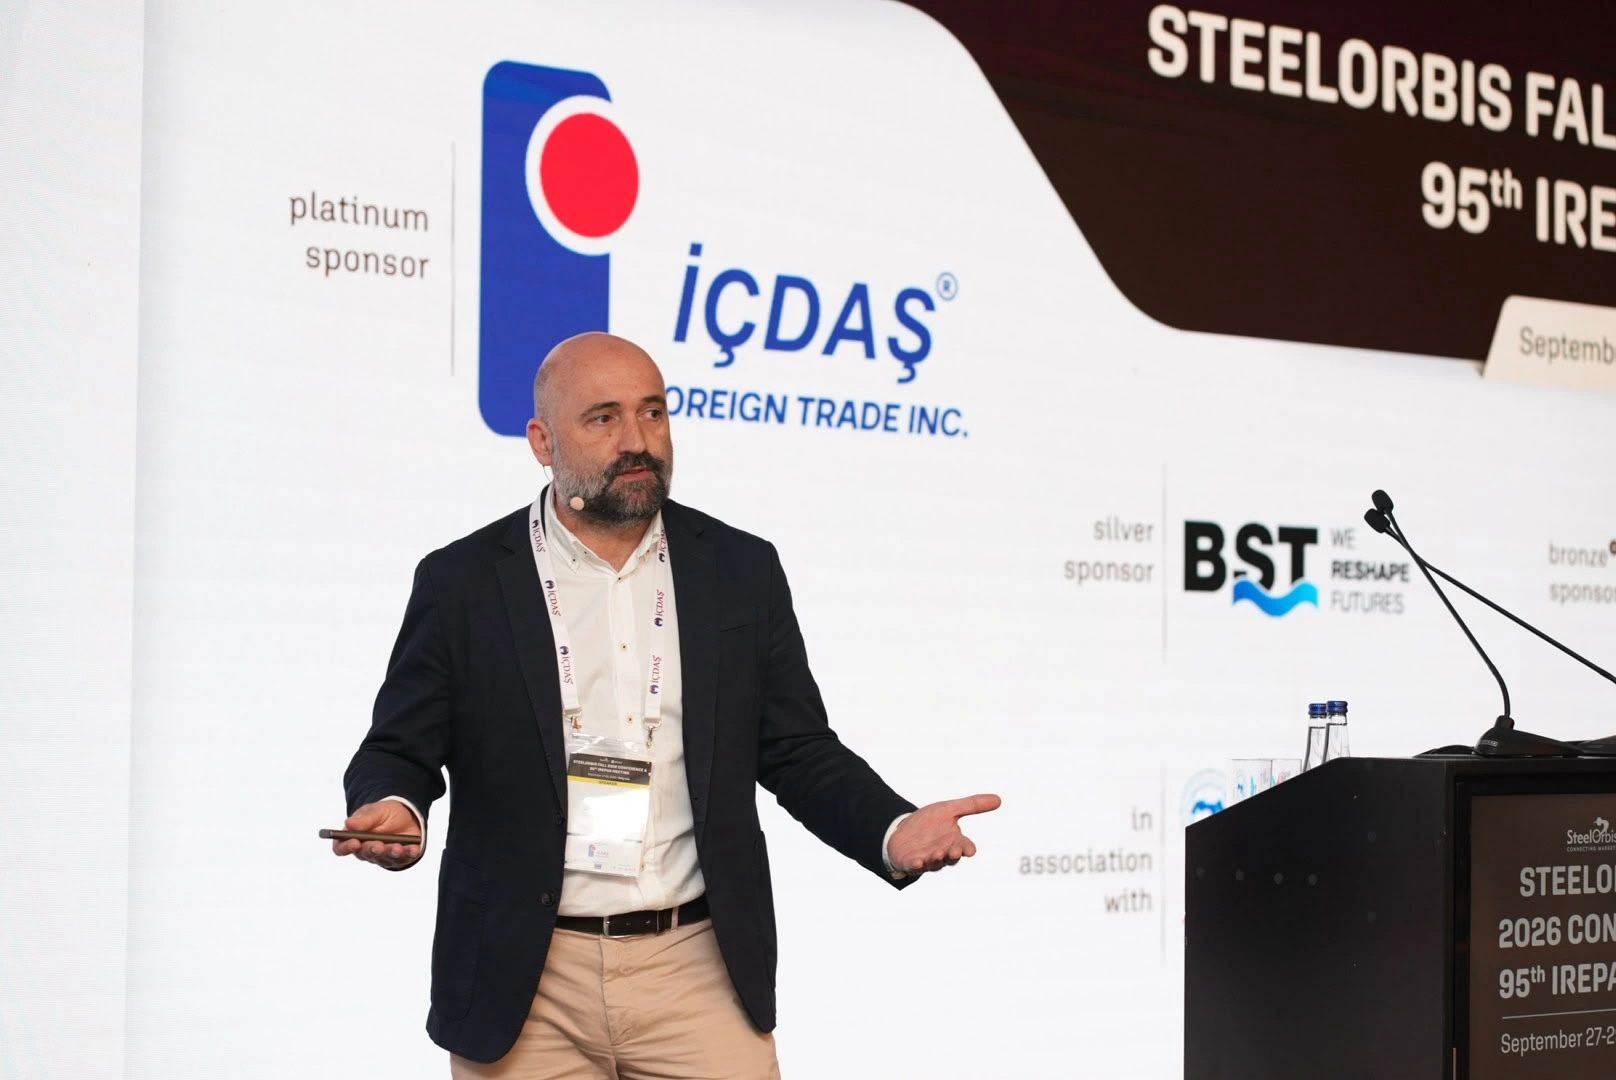
Steel suppliers should prepare early for CBAM verification requirements
Jerónimo Casas, global product manager for climate change and sustainability solutions at SGS, discussed verifier accreditation, emissions monitoring, data integrity and reporting deadlines in his “Spotlight on CBAM” presentation at the SteelOrbis Fall 2026 Conference & 95th IREPAS Meeting held in Belgrade on September 27-29.
Mr. Casas said SGS had applied for CBAM verifier accreditation through SGS Belgium and SGS Italy. Final decisions on both applications are pending. According to Casas, accreditation granted to either affiliate would allow it to carry out CBAM verification across the EU. He encouraged operators to request verification proposals now.
Monitoring plan identified as key challenge for operators
Drawing on SGS’s pre-verification work, Casas identified the monitoring plan as a key challenge for operators. He said CBAM requires a monitoring system, with the plan explaining how an installation collects data, calculates emissions and meets the applicable requirements. The plan will be examined during verification. Casas noted that the relevant regulatory section contains 22 points that operators should review and address where applicable.
The monitoring plan covers the installation and its processes; goods identified by CN code and functional unit; CBAM production processes and routes; non-CBAM goods by process; relevant benchmarks; monitoring methods and calculation factors; emission sources and source streams; system boundaries; precursors used in each process; and controls over data quality. Casas cited Annex II, section A.5 of Commission Implementing Regulation (EU) 2025/2547 for the plan’s minimum contents.
Casas also discussed specific embedded free allocation (SEFA), which he said must be calculated and verified alongside reported embedded emissions. He explained that EU installations receive free allowances based on sector-specific benchmarks and described SEFA’s role in accounting for that free allocation under CBAM. Casas advised operators supplying the EU market to prepare the relevant information and EU importers to discuss it with their suppliers.
Verifier independence and data integrity under CBAM
On verifier independence, Casas said a company that has implemented an installation’s emissions monitoring system could not then verify the same system. He added that, using another company in the same corporate group did not automatically remove a conflict of interest and that commercial referral agreements with consultants could also present a conflict. National accreditation bodies examine such arrangements as part of their assessments.
Casas also described several checks intended to address fraud and data manipulation. Operators reporting actual emissions must collect the required data and explain their calculations under the European Commission’s methodology. An initial verifier site visit is mandatory, he said, allowing the verifier to examine the installation, measurement equipment, calculations and underlying records. Competent authorities and the European Commission can request further information about unusual or apparently incorrect reports, while data manipulation can lead to sanctions.
Verified emissions data can reduce CBAM costs
Casas compared three reporting options, describing verified emissions from both an installation and its relevant precursors as producing the lowest CBAM cost, provided suppliers are ready to supply the data. A second option uses verified installation emissions and default values for precursors. Under a third option, default values alone require no verification but are described as producing the highest CBAM cost. Casas said verification allows operators to report actual values and gives declarants information for purchasing decisions.
For declarants, he recommended contractual requirements for verified supplier emissions data, with financial consequences if the data are not provided. He also suggested agreeing on emissions thresholds and consequences if they are exceeded, checking whether suppliers have completed pre-verification, and supporting improvements to their monitoring and reporting systems.
Companies urged to prepare ahead of CBAM reporting deadline
Casas stated that CBAM certificates will be available for purchase from February 2027, while September 30 is the deadline for submitting verified reports and surrendering certificates. Casas urged companies to engage verifiers and suppliers early, warning that demand for verification could be concentrated near the deadline.
He said early planning was particularly important for iron and steel supply chains. Downstream producers may need verified emissions data from suppliers of precursors; without those data, they may have to use default values for the precursors even if emissions from their own operations have been verified. Casas also advised declarants to plan certificate purchases and submit their reports ahead of the deadline to avoid difficulties caused by heavy use of the reporting platform.
Author: SteelOrbis Editorial Team

AM Eisenhüttenstadt interrupts production
ArcelorMittal has halted parts of production at its Eisenhüttenstadt strip mill in Germany, Kallanish hears from the company.
The decision was preceded by irregularities noticed in the processes of the mill’s blast furnace, the company explains. Its technicians are working to stabilise operations and expects to resume regular production shortly.
Eisenhüttenstadt produces 2.5 million tonnes of crude steel/year.
The disturbance at Eisenhüttenstadt comes at a time of rumours about production cutbacks at the major strip producers in western Europe, partly due do planned maintenance, but also because of extraordinary circumstances.


Tata, Dutch authorities extend agreement on environmental issues
Tata Steel Nederland (TSN) and several Dutch authorities have agreed to extend the Joint Letter of Intent (JLoI) on the transition to low CO2 steel production and to improve the environment at Ijmuiden.
One year ago, the JLoI set out agreements on targets, financing and timelines, designed to create a healthier living environment and reduce CO2 emissions around the Ijmuiden site. “This joint signing demonstrates our shared belief in the course of more sustainable steel production in the Netherlands, also known as the Green Steel Plan (Groen Staal Project),” TSN noted then.
The original 47-page document was signed by the Ministry of Economic Affairs and Climate, the Ministry of Infrastructure and Water Management, the Province of North-Holland, by TSN and its parent Tata Steel. The parties have now extended the JLoI by five months until 1 March 2027. The extension will provide the parties with additional time to address outstanding matters and work towards a realistic approach to the integrated health and decarbonisation project, Kallanish understands.
Essentially, the agreement and its extension address environmental issues that led to penalties imposed by authorities on TSN (see Kallanish passim). Under the new agreement, TSN will explore options for the controlled closure of its coke and gas plants in consultation with the relevant authorities.
At the same time, efforts between involved parties continue to progress toward a solution for steel slag. The Dutch regulatory framework governing the production, storage and transportation of steel slag has become increasingly complex, TSN notes.