


Euro area construction output stable in July 2026 from June
According to first estimates released by Eurostat, the Statistical Office of the European Union, in July this year the seasonally-adjusted production of the construction sector in the European Union member states (EU-27) decreased by 0.3 percent compared to June this year and fell by 1.8 percent compared to the same month of 2025. In June, production in the construction sector had moved down by 1.3 percent month on month.
In the euro area, the seasonally-adjusted production of the construction sector in July remained stable month on month and moved down by two percent year on year. In June, production had decreased by 1.5 percent month on month.
Building construction in the EU-27 in July moved down by 0.4 percent month on month and down by 5.6 percent year on year, while civil engineering output in the region decreased by 0.9 percent month on month and decreased by 0.4 percent year on year. In the euro area, building construction remained stable month on month and was down by 6.4 percent year on year, while civil engineering output in the region rose by 0.6 percent both month on month and year on year.
As compared to June, construction output in July increased by 2.8 percent in Belgium, by 2.1 percent in the Czech Republic, and by 1.9 percent in Slovakia, while it decreased by 4.7 percent in Hungary, by 3.8 percent in both Poland and Sweden, and by 2.2 percent in Austria.
As compared to July 2025, construction output in July this year increased by 12.8 percent in Finland, by 11.6 percent in Slovenia and by 4.8 percent in Bulgaria, while it decreased by 12.2 percent in Hungary, by 9.7 percent in Spain and by five percent in France.


European HRC prices climb despite weak demand; import risks and supply concerns support market
Domestic prices for steel hot-rolled coil (HRC) edged up in both Northern Europe and Italy on Monday September 21, while sources reported steady but gradual price increases linked to weak demand and limited import activity.
In Northern Europe, sources said prices were gradually increasing but demand remained weak as there was no major restocking in the market.
A supplier source in the region indicated workable HRC levels for October delivery at €740-750 ($850-861) per tonne ex-works, adding that it was aiming to achieve €760 per tonne ex-works, depending on how demand develops.
“Mills are carefully observing the situation,” the supplier said on Monday.
The same source said HRC import activity into the region was very quiet due to the high risks related to safeguard quotas and Carbon Border Adjustment Mechanism (CBAM), so buyers were staying a bit away for the moment.
The supplier also said that it was seeing prices mostly stable in the upcoming period, with an ambition to reach levels around €800 per tonne ex-works in the domestic market by the end of the year.
Meanwhile, a distributor source in Germany reported offers for material within the range of €750-760 per tonne delivered on Monday, which nets back to €730-740 per tonne ex-works, adding that the market was very quiet and demand remained weak.
The same source said that levels around €720 per tonne ex-works, which were previously quoted by sources in the market on Friday September 18, were no longer achievable.
On the other hand, a buyer source said on September 21: “Whilst there may be odd deals at lower levels, we would agree that around €750 [per tonne ex-works] is a fair estimate, trending to €775 [per tonne ex-works].”
As a result, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €745 per tonne on September 21, up by €7.50 per tonne from €737.50 per tonne on September 18.
The index was also up by €7.50 per tonne week on week and by €22.92 per tonne month on month.
In Italy, the picture of achievable prices in the market remained slightly blurred, with buyers and suppliers reporting different levels.
Latest offers were reported at €750 per tonne delivered, equivalent to around €735 per tonne ex-works after deducting €15 per tonne in delivery costs, a trade source said on Friday September 18.
The same source added that there was limited room for negotiation, indicating workable levels for hundreds of tonnes at €750 per tonne delivered and for larger volumes at €740-745 per tonne delivered (€725-730 per tonne ex-works) on the same day.
Meanwhile, a distributor source said on Monday that the minimum levels it was hearing were within the range of €730-740 per tonne ex-works, declining to offer lower prices.
“Honestly, I think that in this moment buyers are not realistic. Price is going up week after week and some numbers they declare are not anymore available, according to my opinion,” the same source said.
A second trade source quoted achievable levels in the range of €730-735 per tonne ex-works on Monday, in line with the latest deals heard in the market on September 17. The source added that prices at €725 per tonne ex-works sounded “optimistic” under current market conditions.
Thus, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €733.75 per tonne on September 21, up by €3 per tonne from €730.75 per tonne on September 18.
The index was down by €2.50 per tonne week on week but up by €21.25 per tonne month on month.
One of the main factors affecting HRC availability in Italy remained the uncertain future of the former Ilva steelworks in Taranto, which has been ordered to suspend hot-end operations by October 28.
However, market participants were uncertain how the situation would develop. Italy’s Court of Cassation, the highest court of last resort in the country, is scheduled to hear appeals against the shutdown order on October 20, only days before the deadline for the closure to take effect, a trade source told Fastmarkets.
As a result, many participants remained in a wait-and-see mode regarding the producer’s future and its potential impact on domestic steel supply.
At the same time, a company source at Metinvest’s Ferriera Valsider mill in Italy told Fastmarkets that it was not taking new orders yet. “We are producing but the potential space for new orders, if any, would be for December production earliest,” the same source said.

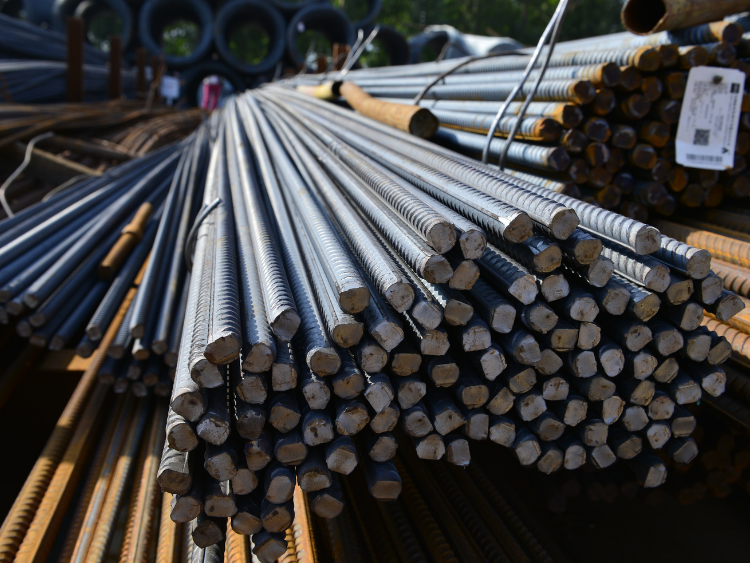
Polish domestic rebar prices rise amid higher energy costs
Polish domestic rebar prices rose in the week to Friday September 18 as producers continued to push for higher levels in response to increasing production costs.
“There is a really big cost pressure for mills. Energy prices are very high. Compared to a month ago, prices are doubled,” a distributor source told Fastmarkets.
Rising oil and energy prices continued to support higher offers, while some mills adjusted their working hours depending on energy costs.
Deals for domestic rebar were heard at 2,770-2,800 zloty ($729-737) per tonne, with offers also heard within that range. Workable levels were heard at 2,740-2,800 zloty per tonne.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, CPT Poland, rose to 2,740-2,800 zloty per tonne on Friday, up from 2,650-2,680 zloty per tonne the previous week.
In the wire rod segment, indications were heard at 2,900-3,100 zloty per tonne delivered.
Fastmarkets’ weekly price assessment for steel wire rod (drawing quality), domestic, delivered Poland, remained unchanged at 2,900-3,100 zloty per tonne on Friday.

Siemens Mobility forms rail material recycling consortium
Siemens Mobility has launched a project aiming to recover materials from end-of-life trains, Kallanish learns.
It is joined by a consortium that includes railway operator Deutsche Bahn, aluminium producer Hydro, German metals recycler TSR, and steelmaker voestalpine.
The project, named “Train2Train”, brings together the full value chain, from dismantling and recycling to material processing and manufacturing. Each partner plays a critical role in creating a transparent and circular material loop, Hydro says.
TSR will dismantle the rail vehicles and retrieve the materials with the aim of recycling them into new rail parts. It will ship steel to voestalpine for recycling and further production. TSR will also recover aluminium and send it to Hydro, to its recycling facility in Ghlin, Belgium.
The project aims at reusing material from end-of-life trains, recycling them to become materials that can again be used within the railway industry. Austrian partner voestalpine is active in making rails and in railway technology. However, it has not issued an announcement on the project to explain its further use of the recycled steels.
Italy’s ABS opens hub for Scandinavian operations
ABS – Acciaierie Bertoli Safau SpA, the Italian maker of special bar qualities (SBQs), inaugurated last week its new distribution and service centre in Värnamo, Sweden, the firm tells Kallanish.
This marks a shift for Danieli-owned ABS from a producer of special steels to an industrial partner that is closer to the customer, the company says. This involves integrating product, stock availability, processing, logistics and metallurgical consultancy within a single facility, it adds.
The new site is known as ABS Steel Nordic Service Centre. It covers an area of approximately 25,000 square metres, with a newly constructed building spanning 5,500m². It stores structural steel, high-strength and case-hardened steel, free-cutting steel and micro-alloyed steel. It operates cutting equipment that can process from 10mm to 560mm thick product.
Värnamo will be the hub for ABS’s Scandinavian operations. Last November at the Elmia Subcontractor trade fair, ABS announced the establishment of a new unit for Scandinavia, ABS Steel Nordic, plus the greenfield construction of the service centre.
“We have been operating here in Sweden with our own company since 2012, but, now, we are making a huge investment,” Elmia’s website quoted Eric Lennermark, chief executive of ABS Steel Nordic, as saying then. He noted that ABS is the number two SBQ supplier in the Nordics, with an annual sales volume of 55,000 tonnes.

Arvedi/CLN merger antitrust ruling expected early October
The EU antitrust review of the merger between Italian steelmaker Arvedi and troubled coil service centre ArcelorMittal CLN Distribuzione Italia (AMCLN) is expected to conclude on 2 or 3 October. The presentation of Arvedi’s industrial and financial plan to trade unions should follow, union sources tell Kallanish.
“We hope that the Arvedi group, which in the past has resolved disputes such as those in Trieste and Terni, will take over CLN and quickly bring the crisis to an end,” an Uilm union note says.
The next meeting is scheduled for 6 October at the Rome headquarters of the Ministry of Enterprises and Made in Italy (MIMIT), where the unions hope to meet Arvedi. The firm is expected to show the industrial plan to the social partners.
“We express strong concern over the current state of the company. The majority of the approximately 400 employees across the six plants have been on short-time work schemes for several weeks now, with a significant impact on workers’ wages. To date, we have not yet received the industrial plan and, as a result, many doubts remain over future employment levels and the nature of the investments Arvedi intends to make in AMCLN,” another Fiom union note states.
The company has been reducing its output due to financial hurdles, and part of the workforce has been put on temporary layoffs.
At the end of July, Arvedi submitted a binding offer to acquire the service centre. Earlier this year, ArcelorMittal was seeking full control of AMCLN, its joint venture with CLN. The process comes amid continued pressure on the European automotive sector, a key market for the business.
In May, the European Commission cleared the merger between ArcelorMittal and AMCLN Distribuzione Italia. However, the Italian government has invoked its “golden power” authority to impose conditions on the merger, suggesting the government has pushed for an Italian buyer instead of ArcelorMittal.
The Italian government blamed ArcelorMittal for failing to relaunch Acciaierie d’Italia – the former Ilva – and is now seeking €7 billion ($8.08 billion) in damages. This may have influenced the political dynamics around the merger.
The golden power is a tool the Italian government can use to block or impose conditions on corporate acquisitions considered strategically important for the country. This is the case even when the deal has been approved by European competition authorities (see Kallanish passim).
Contacted by Kallanish, Arvedi and ArcelorMittal did not comment before press deadline.

Railway closures in the Balkans could affect scrap trade


EU steel TRQs fluid with trade, decarbonisation trends
The EU’s steel protections will continue to evolve subject to both domestic and global industry trends, according to Eurofer Deputy Director General Karl Tachelet, describing the steel tariff-rate quota (TRQ) framework as a “living instrument.”
Tachelet, responsible for International Affairs at EU steelmaking association Eurofer, discussed possible developments for the mechanism at the EUROMETAL Regional Meeting Central Europe 2026 in Warsaw on 16 September, as part of the panel on ‘Industrial Competitiveness and Regulation.’
According to Tachelet, while the EU’s steel protections have traditionally been time-limited (e.g the 5-year terms for anti-dumping protections), July’s overhaul of the TRQ framework has the potential to be permanent, though still remains a “living instrument.”
This dynamic nature of the TRQ regulation will not only be subject to developments in the international steel markets – after all, combating overcapacity-related import pressure is its core purpose – but also the decarbonisation of the EU’s domestic steel sector, Tachelet said, suggesting that the Commission would see no reason to keep the TRQs if its steelmakers failed to modernise their operations at pace with the bloc’s climate ambitions.
Against the doom-and-gloom sentiments more commonly associated with the European steelmaking sector, Tachelet was notably more positive, stating that in some ways, Europe represents something of an “investment hotspot” in global steelmaking, if interpreted more broadly as incorporating decarbonisation projects, rather than just capacity expansion.
The traditional model of integrated steelmaking “is not sustainable” in the context of the EU’s climate ambitions, said Tachelet, seeing the future of the European steel industry as belonging to “a new type of competitiveness, beyond price.”
EU advantages
The Eurofer Deputy Director General highlighted the EU’s significant advantages for the low-carbon transition: its abundant high-quality scrap reserves, its technological competencies and expertise, and its large manufacturing sector – i.e. “demand” – seeing a need to shield these competencies as the EU defines and realises its new competitive advantages.
Tachelet stressed that some of Europe’s decarbonisation barriers would be very difficult to overcome, but that Europe’s industries nevertheless have to “find a new competitiveness,” and questioned the long-term viability of new blast furnace assets and capacities in, for example, India, in “20-30 years”.
Dow Jones Energy tracks steel decarbonisation projects globally and by region, as detailed in our Global Green Steel Profile.
The European Commission does appear to be taking a harder stance on the inevitability of the industrial transition, with July’s reform proposal for the EU Emissions Trading System (ETS) introducing new conditionality mechanisms for producers to emit portions of their production free-of-charge via ‘free allocation’.
Dismantling the TRQs due to a lack of decarbonisation progress would represent a massive relaxation of the EU’s new import restrictions, but as discussed on the panel, the inverse is much more likely: that the Commission moves to further intensify protections by changing the basis of volume allocations to the TRQs from traditional origin determinants, to the country of “melt and pour” (MnP).
Melt and Pour, and its complications
Under the new TRQ regulation, the Commission must assess whether to change the allocation rules to MnP by the end of June 2028, which could then be backed with a legislative proposal. That deadline falls after the review to assess whether to extend the TRQs scope downstream to steel-containing goods, scheduled for the end of June 2027.
As the steel TRQ rules currently stand, the MnP clause operates as a traceability mechanism, with importers required to declare the country of MnP for in-scope products from 1 October, to be evidenced with Mill Test Certificates.
As described by EUROMETAL President Alexander Julius, switching allocations to the country of MnP would be an extreme change for steel imports, with the panelists commonly considering potential interactions between MnP allocations, and the extension to downstream steel-containing goods, as highly complex. Julius was also against the inclusion of scrap content and sourcing reporting requirements in the MnP rules, considering that level of international traceability to be “completely unworkable.”
Tachelet suggested that Eurofer was in support of MnP allocations, but also recognises that downstream MnP provisions could become very complicated.
The ‘value chain’ perspective
The Warsaw conference took a unique approach, focusing entirely on the urgent need to extend the EU’s new steelmaking protections downstream to steel-containing manufactured goods, without which the European value chain risks existential erosion from substitutive downstream imports.
Dow Jones Energy was in attendance for the sessions, and later moderated the steel production panel alongside panelists Tomasz Plaskura, CMO East Europe for ArcelorMittal Europe Flat Products; Jiří Mravec, Head of Innovation and Transformation at Czech steelmaker Třinecké železárny; and Radek Strouhal, CEO of Czech steelmaker NOVÁ HUŤ.
The sessions demonstrated unanimous agreement among steel sector representatives – including steelmakers – that downstream protections are indeed urgently necessary to preserve Europe’s industrial base, with a scope extension of both the newly intensified TRQ framework, and the Carbon Border Adjustment Mechanism (CBAM), considered the most appropriate strategy.
Distribution representatives emphasised that these extensions should not be seen as “support,” but rather a “level playing field,” allowing downstream industries to pass on upstream steelmaking’s inherently inflationary policy effects without losing competitiveness to substitutive imports, via the extension of those same policy protections.
Jiří Mravec stated that concerns over export competitiveness could no longer be allowed to delay the extension of trade protections across the entire steel value chain, emphasising the need to ensure the survival of steel demand within the EU. Alexander Julius expressed a similar position, considering the EU’s export markets as already “lost” to Chinese industrial overcapacity, requiring a much more defensive approach from regulators to halt the same trend at home.
Tomasz Plaskura of ArcelorMittal spoke of the importance – and opportunity – of consolidating the voice of the EU’s downstream steel sector representatives on the panel, saying that European authorities had never before been so responsive and willing to protect its industries, in recognition of its longstanding competitiveness burdens.
Earlier in September, EUROMETAL organised the ‘European Convoy for Industrial Competitiveness’, with Dow Jones Energy in attendance, seeking to bring visibility of the threat to European manufacturing and industry to the European Commission’s doorstep.
Author: Benjamin Steven


Nippon Steel decides to build new EAF in Slovakia
Nippon Steel, Japan’s largest integrated steelmaker, plans to build a 1.6 mt/y electric-arc furnace (EAF) at U.S. Steel Košice (USSK) in Slovakia to strengthen the mill’s long-term competitiveness and support stable supply of green steel in Europe, the company said on 16 September.
The new EAF is scheduled to start operating in 2030. Nippon Steel also plans to add an air separation unit (ASU) to support stable steelworks operations, improve energy efficiency and reduce CO2 emissions, with the ASU scheduled to start operating in 2029.
Total investment will be around EUR0.9bn ($1.04bn), including EUR3.5m from the EU Modernization Fund.
USSK currently has around 4.5 mt/y of crude steel production capacity, with two of its three blast furnaces operating. Actual crude steel output was 3.22 mt in 2025. Its key finished steel products are flat steel products.
A Nippon Steel official said the company had not yet decided whether any existing blast furnaces would be halted after the new EAF starts operating. The company will consider and determine an optimised production structure, the official said.
The official said a production base in Europe was needed as Nippon Steel expands its global production footprint in regions with growing demand. The company also expects increased EU trade measures on imported steel to make local production more suitable.
EAF production will increase the share of green steel in Nippon Steel’s output and allow the company to meet growing demand for lower-emissions steel in the region, the official added.
In May, Nippon Steel announced plans to separate USSK from U.S. Steel and make it a wholly owned subsidiary of Nippon Steel, effective 1 October. The company plans to rename the mill Nippon Steel Slovakia (NSSK) from the same date, positioning it as Nippon Steel’s key operating base in Europe.
Author: Benjamin Steven
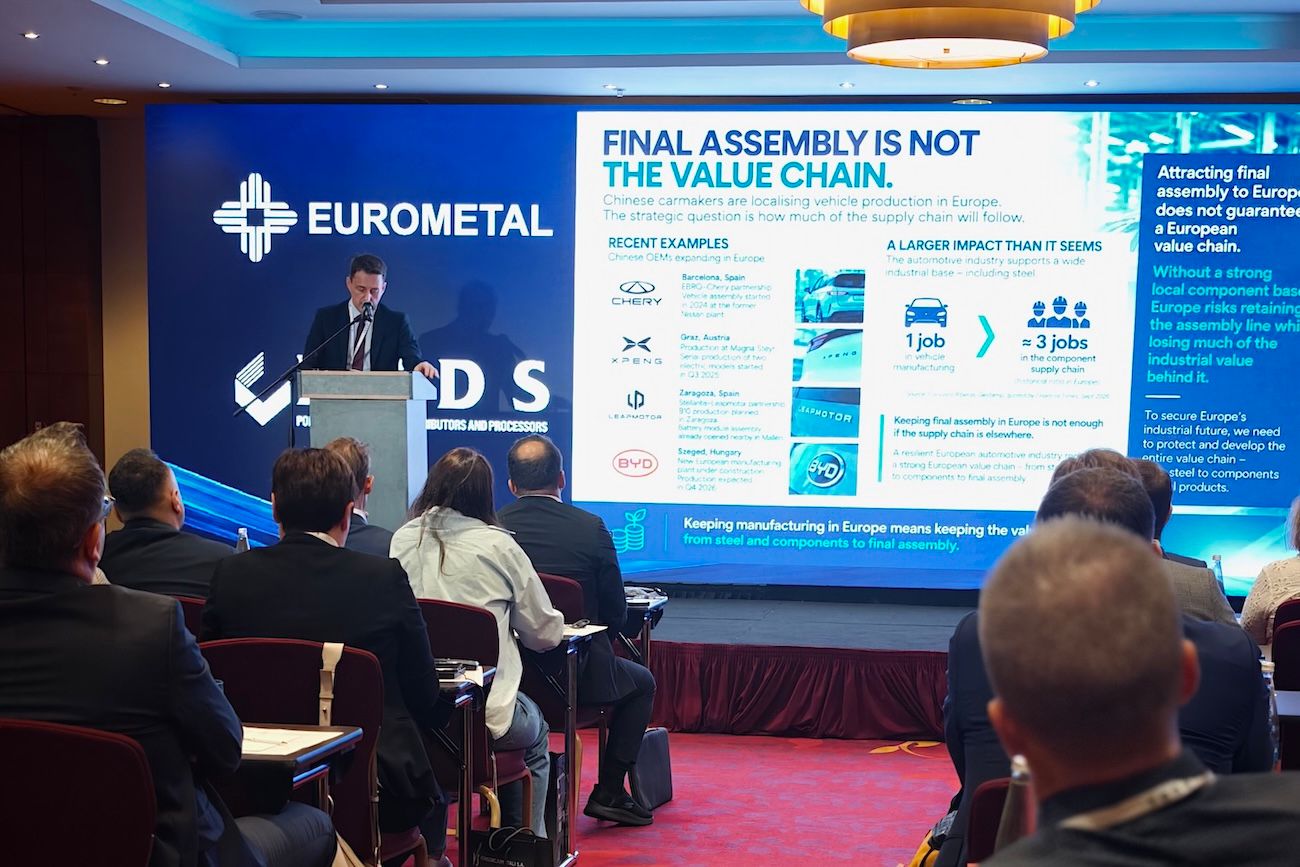
Growing CEE manufacturing input imports threaten value chain
Central and Eastern European (CEE) steel production has plummeted in the last decade, but manufacturing continues, increasingly fed by imported inputs. This raises the question of how much of the steel value chain is generating value within Europe, says Polish Union of Steel Distributors (PUDS) president Piotr Sikorski.
CEE crude steel production dropped over 40% between 2015 and 2025 to 14.1 million tonnes, but regional end-user activity did not contract by the same amount – automotive, machinery and construction sector output continues.
The region’s array of mills once owned by Liberty Group have now been rescued or are awaiting rescue. “Who is willing to own, produce, finance, and modernise the capacity that has remained?” Sikorski asked during his presentation at last week’s EUROMETAL Regional Meeting Central Europe in Warsaw, attended by Kallanish. Alternatively, “where does the steel come from instead?”
Taking Poland, Czech Republic, Slovakia, Hungary and Romania into account, the deficit of finished carbon steel, including pipe, imports rose almost 9mt in the decade to 2025, to 14.2mt. The region has become substantially more dependent on steel imports. However, rather than imports from outside the bloc, intra-EU trade accounted for 60% of that deficit growth.
Going forward, “if the production is dropping, if the steel consumption is dropping, and we have effectively narrowed the import, how we keep on manufacturing?” Sikorski asked. Looking at the automotive sector across those five countries, imports of seven groups of automotive components rose 17.5% between 2015 and 2025, with intake from outside the EU doubling. Regional automotive output grew some 7% in the period to 4.11 million units.
“We were occupied with steel imports to EU, but we seemed to forget that the threat might be somewhere else,” Sikorski noted. “The industrial base remains but the way steel and components enter its value chains is changing.”
“The declining domestic steelmaking does not necessarily mean declining final manufacturing … The picture is much more complicated as European manufacturing is becoming more and more complex with external inputs. Part of the industrial value chain can move across borders, while the final factory remains exactly where it was,” he continued.
“We already see Chinese carmakers localising production in Europe. In our region, for example, BYD in Hungary, and of course investments in production coming to Europe are always welcome. But the real question is, how much of the supply chain will follow?” Sikorski noted.
He referred to the recent Financial Times interview with Gestamp executive chairman Francisco Riberas, who said he supports Chinese automotive investment in Europe but argued that Asian manufacturers should increasingly source components locally rather than importing them. Otherwise, Europe risks becoming no more than an assembly base.
“We should not ask, is this car made in Europe? We should also ask how much of the value behind this car is created in Europe, because the steel is hidden in the value chain,” Sikorski said.
“Europe cannot remain an industrial power if it retains only the final stage of the value chain,” he concluded.
Author: Adam Smith
