

EU’s trade defences for steel shift overseas competition downstream
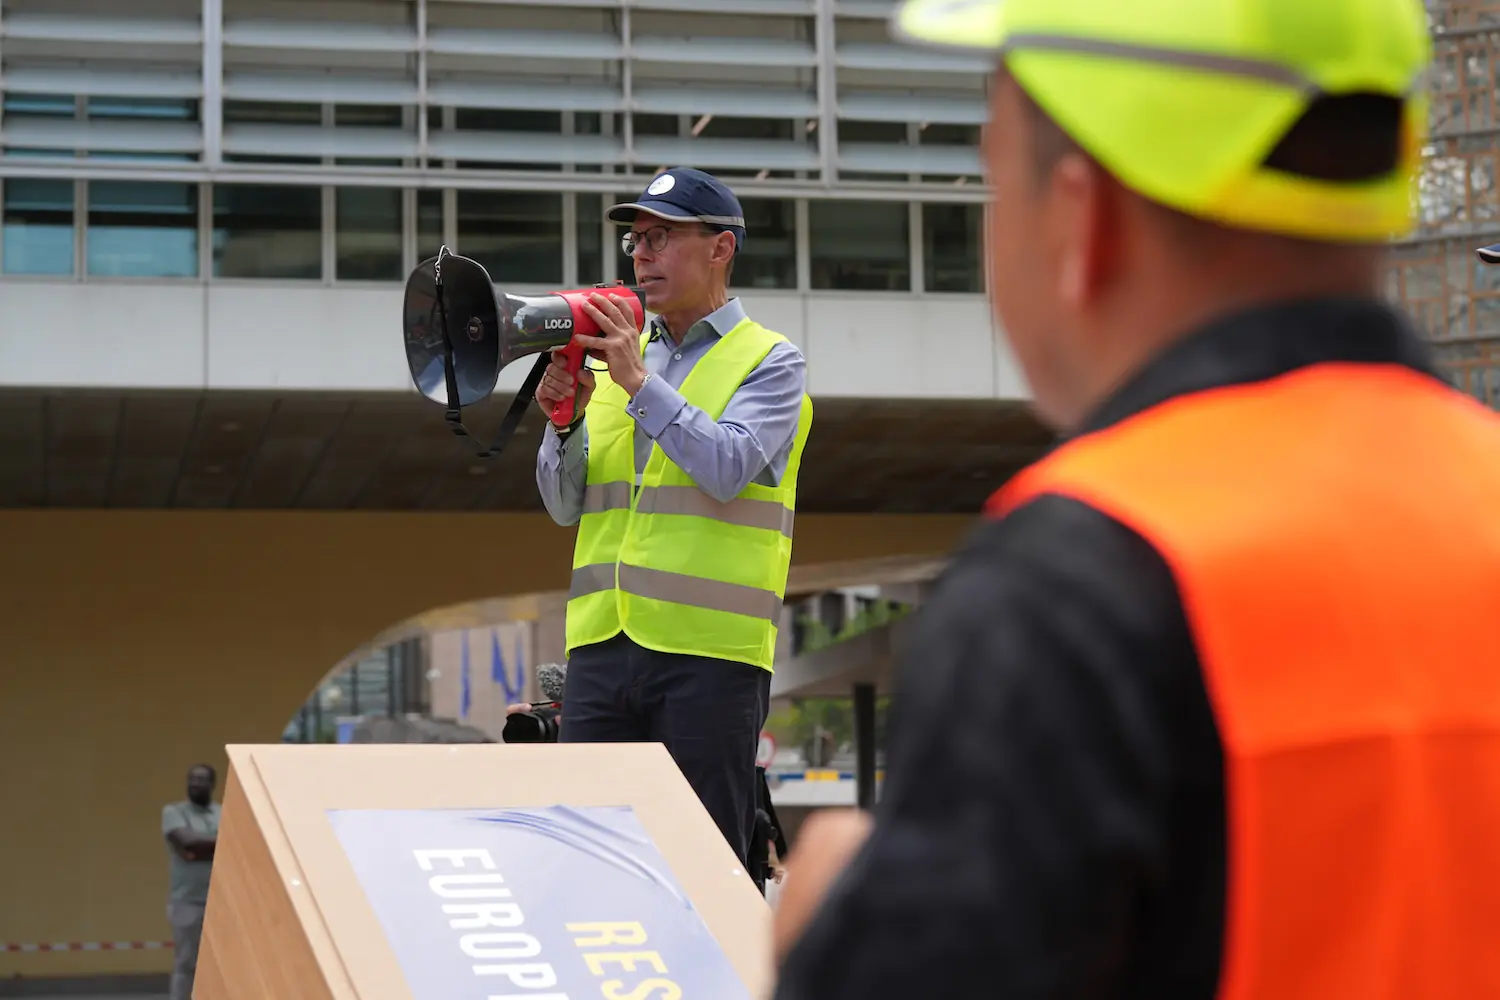
Steel distributors and service centres were represented at a demonstration in Brussels to highlight the issue of increased competition from imports of downstream steel products, this month.
In June, the European Commission adopted a proposal to extend CBAM to around 180 additional steel- and aluminium-intensive downstream products from 2028. However, more than 200 representatives from across the EU’s steel supply chain joined September 7’s European Convoy for Industrial Competitiveness, organised by Eurometal, to highlight the need for more comprehensive action.
The demonstration came just days before a crucial vote on the future scope of CBAM. On September 15, the European Parliament subsequently voted in support of a significant broadening of CBAM which could see it cover well over 400 downstream products. The measure will now be subject to negotiations between Parliament and EU member states.
EUROMETAL says that current EU trade and climate policies protect domestic steelmakers from overseas competition while leaving other businesses in the steel supply chain exposed to imports of downstream products. Such products are not currently subject to CBAM or the Steel Regulation’s tariff-rate quotas (TRQs).
Current trade defences “undermine” downstream operators
EUROMETAL argues that stringent trade defences on steel imports therefore “shift rather than eliminate import pressure”, undermining the competitiveness of Europe’s downstream steel supply chain. They will also result in carbon leakage as third countries’ steel and manufacturing processes, which may be more emissions intensive than those in EU countries, are used to create products that are imported into the EU, EUROMETAL says.
MEPS respondents increasingly highlight the influx of subtly modified steel products, which bypass the EU’s trade defences. This increased low-cost competition for European manufacturers, service centres and rerollers comes as EU steel prices continue to rise after new TRQs significantly reduced their access to imports, raising their input costs.
The MEPS Europe Average hot rolled coil price has risen by over 16% between January and September as buyers increasingly source material from domestic steelmakers. However, this month’s research indicated that high inventories and low demand will mitigate the scale of further increases during the coming months.
Large distributors and service centres are better placed to navigate the EU’s stringent legislation covering steel imports than their small, independent counterparts. An ability to fund port warehousing facilities leaves these businesses well placed to clear imported material through customs at the start of each quarterly quota period. Significant stock funding also allows large operators to maintain their inventories ahead of any anticipated increase in steel prices.
This month, MEPS respondents said that some European distributors are selling material at prices “significantly below” those now being asked by mills. Many are attempting to convert stock into cash before the end of the year.
Further measures required to protect wider sector
The proposed changes to the EU CBAM should strengthen Europe’s downstream steel industry, just as the Steel Regulation and CBAM have improved the outlook for domestic steelmakers. Voicing his support for the wider application of CBAM, the director general of the European steel association (Eurofer), Axel Eggert, said: “Extending CBAM to more steel-intensive products would help ensure that steel produced in Europe and steel contained in imported products compete under comparable carbon conditions.”
However, following this month’s vote in the European Parliament, EUROMETAL is already broadening the scope of its appeal for greater import protection. Association president Alexander M. Julius is calling for a new mechanism to support downstream steel processors and end-users competing in export markets where rivals are not exposed to carbon costs equivalent to those levied in the EU. He said that there remained “no solution for EU exporters carrying carbon costs when competing globally”.
European steel buyers say that import legislation has shifted the balance of power towards domestic steelmakers. Increasing calls for reform suggest new measures are now required to preserve the downstream sector that forms a vital part of their customer base.


Sülzle supplies stainless rebar for Helgoland port
Sülzle Stahlpartner has started the supply of approximately 2,500 tonnes of stainless rebar for the West Pier of Helgoland port in the North Sea.
The West Pier protects the port in the island’s south and, with it, the lifeline of this rocky island in the German Bight, Sülzle explains to Kallanish. To ensure that the 563-metre-long protective structure can continue to withstand the enormous forces of the North Sea in the future, it will undergo extensive repairs and technical modernisation until 2028.
A key component of the project is the highly corrosion-resistant Top12 stainless steel reinforcement from Steeltec AG, Sülzle notes. The steel used is grade 1.4003: stainless, with a chromium content of over 12%, and developed for components exposed to high chloride loads. In the highly stressed splash and tidal zones, it offers significantly greater resistance than conventional reinforcing steel.
The steel will be delivered from Sülzle’s shop for stainless steels in Bad Säckingen in southern Germany. Sülzle says it plans to also establish production of stainless steel reinforcement at its site in Seelze, Lower Saxony.
Author: Christian Koehl


German rebar mills strive for modest increase
Following a period of mixed signals during summer, with deals of base rebar prices below €400/tonne ($461), and then trying to return to that threshold, German mills are now ambitious to take one step further.
“You will not get €400 any more now,” several buyers said unanimously at the beginning of the week. Meanwhile, “at least two mills only today announced that they want €420 now,” one buyer told Kallanish on Wednesday confirming expectations expressed by others earlier.
The increase appears modest in comparison with Italian domestic base price offers of €440/t, and meanwhile way above that, too. One German purchasing manager dismisses those figures completely. “I have not heard €440, let alone more, neither from Germany nor from Italy.” He tells of a deal with an Italian mill only last week over a three-digit tonnage at below €400/t still, “but we were probably the last to enjoy that,” he says.
The mills have good reasons to ask for higher prices. “From north to south, all of them argue with energy costs,” which keep climbing because of the conflict on the Persian Gulf, the manager points out.
Another manager at a bending firm says he does not believe in a pronounced increase so soon. “I was expecting jobs from the construction industry to come back now that the summer break is over. They did, but to a lesser extent than I had wished,” he says. He also points at continued cannibalism among benders, with many of them making offers at dumping prices to secure orders.
Another source tells of a project in Hanover over a volume of 10,000 tonnes, which was won at a bid of €680/t. All the while mills would charge €685/t delivered, provided they can exert the base price of €420, plus the average size extra of €265.
Author: Christian Koehl

European stainless flats market subdued amid high inventories
The European stainless flat products market remains subdued, with demand flat at very low levels following a sluggish summer across the region. Prices have slipped because of the standstill, sources tell Kallanish.
Market participants do not expect prices or demand to improve until buyers reduce their elevated inventories, a process that could take a few months. One large Southern European processor expects stability until the end of the year, as producers’ costs remain too high to allow price reductions. Weak demand is limiting price increases. A separate source expects prices and demand to improve from January 2027, as European inventories are depleted and imports are constrained by EU quotas and CBAM.
Another source notes that in the first half of the year buyers purchased around 30% more material than usual, encouraged by a generally optimistic outlook as prices were rising along with new trade measures. That extra stock is now being used very slowly. Demand from both end-users and service centres remains weak and is expected to stay that way in the coming months.
There are variations, with some European markets holding better prices than others despite generally subdued volumes everywhere. In France, sheet prices stand at around €2,850/tonne ($3,289/t) delivered, some €100/t above Germany and Italy where prices remain at €2,750/t or below.
End users remain cautious, pushing for lower prices given weak market conditions. While some sellers are holding firm and losing orders, others are cutting prices to retain business. One source expects weakness to persist, with long-term contract buyers increasingly negotiating lower prices.
As Europe is overstocked, several sources say they are not buying coils and may resist without buying for some time. “What I see is against logic,” a northern European coil buyer tells Kallanish. “Prices were supposed to increase. With the quota system and CBAM, mills should be able to raise prices, but downstream demand is too weak, and the recovery anticipated for September is not happening.”
European cold rolled coil prices have eased to €2,580-2,600/t delivered, while Italian prices have fallen from €2,580/t in early July to €2,530-2,560/t. Polished edge Italian HRCs stand at €2,350/t and €2,400/t delivered in the rest of Europe. Mills in Europe are quoting October and November lead-times. The level of €2,650/t quoted for November delivery is not yet achieved.
Meanwhile, stainless steel producer Aperam is extending its product range in Europe, with its 304L and 316L grades now available in thicknesses up to 15mm in 1,500mm width, in both coils and sheets.
Aperam says in a note it is the only European producer offering this combination, expanding options for demand applications while maintaining the quality and consistency of continuously rolled stainless steel.
Europe needs US value chain approach, melt-and-pour: EUROMETAL Warsaw
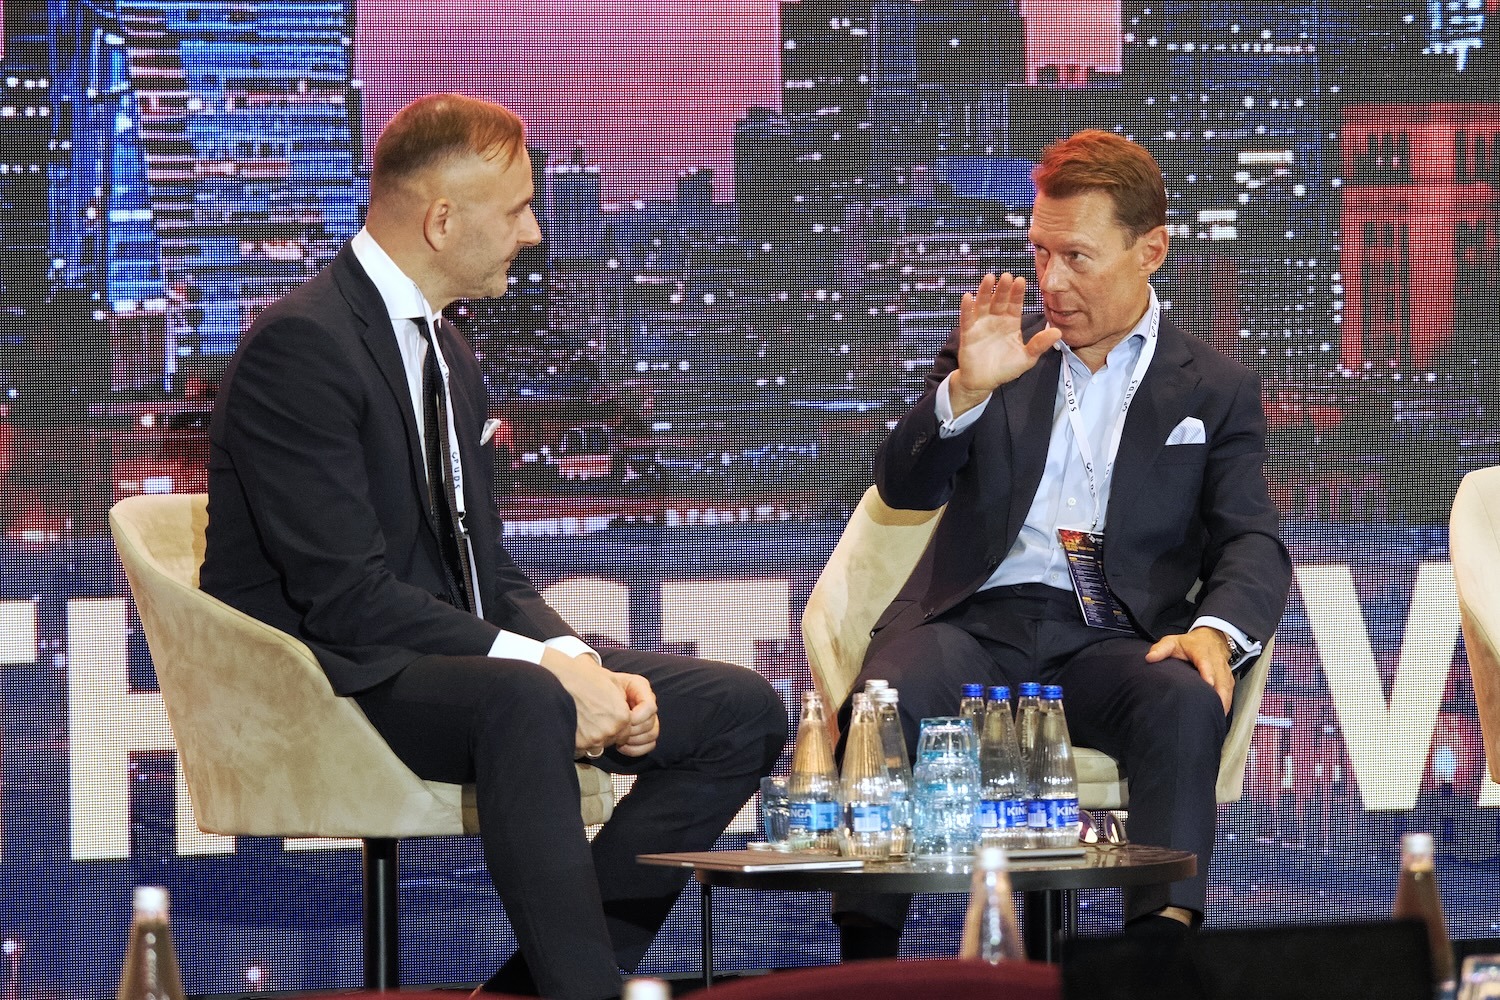
Europe will need to go in the direction of the United States to protect its entire steel value chain if it wants to keep manufacturing, jobs and wealth within Europe, while authorities should commit to implementing melt and pour, said panellists at the EUROMETAL Regional Meeting Central Europe in Warsaw on Wednesday.
Much of the discussion centred around the need to extend CBAM and tariff-rate quotas to downstream, steel-containing manufactured goods, a message Eurometal drove home a week earlier during its rally in Brussels.
“If we want to have a fair Europe, that means we will end up similar to the United States … We will need to focus on Europe as a sales market but it also means we will need to close our doors completely. Not only … on the raw material side when we talk about steel, but also on the product side. At least we are saving the manufacturing jobs here in Europe. That means we can still live with the value chain in Europe,” EUROMETAL president Alexander Julius said at the event attended by Kallanish.
Steelmakers are more aware than ever before about the need to secure the whole value chain in Europe, added Eurofer deputy director general, international affairs Karl Tachelet. Integrated steel production in Europe is no longer sustainable. But the continent has a big manufacturing industry and market, plentiful scrap supply and high-tech steel production capability that it should utilise, he added.
Trade barriers support supply but “what about the demand? What about our customers? What about steel use?” he asked. The European Commission should be applauded for recognising this and introducing a provision to expand the scope of measures, he added.
Julius added that in recent discussions, an EU mill official revealed that 80% of the firm’s steel is being sold in a range of 500km. “If the demand is fading away, that means if it’s being replaced by incoming [imported] products, then there is no need to keep up these steelmaking capacities [in Europe],” Julius pointed out.
European export competitiveness is yet to be addressed by any measure, however. Based on the EU’s cost-competitiveness, if it wants to continue exporting steel, this will likely be limited to niche products like tin mill products and electrical steel that the US does not make sufficient quantities of thus far.
However, these products are “not representing the mass steel sector. So, honestly speaking, countries like China have covered the world already with exports. So … it’s more than naive to think that we can really be competitive in those markets,” Julius warned.
As for melt and pour, although “it makes sense” to prevent circumvention, there is no firm commitment yet from European authorities to introduce the clause. Tachelet noted. Their attitude is “we are open for bringing in melt and pour as a principle of quota allocation, but not yet. Let’s see what the monitoring tells us,” he added. The European Commission has to be convinced to “take the second step”.
Sławomir Czajka, EY, partner remarked of the CBAM regulation: “We’re kind of building the plane while we fly it”. Nobody except “the large multinationals that have … big teams of lawyers” probing suppliers will be able to use actual emissions data for their CBAM calculations. “All the mid-cap companies are not ready to use the … actual emissions data to calculate CBAM. We will use the default values, which we know are … higher.” He added CBAM is “one of the most complex ones [systems] we have in the EU, and it’s not getting stricter. I’m afraid.”
Author: Adam Smith
Liberty Tubular Products restarts welded pipe mill, secures two months of orders
On September 14, Romanian pipe producer Liberty Tubular Products Galati restarted production at its welded pipe mill after several months of very limited activity.
The facility has an annual production capacity of around 50,000 mt and produces welded pipes using heavy plate as feedstock. According to the company, the current order book is sufficient to support around two months of production. Operations may still see some short interruptions during this period, as part of the required heavy plate will be delivered in batches.
The mill had previously restarted on February 16 to process orders totaling around 1,400 mt, with expectations at the time that additional bookings would follow. However, activity remained limited thereafter as order volumes proved insufficient, while the company continued to face financial and liquidity difficulties. Liberty Tubular Products remains under preventive restructuring proceedings, while outstanding salaries at the unit are currently being paid through Romania’s Salary Claims Guarantee Fund.
Liberty Tubular Products operates on the same industrial platform as Liberty Galati and has traditionally sourced the heavy plate used in its pipe production from the steelworks, keeping the two operations closely linked. Meanwhile, preparations for further tolling activity are continuing despite logistical challenges and high energy costs. A first train is being loaded in Constanta with customer-owned slabs for transfer to Galati, while technical and commercial discussions are also underway for additional tolling volumes. With pipe production now restarted and further tolling volumes under discussion, the company is seeking to maintain a more continuous level of activity in the coming months.
Author: SteelOrbis Editorial Team


ArcelorMittal Belgium receives world’s first LNG-powered bulk carrier in Ghent
ArcelorMittal’s Belgian subsidiary ArcelorMittal Belgium has received the Oceana Frontier, described as the world’s first LNG-powered bulk carrier, at its quay in Ghent, marking the first arrival of an LNG-powered bulk carrier for both the steelmaker and North Sea Port. The vessel, carrying iron ore from Canada, arrived in Ghent on September 15.
The Oceana Frontier is one of five vessels in the global fleet transporting raw materials for ArcelorMittal that are currently capable of using LNG as fuel. Following the unloading of its iron ore cargo in Ghent, the vessel will return to Canada to load another shipment for ArcelorMittal Belgium.
LNG use reduces carbon emissions by about 23 percent
According to North Sea Port, using LNG instead of conventional marine fuels can reduce the vessel’s carbon emissions by approximately 23 percent, while also significantly lowering sulphur oxide and nitrogen oxide emissions. On a voyage of around 2,700 nautical miles, the use of LNG is estimated to reduce carbon emissions by approximately 500 mt per trip.
ArcelorMittal considers LNG a transitional solution as it works to reduce emissions associated with the maritime transportation of raw materials. The company is also assessing how newer and more energy-efficient vessels could play a larger role in its raw material logistics in the future.
“With the Oceana Frontier, we are taking a concrete step towards making the transport of our raw materials more sustainable,” Frederik Van De Velde, CEO of ArcelorMittal Belgium, stated, adding that the operation will allow the company to gain experience with a new generation of bulk carriers as part of its efforts to progressively decarbonize its value chain.
Ghent arrival to provide operational experience for other ArcelorMittal sites
The arrival of the Oceana Frontier will also allow ArcelorMittal Belgium to gain operational experience in receiving and unloading LNG-powered bulk carriers, with the knowledge potentially applicable at other ArcelorMittal sites.
North Sea Port has meanwhile been preparing its infrastructure for alternative marine fuels. An independent risk assessment found that LNG, hydrogen, methanol and ammonia can be safely bunkered throughout its port area, including Ghent, Terneuzen and Vlissingen. The port is continuing to develop pilot projects and infrastructure to support the use of these fuels.
Author: SteelOrbis Editorial Team

European manufacturers unable to absorb coil hikes: Assofermet
The risk of a progressive and irreversible weakening of European manufacturing is more tangible than ever. Coil service centres are unable to pass on announced coil price increases without further eroding their competitiveness, Italian trade association Assofermet warns in its recent market note obtained by Kallanish.
European steelmakers have embarked on a path of coil price increases, driven by elevated energy costs and supported by trade barriers to curb steel imports, despite the current complex market landscape. This is being met with serious concern by steel distributors and, above all, by downstream manufacturing.
“The gradual resumption of activity after the summer break is now complete, in an international context largely unchanged from the end of July. Steel demand continues to be impacted by geopolitical tensions, which, beyond supporting a climate of deep uncertainty, are keeping energy costs at extremely high levels,” the association states.
Assofermet has renewed its call to EU institutions to extend any trade and environmental barriers to downstream products and semi-finished goods across the supply chain. This, it argues, is necessary to ensure effective protection of the entire European manufacturing system, not just primary steel production.
Regarding the flat and long steel distribution sector, the summer months of July and August ended with an overall positive result compared to July-August 2025, despite a decline in volumes. Revenue growth was supported by the sudden increase in prices following the start of the Iran-US conflict. Revenues were also boosted by the entry into force of the new EU quota regime on 1 July, while volumes were impacted by summer seasonality and persistent weakness in downstream demand.
“The comparison with the same period in 2025 is nonetheless less negative than previous months’ outlook, pointing to a search for a new equilibrium, albeit still fragile,” the note states. July demand remained weak and distribution cautious, while prices recovered part of their earlier losses. August prices held broadly stable, as European producers, backed by well-filled order books and stronger import barriers, laid the ground for fresh price increases on the return from the summer break.
Long products remain the weakest segment in terms of volumes, impacted by stagnation in construction. The rising prices, however, are softening the contraction in terms of value.
Hot-rolled flat products recorded an increase in both volume and value compared to July-August 2025, with average prices improving, Assofermet concludes.
Author: Natalia Capra

CBAM pricing impact delayed, Europe must adapt: EUROMETAL Warsaw
The impact of the Carbon Border Adjustment Mechanism (CBAM) is yet to be fully reflected in EU steel prices, while distributors’ survival depends on the mechanism being extended downstream. Distributors need to adapt to changing customer needs and Europe, in general, to the changing global landscape if its industry is to survive.
So concluded panellists at the EUROMETAL Regional Meeting Central Europe in Warsaw this week, attended by Kallanish.
Energy and labour costs are more dominant factors in EU pricing than CBAM. However, this is mainly because the market is still working through large inventories accumulated during the front-loading of imports before CBAM and the tariff-rate quota system were implemented. “Now it’s just a matter of [inventories] being digested by the market, and this will come,” said Konsorcjum Stali long products purchasing head Marcin Matysiak.
CBAM did boost EU steel prices by some 5% in the first quarter, but keeping steel-containing manufacturing within Europe is the more pressing issue, argued Carboferr chief executive Roland Fazekas. A decade ago his company invested downstream into machining and engineering capability to produce parts for sectors such as automotive. “We are fighting with the tier ones and the OEMs at the same time. Plus, we are having the mills on the other side,” he noted.
The firm was once contracted to provide parts for BMW production in Hungary. “It was an issue with the counterparty, what we outsource to China, what we keep in our own production. The effective [EU] import duty on a Chinese precision tool is 1.5%, roughly. If we just look at quarto plates directly imported from China, it is 70% import duty. I think the Chinese are laughing all the way down on us, that how come we are so stupid?”
“We are at the first line between the upstream and our customers. Customers create demand,” said Wojciech Gruszka, CEO east ArcelorMittal Distribution Solutions. “If we allow to push this production of metals, processing of metal outside of Europe, we will die … We know that they [customers] are starting switching to [importing] the semi product. They are cutting costs.” CBAM is therefore “a good direction but this is not enough”, he noted.
There may be some resistance from authorities to implement downstream goods tariffs, however, due to fears over retaliation against EU manufacturing exports, Fazekas added.
In any case, trade barriers should be limited in duration and have clear targets, noted Ferona ceo Jan Moravec.
European policy needs to facilitate industrial survival amid the changing global landscape. Its mills are suffering losses while distributors are operating at close to zero profit margin, Moravec continued. ESG reporting requirements mean companies “have to have departments … maybe scientific teams for analysing all the rules and the standards,” he noted. Green Deal targets should be realistic, while market protection should move faster, as it does in the US, rather than authorities overanalysing, he added.
Investments to adapt are also crucial. “2-3 years ago, we sold … more or less about 200 items, and the average [sale] was two tonnes. Now we are selling almost 1,000, average 100 kilo. It means that it’s a complete change,” said Stalprofil board member Zenon Jedrocha. “We have to invest plenty of money for the two-high storage system, and it’s a fully automatic system that allows us to sell such more items.” He added that “plenty of distributors” have invested at high interest rates in Poland but “we are waiting since years for a better time”.
Konsorcjum Stali recently completed its new service centre investment to respond to customers’ changing logistics and quality needs, while Ferona is investing into digitalising its processes to respond to changing consumer behaviour.
Demand for premium-fetching green steel has so far meanwhile been tempered, partly by the squeezed profit environment. “Every single change on our side, regarding prices, even during the contract time, one quarter, two quarters, for them [our customers] is a problem that they cannot accept,” Gruszka noted. “They cannot take the burden of the increasing of the raw material from our side. They are not working on three-digit margins, right?”
Without government incentives for green steel use, “our customers do not care at the moment [about green steel],” said Moravec. Moreover, the definition of “green” steel first needs to be agreed before a market can be created.
In terms of future steel demand, Central and Eastern Europe should be a beneficiary of manufacturing relocation from western Europe, said Fazekas. Consumption is likely to remain flat for the next 2-3 years, Moravec noted. Distributors will look to grow their business in tandem with returning EU steel capacities, even if demand remains flat, Gruszka noted. Jedrocha highlighted EU-funded projects should spur demand in Poland, while Matysiak concluded Konsorcjum Stali is also prepared for expected improved demand.

