


Upward pressure mounts on European longs prices, but demand fails to take off
According to market participants, the upward pressure in the European long steel market is becoming increasingly tangible. However, market fundamentals are not strong enough to suggest a long-term trend, as the price increases appear to be mostly cost-driven.
“The market in Germany is picking up and prices will certainly increase,” one market participant stated. “However, competition from traders in the local market is strong, as inventories were still full of material purchased at lower prices after the summer period,” another commented.
As for Poland, a wide gap has been reported between domestic rebar prices. Sources have reported prices from different mills ranging from a low of around €600/mt delivered to a high of around €655/mt delivered. On the one hand, cost pressure would push prices upward, and mills are reported to be seeking to raise both rebar and wire rod prices by around €20/mt. At the same time, however, demand remains weak and market uncertainty is preventing mills from taking a clear position.
Although September has historically been a month when attempts are made to raise prices following the end of the summer low season, this year energy, gas, transport and logistics costs are weighing more heavily on the market. “Visibility is very, very limited,” a source commented, “also because, at the end of the day, demand always determines the trend. Once the outlook for October becomes clearer, we will have a better idea of how the year will end.”
In the import segment, Turkey has increased prices by around €20/mt week on week for both rebar and wire rod, bringing them to €585-590/mt CFR and €590-600/mt CFR, respectively, though no sales have been reported. As for exports from Egypt, prices have been reported at around €560/mt CFR for rebar and €580/mt CFR for wire rod, up by €15-20/mt compared to the last reported levels on September 4.
€1 = $1.15
Author: SteelOrbis Editorial Team


Moderate HRC imports continue in EU despite emerging CBAM payment concerns
European customers continue to show moderate interest in HRC imports from several destinations, aiming to secure their requirements for the coming period. Some volumes, according to sources, have been freshly booked from Turkey and India.
Overall, while CBAM-related payments are expected to start in 2027, the default values will be taken into consideration for 50 percent of CBAM certificates until there are verified values available in the market. “The European Commission issued a document stating that, until you have actual emission values certified, you must apply with the country’s default values. That means that many players wanted to apply with reduced (estimated) values, but now they will have to pay fully, and then after verification you´ll be refunded the difference,” a source commented to SteelOrbis. Others believe that there will be no refund per se, but the government will return the difference via certain tax or energy-related incentives or will consider them in the calculations for the following periods. “There is a lot of confusion because in some cases people were expecting to pay €50-60/mt CBAM for slabs, but now they will have to pay triple that,” a trader mentioned. “That means huge money frozen and I’m not sure some small traders can deal with that because they have to make upfront payment of millions of euros,” another source opined.
Imports have continued while the market is trying to evaluate the current situation amid reports that there is a certain lobby trying to ease the ongoing situation regarding CBAM payments in the EU. According to sources, some medium lots have been booked from Turkey at €565-575/mt CFR without duty, which is €10-15/mt higher than the previous deals. Moreover, several new deals have been reported from India at $700-710/mt CFR (for the fourth quarter), up from the earlier $680-690/mt CFR, while others have confirmed sales at up to $720/mt CFR for small lots. Egypt is also expected to sell some volumes, with the latest offers heard at $725/mt CFR, while buyers’ price ideas are around $700-710/mt CFR.
In the domestic HRC market, mills’ highest targets are yet to be accepted, with buyers mainly being cautious and buying just to meet their minimal needs. In Italy, price levels are at €740-750/mt delivered, with some deals €10/mt lower also taking place, but overall supply is not plentiful with only some October volumes available. In Spain and the northern EU countries, workable prices have remained at €735-745/mt ex-works, in line with the levels of earlier this week. In the meantime, mills’ highest targets have remained at €770-790/mt ex-works depending on the region. In central Europe, reasonable price levels are at €760-775/mt delivered and effective, while some separate suppliers, according to sources, might be willing to deal at €740/mt CPT base.
Author: SteelOrbis Editorial Team
Waterford offers former Duferco steel plant for sale
Waterford Capital Partners has acquired the former Duferco Danish Steel plant in Frederiksvaerk, Denmark, and is offering the entire facility for sale and relocation.
The package comprises a 300,000 tonnes/year merchant bar hot rolling mill built by Moeller & Neumann, and two cold drawing lines for bright steel, Kallanish hears from Waterford. Included in the sale are 14 overhead travelling cranes, a service centre, laboratory, maintenance workshop, approximately 1,000 spheroidal graphite cast iron rolls and the associated spare parts inventory.
The range of products includes hot rolled merchant bar flats of 25-160mm, rounds of 16-70mm, squares of 16-50mm, angles 30-80mm, and more. In cold drawn bright steel, the two lines produces flats from 20 x 4mm-150 x 30mm, rounds and squares of 20-50mm, with hexagon achievable.
The guidance price given by Waterford is € 12.5 million ($14.3m) for the complete plant, ex-works Frederiksvaerk.
The plant was in production until closure and is offered as a working line. According to Waterford, it has been modernised continuously by Danieli. A dismantling and relocation tender is being run in parallel, Waterford notes. A buyer takes over the plant ex-works and will need to work with one of the recommended dismantling parties, it says.
Author: Christian Koehl


Stargate expansion targets affordable green hydrogen for steelmaking
Estonian electrolyser manufacturer Stargate Hydrogen has secured a €20.6 million ($23.7m) EU grant to scale up its operations to supply “affordable” green hydrogen to steel, chemicals, and other energy-intensive sectors, Kallanish learns from a company statement.
The EU Innovation Fund grant will help expand the firm’s manufacturing facility in Tallinn, Estonia, to produce 250 MW/year of electrodes, 150 MW/y of stacks, and 66 MW/y of electrolyser systems.
“With the help of the Innovation Fund, we truly step up our game,” comments Marko Virkebau, chief executive of Stargate Hydrogen. “After the factory expansion is finalised, Stargate will become one of the largest electrolyser manufacturers in Europe.”
The factory opened last year with an initial manufacturing capacity of 140 MW/y of electrolysers. At the time, Stargate said it was “well-positioned” to bring down the cost of green hydrogen and help decarbonise sectors such as steel, fertilisers, and chemicals.
The company says its alkaline electrolyser technology uses a ceramic-based catalyst material, instead of precious metals, which reduces the reliance on imported critical raw materials, while enabling highly efficient hydrogen production. According to its website, this leads to “significantly lower hydrogen production costs and makes the electrolysers affordable for end-users.”
High cost of green hydrogen is one of the key barriers to its wider adoption, despite its decarbonisation potential. A recent report by trade body Hydrogen Council found that the steel sector accounts for just 5% of binding clean hydrogen offtake agreements globally, with the industry favouring decarbonisation routes other than hydrogen in the near term.
Yet, Stargate says its project is expected to avoid 3 million tonnes of CO2 equivalent emissions in the first ten years of operation by “supporting broader deployment of affordable green hydrogen across hard-to-abate industries”.
Author: Reethu Ravi

Marcegaglia rethinks tube pricing, segment faces deep transformation
Italian pipe and steelmaker Marcegaglia has published a new price list that changes the pricing structure for welded tubes, in line with recent changes in the coil market, Kallanish notes.
Sources in the sector believe the company is modelling the new structure on the coil pricing mechanism. Under the new list, welded tubes prices will consist of a base price plus specification-based extras, mirroring the pricing formula used for coil. On tubes, the base price will remain fixed, while the extra will vary by specification. Discounts will be applied to the base, whereas under the previous system discounts were applied to the total value.
The new price list has been published, with full implementation expected by late September or early October as customers adapt to the revised pricing model, Kallanish understands. The update will include price increases, although Marcegaglia has yet to set final levels as it assesses the recent rise in coil prices.
Updated transport costs have also been integrated into the new list. Freight rates have surged in recent months, and finding trucks and drivers is increasingly difficult. Logistics are becoming a serious financial burden on the price of steel per tonne with bottlenecks causing delays across the value chain.
According to one source, the rising cost of fuel and freight will push the tube business towards greater regionalisation. Globalisation is fading due to protectionism, and regional presence will become increasingly important to improve customer service and contain costs.
Several other European pipe makers are also considering price increases in response to higher coil and transport costs. On the coil side, rising costs pushed ArcelorMittal to increase prices across Europe in September. The revised base price for hot rolled coil in Southern Europe is at €790/tonne delivered, and €770/t for Northern Europe, levels seen as workable for October and November. With HRC purchase prices now well above €700/t base ex-works, tube makers are expected to raise prices despite uncertain downstream demand.
Another source expects a broader transformation of the welded tube sector as European protectionism reshapes supply chains. With competitively priced imported HRC no longer readily available, producers will need to focus more on value-added services, quality and processing capabilities than on raw-material sourcing.
Tube demand in central and southern Europe remains subdued, with no clear recovery in consumption. However, market sentiment is improving as imports decline. Buyers built inventories ahead of the July quota changes but are expected to return to the domestic market in October and November as stocks are depleted.
Author: Natalia Capra
Italian rebar prices edge higher amid rising costs, tentative demand recovery
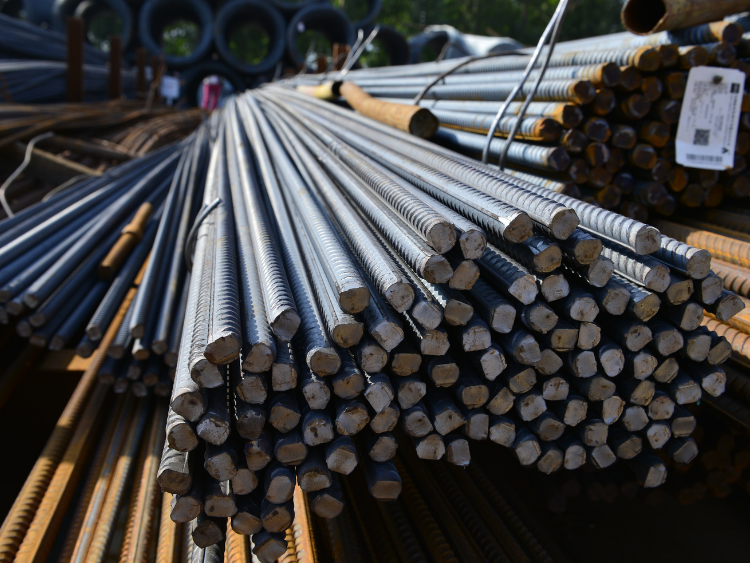
Italian domestic rebar prices narrowed upward in the week to Wednesday September 17 amid rising production costs and a modest improvement in speculative demand, as producers continued to push for higher prices.
“Energy and fuel prices continue to move higher, particularly considering the current global macroeconomic and geopolitical situation, and this is adding further pressure on production and logistics costs,” a buyer source told Fastmarkets.
Market participants noted a slight improvement in speculative demand across Europe compared with the end of August and the first days of September, although not enough to support significant price increases sought by producers.
“The Italian rebar market, however, remains relatively slow, with demand still not strong enough to fully support a significant price increase,” the source told Fastmarkets.
In northern Italy, tradable levels were heard at €700-730 ($808-842) per tonne ex-works, while transactions in southern Italy were heard at €730-750 per tonne ex-works. Higher offers of €760-770 per tonne ex-works were also heard, although those levels were not supported by transactional activity.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, exw Italy, was €700-750 per tonne on September 17, narrowed upward from €690-750 per tonne the previous week.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, delivered Spain, remained unchanged at €750 per tonne.
Meanwhile, German domestic rebar prices edged higher, with tradable levels heard at €715-720 per tonne delivered.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, delivered Northern Europe, was €715-730 per tonne on September 17, narrowed upward from €710-730 per tonne the previous week.
Wire rod prices remained largely stable during the assessment week, with weak demand and low liquidity continuing to constrain market activity.
Fastmarkets’ weekly price assessment for steel wire rod (mesh quality), domestic, delivered Southern Europe, was unchanged at €660-680 per tonne on September 17.
Fastmarkets’ weekly price assessment for steel wire rod (mesh quality), domestic, delivered Northern Europe, was unchanged at €690-715 per tonne on the same day.
European sections and beams
European domestic section prices remained stable month on month.
Fastmarkets’ monthly assessment for steel sections (medium), domestic, delivered Southern Europe, was €800-870 per tonne, unchanged month on month.
Domestic beam prices increased month on month, with tradable levels heard at €810-860 per tonne delivered across Europe.
Fastmarkets’ monthly assessment for steel beams, domestic, delivered Northern Europe, was €810-860 per tonne, up from €780-820 per tonne the previous month.

UK government to seek nationalisation of SSUK
The UK government is developing a plan to nationalise Speciality Steel UK (SSUK), Business Secretary Jonathan Reynolds announced in the UK’s House of Commons on 14 September, seeking to revive production at the troubled steelworks.
Sources close to the matter consider the restart of SSUK’s electric arc furnace (EAF) capacities to be all but certain for December, reporting that the Official Receiver has been releasing funds in line with what would be required for a restart before end-of-year.
A winding-up order was granted for SSUK in August 2025, putting the steelmaker’s administration process under the Official Receiver.
Since then, the government has been keen to find a private sector solution for SSUK – with private investment featuring heavily across March’s UK steel strategy – as was the case with British Steel, following government seizure from the Chinese owner Jingye, in April last year.
Against those intentions, the government failed to find a suitable buyer for British Steel, instead taking the steelmaker into state ownership in July.
According to sources, finding commercial synergies – potentially via consolidation of the UK’s primary and downstream steelmaking assets – has long been in the government’s sights, particularly in relation to British Steel and SSUK while under state administration.
Greenfield steelmaking company Blastr, which is developing new green direct-reduced ironmaking (DRI) capacities in Finland, was granted preferred bidder status for SSUK earlier this year, prior to the lapse of the exclusivity period in June.
Dow Jones Energy understood that Blastr was still actively involved in the bidding for SSUK despite the end of preferred bidder status, and so – it seems – did Blastr, expressing disappointment at the news of nationalisation:
“We are disappointed by the Government’s decision today concerning Speciality Steel UK, and we were not informed in advance,” Blastr replied to Dow Jones Energy on 14 September. “Over the course of several months, we have advanced our plans for a private sector solution to acquire SSUK – and were today on site in South Yorkshire with investors and strategic partners. We have a fully-funded proposal – at no cost to the British taxpayer – that is ready to complete within 12 weeks.”
Sources attribute the long negotiation period between the government and SSUK to frictions on project financing, suggesting that the government was dissatisfied with how far Blastr’s proposal would expose UK taxpayers. Sources also expect that the government’s nationalisation of British Steel could have altered its willingness to take ownership of SSUK, potentially able to find greater sector synergies for the steelmaking assets under mutual ownership.
Author: Benjamin Steven


EU steel industry calls for further work as lawmakers widen CBAM scope
The European steel industry has warned that Europe still falls short of a level playing field after the European Parliament backed an extension of the Carbon Border Adjustment Mechanism to downstream steel and aluminum products on Sept. 15.
The Parliament approved the expansion of CBAM’s scope to finished goods such as fasteners, wire, springs and household articles by a 464-50 vote, with 159 abstentions. The move aims to address carbon leakage in downstream manufacturing, where imported steel‑containing goods increasingly enter the EU market without facing the carbon costs borne by European producers.
“Today’s vote is a step in the right direction, but it does not yet deliver a level playing field for European industry. The proposed scope remains incomplete, implementation is too slow, and there is still no solution for EU exporters carrying carbon costs when competing globally,” said Alexander M. Julius, president of Eurometal. “Moreover, CBAM alone cannot offset the broader cost disadvantage faced by European manufacturers due to higher steel prices and regulatory burdens. Europe must protect the entire value chain if it wants to prevent carbon leakage and deindustrialization,” he added.
The federation has called for CBAM coverage to be extended to all relevant steel and aluminum-intensive products with an acceleration in implementation timelines, as well as greater support to EU exporters and making sure the EU protects industrial activity rather than encouraging its relocation in its climate policies.
German steel industry association Wirtschaftsvereinigung Stahl also called for increased protection of EU exporters, who still bear European carbon costs, and said it was now crucial for the Parliament to quickly reach an agreement with the European Commission and Council to implement the regulation.
Ahead of the vote, the European Steel Association (Eurofer) supported the motion but called for stronger rules to prevent circumvention, noting the scale of investment required for steelmakers to decarbonize. “Europe’s steelmakers are investing billions to produce cleaner steel, but they cannot make that transition without a level playing field. MEPs have the opportunity to strengthen CBAM so that investing in low‑carbon steel production in Europe makes economic sense,” said Axel Eggert, director general of Eurofer. “Europe should be creating the conditions to produce more clean steel here, not incentives to move production elsewhere.”
European steel prices have risen in 2026 following CBAM’s implementation and the revised steel safeguard mechanism, with domestic mills holding firmer positions in negotiations as importers seek to mitigate their regulatory risks.
Platts, part of S&P Global Energy, assessed domestic hot-rolled coil in Northern Europe at €730/mt ex-works Ruhr, and in Southern Europe at €725/mt ex-works Italy, both up €110/mt since the start of the year.
Platts assessed imported HRC in Northern Europe at €585/mt CIF Antwerp, and in Southern Europe at €580/mt CIF S. Europe, both up €85/mt across the same period.
Author: Annalisa Villa
Italy’s ADI starts hot-end shutdown; future still hangs on High Court ruling
Acciaierie d’Italia (ADI) has begun a gradual shutdown of hot-end operations at its Taranto steelworks — the only integrated blast-furnace plant in Italy — after a Milan court rejected the company’s appeal against an earlier closure order, raising fresh uncertainty over the future of steel production at the site and its impact on European flat steel supply.
The shutdown, which started Sept. 16, follows a Milan Court of Appeal ruling Sept. 11 that dismissed an ADI challenge to a previous order mandating the closure of the hot-end section of the former Ilva plant. The court has ordered the suspension of the entire hot end of the company, which mainly comprises the coking plant units and blast furnace No. 2, with an annual capacity of about 2 million metric tons — the only one among the five blast furnaces operating — by Oct. 28.
An ADI press officer declined to comment when reached by S&P Global Energy.
Legal proceedings
The special commissioners managing ADI under extraordinary administration have lodged another appeal, and the Court of Cassation — Italy’s highest court — is scheduled to hold an Oct. 20 hearing to consider the challenge to the Milan Court of Appeal’s shutdown order, unions said to S&P Global Energy after a Sept. 16 meeting with the government.
Sources close to ADI also confirmed the development, but it remains unclear when the Court of Cassation will issue its ruling following the Oct. 20 hearing.
The Taranto plant has a nominal crude steel capacity of about 8 million metric tons/year, produced from iron ore and coal through blast furnaces — making it the largest steelworks in Italy and one of the most significant integrated facilities in southern Europe. Its prolonged legal and operational difficulties have weighed on domestic Italian steel output.
ADI has argued that closing the hot-end facilities risks jeopardizing all steel production at the site, as the company’s northern sites reroll the coils produced in Taranto. The Italian government, which is seeking a buyer for the company now under extraordinary administration, faces mounting pressure to secure an alternative industrial solution ahead of a national election next year.
The former Ilva assets were placed under extraordinary administration Feb. 20, 2024, when special commissioners were appointed at the request of the Italian state investment agency, Invitalia, despite opposition from steelmaker ArcelorMittal, which was then the largest shareholder in ADI. The Taranto plant has long been at the center of disputes over public health, with environmental and safety concerns cited in successive court orders targeting its hot-end operations.
Platts, part of S&P Global Energy, assessed domestic hot-rolled coil in Southern Europe at €725/mt ex-works Italy Sept. 15, stable day over day, and imported HRC in Southern Europe at €580/mt CIF Southern Europe, also stable day over day.
Author: Annalisa Villa

EU regulators open review as Arvedi moves to acquire steel distributor AMCLN
Italy’s largest flat-steel producer Acciaieria Arvedi S.p.A. has moved to take sole control of automotive-focused steel distributor ArcelorMittal CLN Distribuzione Italia S.r.l. after Rome’s golden power veto forced ArcelorMittal to abandon its own acquisition bid, according to a Sept. 17 merger notification published by the European Commission.
The EC in its Official Journal confirmed that Acciaieria Arvedi S.p.A. has notified its intention to acquire sole control of ArcelorMittal CLN Distribuzione Italia S.r.l., known as AMCLN, through a purchase of shares.
The Commission received the notification on Sept. 10, under case reference M.12598.
ArcelorMittal had originally planned to acquire the remaining 51% of AMCLN it did not already own, but withdrew after Rome invoked its golden power framework to impose conditions on the deal.
Steel consolidation
AMCLN distributes flat carbon steel products — including hot-rolled and cold-rolled coil — through service centers across Italy, supplying the automotive, construction, and white goods sectors. Full ownership would give Arvedi an integrated position from mill to end-customer.
The Commission designated the case a candidate for its simplified procedure, signaling it does not expect the deal to raise significant competition concerns. Third parties have until Sept. 27 to submit observations.
Acciaieria Arvedi did not reply when contacted by Platts, part of S&P Global Energy, for a comment.
Platts assessed domestic hot-rolled coil in Southern Europe at €725/mt ex-works Italy Sept. 16, stable day over day.
Author: Annalisa Villa