


German steel sales fall 18% on month in August as weak demand persists
German steel distribution sales totaled 727,529 metric tons in August, down 17.8% from July and 2.7% below the same period a year ago, while stocks held steady at just under 1.92 million mt, broadly stable month on month, according to data sent to Platts by the German steel distribution association BDS on Sept. 24.
The monthly sales decline was broad-based across all product categories.
Flat products, which account for the largest share of distribution volumes, fell by 18.4% month on month to 414,052 mt in August and down by 5.6% year over year. Sales of long products declined to 250,106 mt in August from 293,272 mt in July, a fall of 14.7% month on month.
On a year-on-year basis, however, longs bucked the trend, rising 5.7% from 236,714 mt in August 2025, the only product category to record a year-on-year sales increase.
The others category — which includes tubes and other specialty steel products — was the weakest performer, slipping to 63,371 mt in August, down by 24.9% month on month and down by 12.3% year on year.
The data pointed to continued weak demand in one of Europe’s largest steel-consuming markets, with overall stable inventories alongside falling sales.
Total stocks at German distributors stood at 1,921,832 mt at the end of August, up just 0.1% month on month and up by 3.1% year on year.
Flat product inventories declined by 0.8% month over month to 1,251,363 mt, though they rose by 5.7% year on year. Longs stocks increased to 632,508 mt from 620,140 mt in July, a rise of 2% month on month, though they were 2.4% below 647,894 mt a year earlier. Stocks in the others category were broadly stable at 37,961 mt, virtually unchanged from July, but up by 15.5% year on year
| Sales and stocks of German steel distribution | ||||
| Sales (mt) | Longs | Flats | Others | Total |
| Aug-25 | 236,714 | 438,550 | 72,223 | 747,487 |
| Jul-26 | 293,272 | 507,498 | 84,419 | 885,189 |
| Aug-26 | 250,106 | 414,052 | 63,371 | 727,529 |
| Stocks (mt) | Longs | Flats | Other | Total |
| Aug-25 | 647,894 | 1,184,330 | 32,869 | 1,865,093 |
| Jul-26 | 620,140 | 1,261,213 | 37,939 | 1,919,292 |
| Aug-26 | 632,508 | 1,251,363 | 37,961 | 1,921,832 |
| Source: BDS | ||||
Author: Annalisa Villa

ArcelorMittal says Ukraine steel plant cannot restart safely
ArcelorMittal is unable to safely restart operations at ArcelorMittal Kryvyi Rih following multiple recent missile strikes, the steel company said in a Sept. 25 statement.
Over the past five weeks, ArcelorMittal Kryvyi Rih has been hit by four missile strikes, resulting in fatalities, injuries and extensive damage to production facilities.
In total, the attacks claimed five lives and injured 17 employees, ArcelorMittal said, adding that it had advised the Ukrainian government that the company was unable to restart operations at its Ukrainian subsidiary in a safe and sustainable manner.
“Since the war started, our people in Ukraine have worked tirelessly to keep the mines and plant operating. They have been the embodiment of bravery in circumstances most of us cannot begin to imagine,” ArcelorMittal Kryvyi Rih CEO Mauro Longobardo said in the statement.
The company is discussing the plant’s future with the Ukrainian government and will focus on preserving its infrastructure so that, when peace returns, options for restarting production remain available, Longobardo said.
ArcelorMittal expects to record a non-cash impairment charge of about $1 billion, principally reflecting the impairment of property, plant and equipment at ArcelorMittal Kryvyi Rih.
The statement follows a Russian ballistic missile strike overnight Sept. 21-22 on another steel plant, belonging to Ukrainian steel pipe and railroad products manufacturer Interpipe, which said its industrial facility in Dnipro halted production after key equipment and infrastructure were damaged.
Since mid-August, Russia has used missiles to strike several major Ukrainian steel mills, including Zaporizhstal, Kametstal and the Dnipro Metallurgical Plant, forcing them to suspend operations.
Intensified attacks on Ukrainian steel plants, infrastructure and logistics have already affected Ukraine’s ferrous metals business. In August, the country’s pig iron exports fell to 34 metric tons, down from 51,530 mt in July and 196,890 mt a year-earlier. Shipments of semi-finished carbon steel products declined by more than 70% both month over month and year over year to 26,000 mt.

Romanian longs prices stable amid limited buying and sufficient stocks
Romania’s longs market has continued to move sideways this week, as the overall market outlook still offers limited support for higher prices. Demand remains present but relatively limited, with construction activity not yet strong enough to generate a broader increase in steel consumption, while liquidity constraints are also encouraging buyers to remain cautious as regards purchasing volumes. As a result, most buying continues to be focused on immediate requirements, with little need to build additional stocks at current demand levels. Inventories across the domestic market are generally considered sufficient, which has further reduced pressure on buyers to secure extra tonnages. Under these conditions, domestic prices have remained broadly stable, while appetite for imported material has also continued to be limited this week.
Romanian retail rebar prices are still generally heard at around €610-615/mt ex-warehouse. However, some sellers are attempting to lift their quotations by around €5-10/mt, targeting levels closer to €615-625/mt ex-warehouse. So far, these higher levels have met with limited acceptance from buyers, preventing any broader upward movement in the market. Beltrame, Romania’s sole rebar producer, is meanwhile maintaining its official quotations at around €600-610/mt ex-works, with discounts of approximately €10/mt still understood to be available depending on tonnage and payment terms.
The wire rod market has followed a similar direction, with prevailing retail prices remaining at around €635-640/mt ex-warehouse. Sellers are also trying to add approximately €5-10/mt, bringing targeted levels to around €640-650/mt ex-warehouse.
Import activity has remained slow this week, as current domestic demand and sufficient local inventories have left buyers with limited appetite for additional imports. Bulgarian rebar quotations have moved higher to around €640-660/mt CPT Romania, compared with €630-650/mt CPT last week. No fresh Italian offers have been heard this week, while the latest available indications remain broadly stable at around €590/mt FCA, with freight to Romania estimated at €65-75/mt. Hungarian rebar in coils continues to be quoted at around €640-650/mt delivered, while Moldovan suppliers are also maintaining their previous levels at approximately €610-620/mt delivered for rebar and €645-655/mt delivered for rebar in coils. Turkish rebar export quotations have remained unchanged at $620-635/mt FOB this week. With freight to Romania estimated at around $25-30/mt, the corresponding level remains at approximately €555-570/mt CFR Romania, broadly in line with last week. Egyptian suppliers, meanwhile, have continued to seek higher levels. Rebar quotations have increased to $610-615/mt FOB from $600-610/mt FOB last week, translating into approximately €555-565/mt CFR Romania with freight estimated at $35-40/mt, compared with around €545-560/mt CFR previously. Egyptian wire rod offers have also edged up to $625-635/mt FOB from $620-635/mt FOB last week, corresponding to around €570-580/mt CFR Romania, versus approximately €565-580/mt CFR one week earlier.


Bulgarian longs market stabilizes after recent gains, further price rises prove difficult
The recent upward movement in Bulgaria’s longs market has lost momentum this week, with prices remaining broadly unchanged from last week and the market showing little support for another increase. Billet availability remains tight and demand has shown a slight improvement compared with the particularly weak conditions seen earlier, but neither has been strong enough to trigger a new round of price increases. Overall purchasing activity remains slow, while buyers continue to resist higher quotations and generally limit their orders to current requirements. Some suppliers have nevertheless attempted to test higher levels, but these efforts have so far gained little acceptance, leaving the market largely unchanged from last week.
Domestic rebar prices are heard broadly unchanged at around €630-650/mt CPT, while wire rod quotations remain at approximately €670-680/mt CPT. Rebar levels of around €660/mt CPT are reported to have been tested in some cases, but market participants say such prices are difficult to achieve under current market conditions.
Import activity has remained very limited, with almost no fresh purchases reported as weak buying activity in the domestic market continues to weigh on interest in imported material. Turkish rebar offers are currently heard at around $620-635/mt FOB, corresponding to approximately €570-580/mt CFR Bulgaria with freight estimated at $25/mt, compared with around €550-565/mt CFR last week. Egyptian rebar is offered at approximately $610-615/mt FOB, equivalent to around €560-570/mt CFR with freight of about $30/mt, versus roughly €540-550/mt CFR previously. Egyptian wire rod offers are, meanwhile, heard at around $625-630/mt FOB, translating to approximately €575-580/mt CFR Bulgaria, compared with around €560-575/mt CFR a week earlier.

OECD: Global steel excess capacity to reach 721 million mt by 2027, threatening decarbonization
Global steel excess capacity is projected to increase from 601 million mt in 2024 to 721 million mt by 2027, undermining producers’ ability to invest in low-emission technologies and raising the risk that subsidized capacity expansion will further delay the industry’s decarbonization, according to the OECD’s report, Navigating the Steel Transition amid Global Excess Capacity.
The organization stated that persistent overcapacity depresses steel prices, squeezes profit margins and increases financing costs, while government support that sustains inefficient producers slows the retirement of emission-intensive facilities.
BF-BOF capacity additions continue to outpace closures
According to the report, approximately 25.8 million mt of blast furnace-basic oxygen furnace (BF-BOF) capacity is expected to be withdrawn during 2025-2027, including 15.6 million mt in China, accounting for around 60 percent of the total. However, these closures will be outweighed by 62.1 million mt of new BF-BOF capacity, primarily in China and India. Only 6.9 million mt, or 27 percent, of the identified BOF closures are associated with corresponding electric arc furnace (EAF) installations at the same locations, suggesting that deteriorating market conditions remain a stronger driver of closures than decarbonization.
Meanwhile, Chinese overseas investment is contributing to the relocation of emission-intensive production, with around 60 million mt of anticipated capacity expansion in ASEAN linked to Chinese investment, potentially prolonging reliance on high-emission steelmaking.
DRI and EAF expansion does not necessarily reflect decarbonization
The OECD identified 30.7 million mt of planned direct reduced iron-electric arc furnace (DRI-EAF) steelmaking capacity additions and 61.7 million mt of scrap-based EAF additions during 2025-2027. Nevertheless, much of this expansion reflects raw material availability, energy advantages and expectations of stronger demand rather than explicit emissions reduction strategies.
Among the DRI projects scheduled to come online by 2027, only around 19 million mt of capacity appears to be driven by low-emission objectives. The report emphasized that DRI production is not inherently low-emission, particularly where coal-based technologies are used, while natural gas-based projects require credible plans for a subsequent transition to hydrogen to support near-zero-emission production.
Low-emission projects face delays as investment conditions weaken
As of the second quarter of 2025, announced low-emission steelmaking projects representing 15.5 million mt of capacity had been suspended or postponed amid excess capacity, high energy costs and regulatory uncertainty. Projects involving conversion from BF-BOF to EAF production recorded the highest suspension rate at 27 percent, followed by hydrogen-based DRI projects at 18 percent and carbon capture, utilization and storage projects at 15 percent.
The OECD noted that weaker profitability restricts internal funding while earnings volatility and higher borrowing costs make external financing more difficult, leaving producers with limited financial capacity for major technological upgrades.
Lower conventional steel prices increase the relative green premium
Falling conventional steel prices also weaken the commercial case for low-emission products by increasing the relative premium buyers would need to pay. Using an estimated production cost difference of approximately $160/mt between conventional BF-BOF steel and green hydrogen-based DRI-EAF steel in Europe, the OECD calculated that declining hot rolled coil prices during 2022-2025 increased the implied relative premium from 17 percent to 25 percent.
Similar calculations showed increases from 16 percent to 22 percent in China and from 15 percent to 22 percent in Japan, illustrating how depressed conventional steel prices can discourage demand for cleaner alternatives even when the absolute production cost gap remains unchanged.
Transition policies must support capacity retirement
The OECD warned that subsidized expansion of lower-emission steelmaking could generate a new wave of excess capacity unless investment incentives are accompanied by effective retirement of existing facilities.
In economies driving oversupply, the organization called for transition measures to be combined with mandatory closures, binding capacity replacement requirements and the removal of market-distorting subsidies. Meanwhile, carbon-related market access requirements can help protect investment in cleaner production, although subsidized low-emission imports could still undermine market-based producers.
The report concluded that addressing excess capacity is essential to restoring investment capacity and strengthening demand for low-emission steel, while decarbonization policies should promote genuine restructuring rather than simply change the technological composition of global oversupply.
European domestic HRC prices see slight increase; producers remain bullish despite limited demand
Steel domestic hot-rolled coil (HRC) prices edged up slightly in Northern Europe and in Italy, despite subdued market activity and buyers resisting higher offers from mills, Fastmarkets heard on Thursday September 24.
Sources in Northern Europe said that mills remain “quite aggressive” with their offers, trying to increase their prices for HRC, although noting that buyers are not easily accepting higher prices.
“Customers are reluctant, and although they need to buy, they are waiting for better deals or a general increase in market prices,” the source said.
Indications of workable levels were reported around €740-750 ($844-855) per tonne ex-works, while offers were heard hovering at €750-760 per tonne ex-works for October and November deliveries.
Higher offers were also reported at €770-780 per tonne ex-works, but market participants did not consider those levels to be achievable in deals yet.
No reports of new trading activity were heard during the day.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €741.67 per tonne on September 24, up by €1.67 per tonne from €740 per tonne on September 23.
The index was up by €3.34 per tonne week on week and by €11.67 per tonne month on month.
Meanwhile, demand in Italy also remained weak for HRC, with no reports of new offers or deals from market sources during the day.
Sources indicated workable levels at around €730-745 per tonne ex-works.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €737.5 per tonne on September 24, up by €2.5 per tonne from €735 per tonne on September 23.
The index was up by €6.25 per tonne week on week and by €18.12 per tonne month on month.

Regulation costs squeeze flat steel traders: Kallanish GFS26
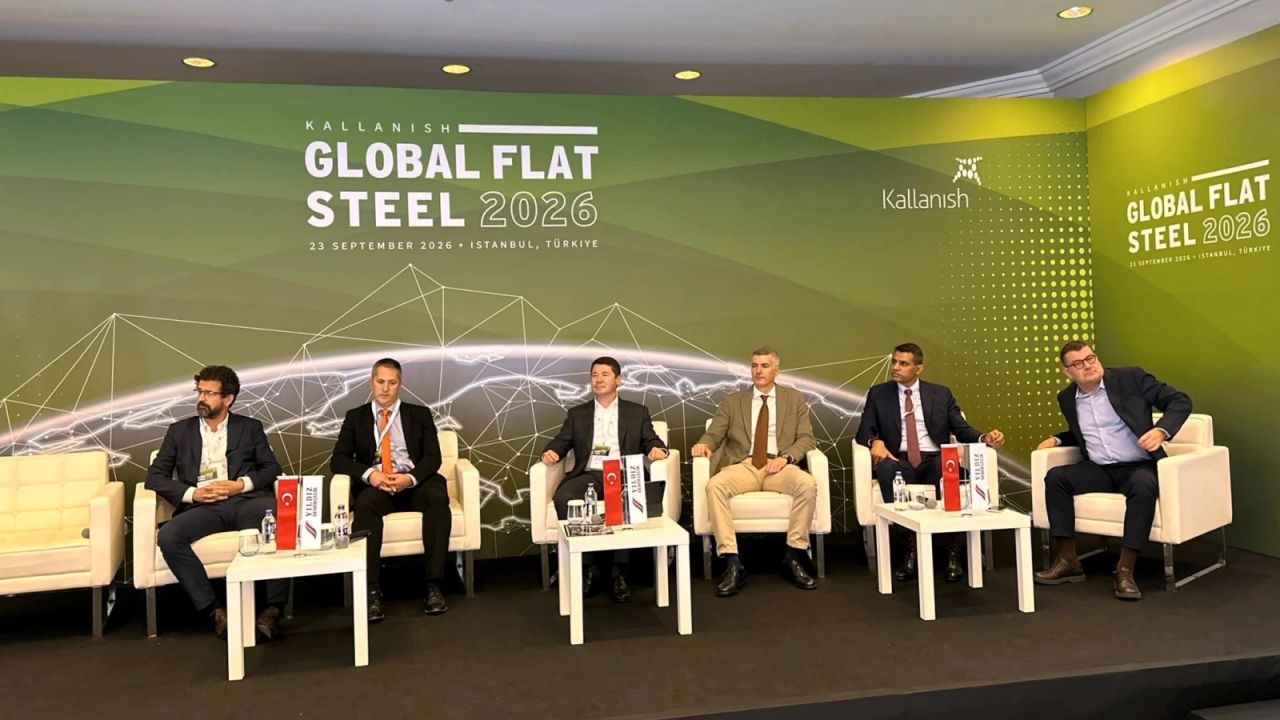
Carbon and quota compliance costs are becoming a permanent part of flat steel pricing and are testing traders, speakers said in the closing session of Kallanish Global Flat Steel 2026 in Istanbul on Wednesday.
Stanislav Zinchenko, chief executive of GMK Center, said CBAM default values and delayed verification would add around €10/tonne ($11.4/t) for Indian material and €20/t for Indonesian product coming into the EU. “We have a new cost factor that will support price – a regulation factor, a carbon factor,” he said.
Zack Newman, commercial director at M7 Metals, said traders must plan for the worst on quotas, CBAM and cash tied up in guarantees. “You have to make your assumptions based on the worst-case scenario,” he noted, adding that some traders would be caught out.
Kutay Ulku, trade manager at Tata International, said it is essential to post extra collateral with EU customs. “I’ll be very happy if the EC [European Commission] would just abolish all the quotas,” he said, and apply a flat 50% duty to every origin.
Ankur Mishra, trading lead for steel at Cargill Metals, said regulatory and financing costs would ultimately be passed to consumers. “At some point, there will be a pushback. There will be demand destruction,” he said.
Gorkem Bolaca, managing director of Galex Steel International, noted that buying decisions had changed. “It’s all about buying the material at a landed, risk-free, regulatory-free price,” he observed.
Guvenc Temizel, executive committee member at Borcelik, said Turkey’s economy was stagnating under high interest rates and inflation, but the steel sector was resilient. “We have had many crises, but we never stop,” he commented.
Asked where they would put $1 billion of investment, the panel was split, each with a different rationale. Mishra chose India. He said that while US prices look attractive, a plant would take three years to build, and India’s per-capita consumption remains well below the global average, giving a 20-year demand runway despite coking coal constraints.
Bolaca chose Africa, citing its young population, the AI-driven data-centre build-out and the need for an investment horizon beyond three years. Temizel would back US grain-oriented electrical steel, as data-centre construction is being slowed by transformer shortages and most transformer steel is imported.
Newman would avoid steelmaking, citing overcapacity, and favour low-carbon DRI and HBI spread across several countries, since cheap gas locations carry higher political risk. Ulku would split funds evenly: European electrical steel and tinplate for data centre and EV demand, and scrap collection in Europe and Africa rather than DRI. Zinchenko would avoid US steel assets over fears they could be lost to political or banking pressure. He said he would put half into North African metallics and half into European re-rolling, where he sees at least €200/t margins for five years.

Overcapacity, protectionism, geopolitics reshape steel: Kallanish GFS26
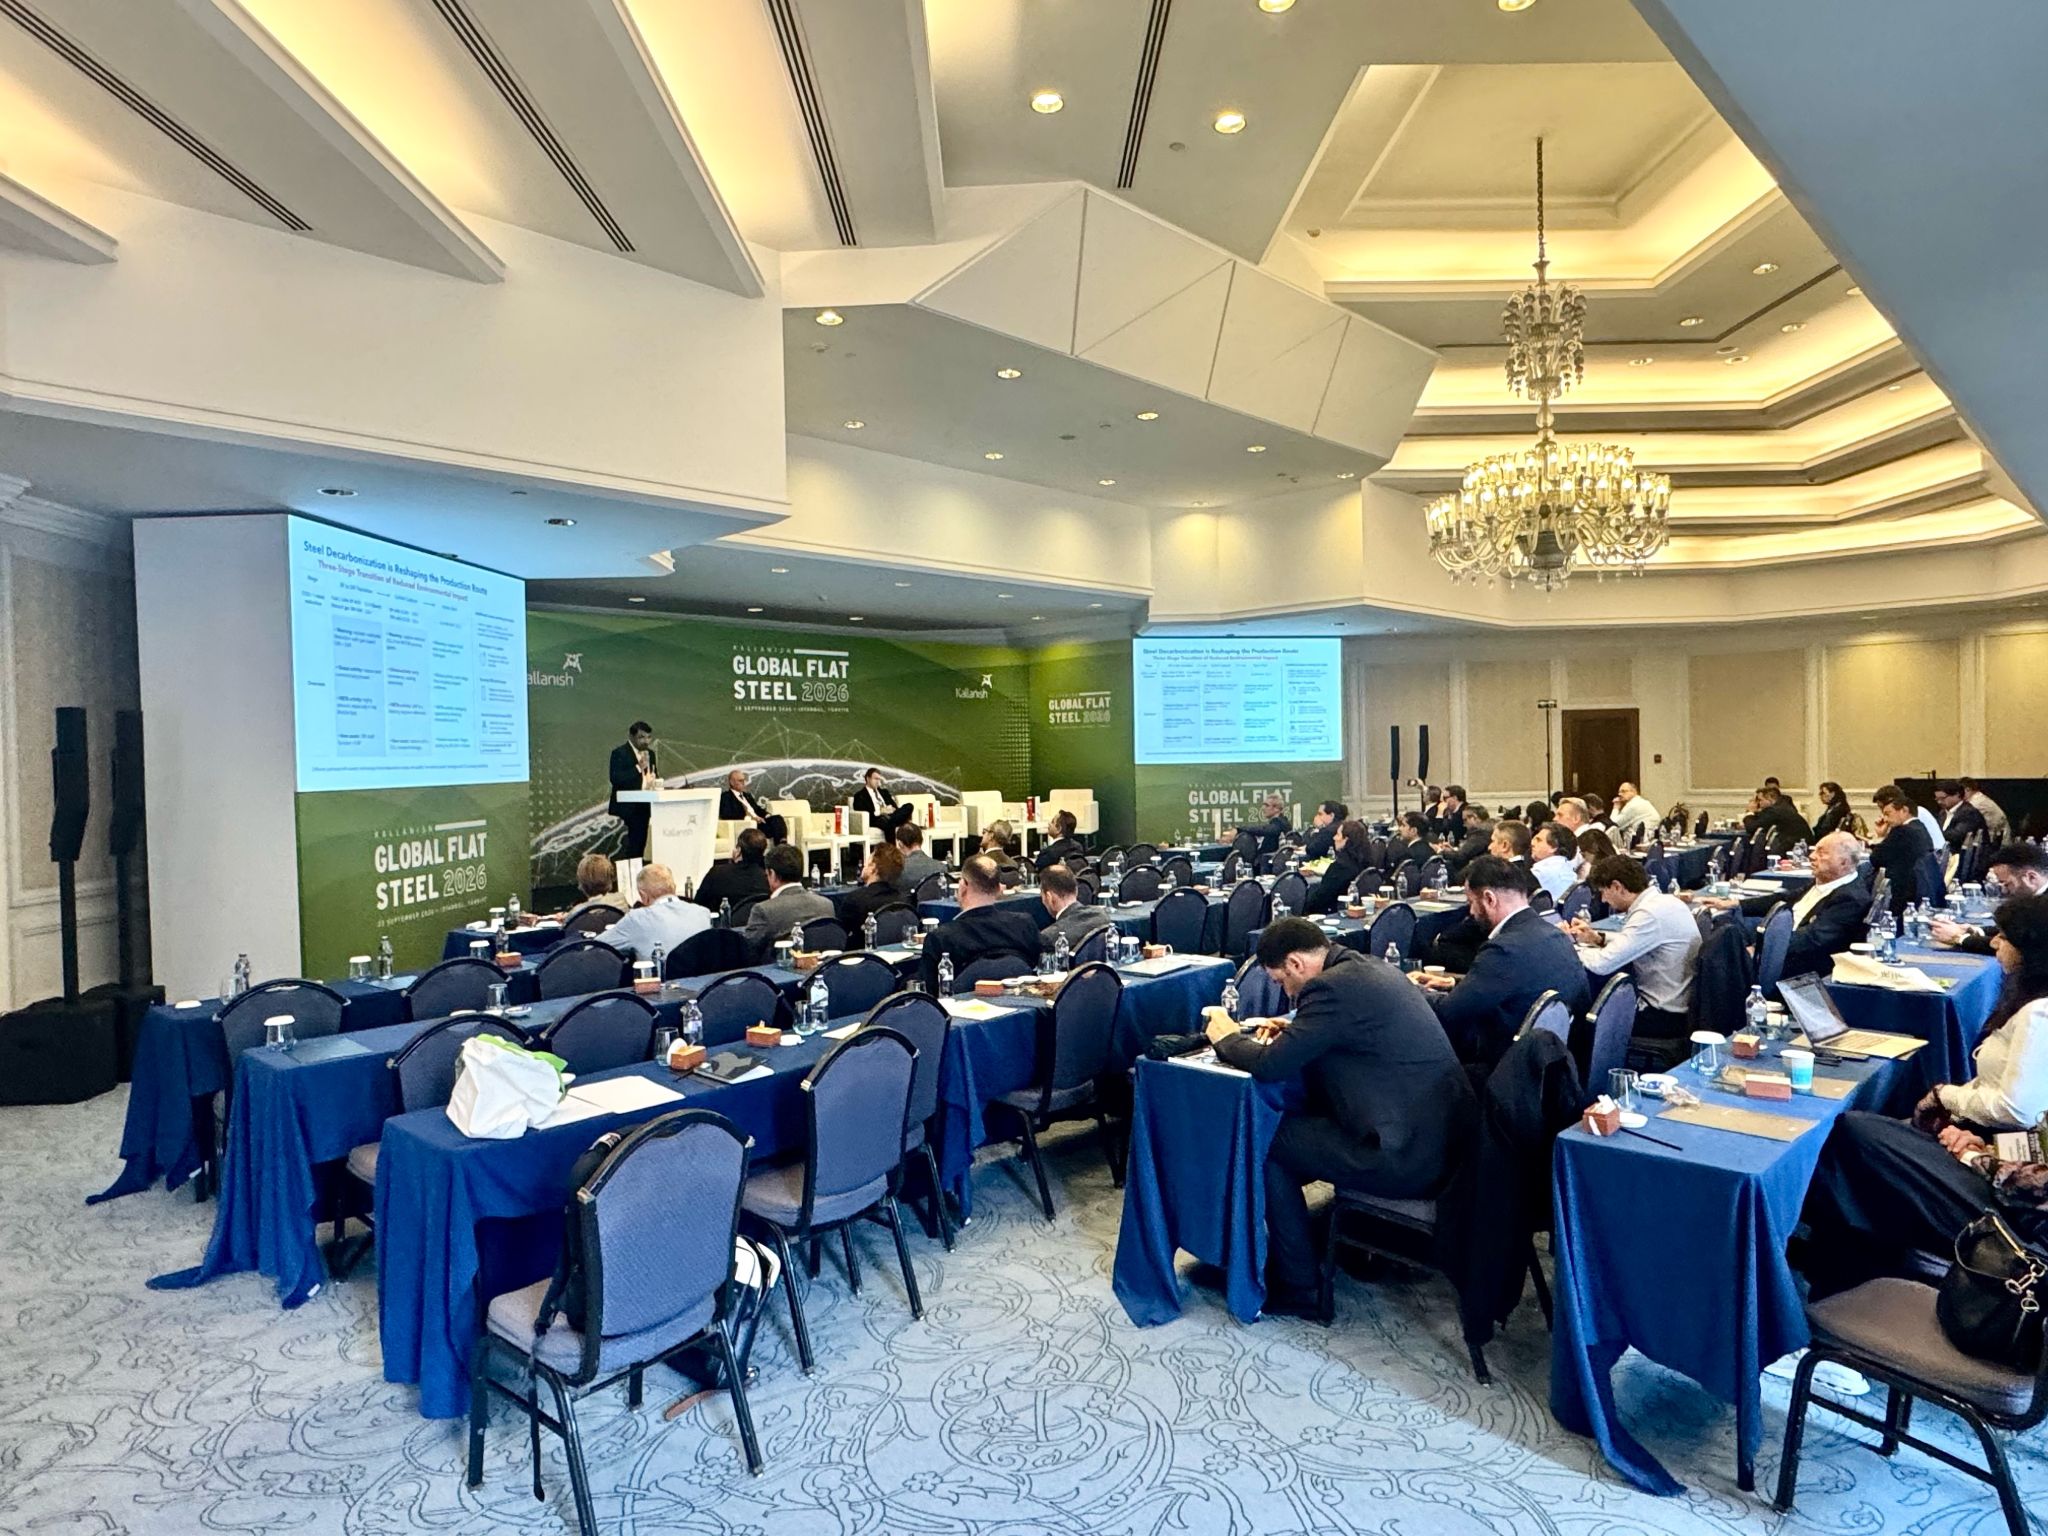
Overcapacity, protectionism and geopolitical disruption are reshaping global steel trade, panellists said during the opening keynote session of Kallanish Global Flat Steel 2026 in Istanbul on Wednesday.
Turkish Flat Steel Import, Export and Industry Association (Yisad) chairman and Colakoglu Metalurji board member Metin Tayfun Iseri said global overcapacity has left producers unable to protect margins. “The ship is sinking, and everybody is trying to protect their own market,” he said, adding that further capacity growth and investment need to stop.
Kallanish managing editor, Asia, and head of data Tomas Gutierrez said China’s steel sector has structurally peaked as Beijing redirects investment towards strategic technology sectors, while steel exports remain high despite thin margins. “If the demand in China is less than the supply, the steel will go somewhere, and that caps prices here and everywhere else,” he said. He put sustainable Chinese exports at around 130 million tonnes this year.
Yildiz Demir Celik general manager Selçuk Yilmaz argued that Turkey’s electric arc furnace-heavy production base should provide a CBAM advantage for supplying into the EU. But Turkish exporters remain exposed to quotas and the incoming “Made in Europe” restrictions.
He also pointed to the toll of regional conflict on trade flows. “Everyone’s talking about overcapacity, but geopolitical conflict matters too. The Israel-Iran war may not hit steel markets directly, but closing shipping routes changes everything – oil prices rise, freight goes higher than before the war. And since 2022 there’s the Russia-Ukraine war, and nobody knows how that resolves,” he said.
MAN Industries president – group procurement and strategy Manish Lunker, who sources pipeline-grade steel for infrastructure projects, said 2026 has been among the toughest years for securing material on time. “Ensuring the material is available at all times is the biggest challenge we as industry are facing today,” he said.
He pointed to Red Sea shipping disruption as a key driver: “The current disruptions in the Red Sea have led to a lot of uncertainty in the shipping industry,” he noted, citing vessel shortages and port congestion. He called for the industry to develop longer-term, 12-24-month pricing mechanisms to support project-based capacity booking, as well as for further investment in special grade steel supply.

HKM permanently shuts down BF A in Duisburg after 53 years
Germany-based steelmaker Salzgitter AG has announced that its subsidiary Hüttenwerke Krupp Mannesmann (HKM) has permanently shut down blast furnace A at its Duisburg plant after more than 53 years of production, as part of its transition toward lower-carbon steelmaking. The final tapping of the furnace took place on September 19.
Blast furnace A was commissioned in 1973 and produced approximately 93 million mt of pig iron over five campaigns during its operating life. A few days before its closure, HKM also shut down coke oven battery No. 2 at its Duisburg plant, as SteelOrbis previously reported.
BF route to be replaced with EAF from 2029
HKM plans to produce lower-carbon steel in Duisburg using a new electric arc furnace (EAF) from 2029. The EAF will have an annual production capacity of up to 2.5 million mt, making it Germany’s largest EAF and the second-largest in the EU.
The project is receiving €200 million in funding from Germany’s federal government and the state of North Rhine-Westphalia under the Federal Funding for Industry and Climate Protection program. Construction of the project started in August this year, while completion is scheduled for 2029.
Gunnar Groebler, Salzgitter CEO, said the closure represents another step toward the group’s goal of completing its transition to nearly carbon-neutral steel production by the mid-2030s. The company plans to replace the conventional blast furnace route in Duisburg with EAF-based production as part of this strategy.
Blast furnace B to maintain production during transition
Until the new EAF is completed, blast furnace B will maintain production at the Duisburg site. The furnace was restarted several weeks ago following a refurbishment lasting several months.
HKM’s two blast furnaces produced approximately four million mt of pig iron in 2025. Due to the refurbishment of blast furnace B and the permanent shutdown of blast furnace A, pig iron production is expected to decline to around three million mt in 2026. From 2027, HKM’s annual production capacity will stand at up to 2.5 million mt, initially using one blast furnace and subsequently the new EAF.

Italy’s ABS strengthens northern European presence with new service center in Sweden
Italian special steel producer ABS – Acciaierie Bertoli Safau, the steelmaking division of Danieli Group – has inaugurated a new service center in Värnamo, Sweden, which will serve as the company’s hub for its Scandinavian operations. According to reports in the local Swedish press, this is ABS’s first service center outside Italy. The opening completes the project launched in 2025 with the development of ABS Steel Nordic and strengthens the group’s presence in the northern European market.
The new ABS Steel Nordic Service Centre covers an area of approximately 25,000 square meters and includes a newly constructed 5,500-square-meter building. The center combines stock availability, processing, cut-to-length services, logistics and metallurgical consulting, enabling ABS to serve large industrial customers, small and medium-sized enterprises and machine shops. The facility was built in approximately ten months and is equipped with automated and robotic systems for material handling and cutting.
The facility has also obtained Miljöbyggnad Silver environmental certification, the second level of Sweden’s leading building sustainability certification system managed by the Sweden Green Building Council (SGBC), confirming performance above the minimum requirements set by Swedish regulations in terms of energy efficiency, indoor environmental quality, and the selection and traceability of materials.
The center will serve key northern European markets
Värnamo was selected for its strategic location in relation to the key markets of Sweden, Norway, Denmark and Finland. The availability of material in stock will enable just-in-time deliveries and shorter response times to customers’ requirements.
The service center will focus on special steels and will stock, among other products, hot rolled products, peeled, cold drawn and ground bars, as well as forged products, with a dimensional range of approximately 20-300 mm. The cutting equipment installed at the center can handle larger-sized materials of up to approximately 560 mm. The product range will include carbon steel, case-hardening steel, quenched and tempered steel, and micro-alloyed steel, while technical and metallurgical support will be provided through the expertise of the ABS Centre Métallurgique (ACM) research center.
Camilla Benedetti, president of ABS Acciaierie, stated that the opening represents a decisive milestone in the company’s international growth, adding, “The Nordic market demands quality, sustainability and service. She emphasized that the new hub is aimed at bringing ABS even closer to its customers by integrating steel supply, logistics, cut-to-length services and technical consulting.