


European domestic HRC prices conditioned by limited downstream restocking; imports rise on latest deals
Steel hot-rolled coil (HRC) prices edged down slightly in the domestic market of Northern Europe under pressure from the downstream market and sufficient inventory. Italian prices remained broadly stable day on day, while imports in the region increased on latest deals, sources told Fastmarkets on Wednesday September 23.
In Northern Europe, participants said that weak downstream demand was limiting price increases in the market, as buyers were not rushing to restock. Meanwhile, mills were firm on their offerings due to the lack of importing competition.
Latest indications of workable levels in the market were reported within the range of €730-760 ($836-871) per tonne ex-works on Wednesday, while offers from mills were heard at €750-760 per tonne ex-works.
Higher offers reached €780-790 per tonne ex-works but they were considered unworkable for the moment, sources told Fastmarkets.
A distributor said that demand was even falling, while mills were trying to increase prices slightly, citing high energy costs in Europe.
Thus, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €740 per tonne on September 23, down by €3.75 per tonne from €743.75 per tonne on September 22.
The index was down by €5 per tonne week on week but up by €17.92 per tonne month on month.
Meanwhile, a supplier source said that steel service centres in Germany and Italy were willing to accept limited stock replacement not higher than €750 per tonne delivered, which they indicated around €730-740 per tonne ex-works.
“There is no appetite to take substantial volumes at these prices – no real stock-outs yet and difficulties to consolidate sheet prices at target levels of €850 [per tonne] CPT and higher,” the same source said.
The supplier added that steel sheet prices were pushed down by some producers in Northern Europe, putting realistic HRC levels in line with the Italian market, where sheets were supported by higher prices.
Despite the weak downstream demand in the market, HRC prices in Italy were holding a firm workable level around €730-740 per tonne ex-works, based on sources’ indications.
A distributor said that competition in the market was strong due to low demand, leading to narrowing margins.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €735 per tonne on September 23, stable day on day.
The index was up by €6.67 per tonne week on week and by €22.50 per tonne month on month.
In Central Europe, HRC mills were heard facing difficulties with production planning due to longer steel slab deliveries, taking around 60-90 days to arrive from overseas destinations. Restricted access to raw materials such as iron ore and coke was also limiting production accordingly, a source familiar with the matter told Fastmarkets.
However, no price increases were initiated this week, and the latest levels were indicated in line with previous deals at €730-740 per tonne ex-works reported on September 16.
Fastmarkets’ weekly price assessment for steel hot-rolled coil domestic, exw Central Europe was €730-740 per tonne on Wednesday, stable week on week.
On the import side, HRC deals into Southern Europe were heard at €555-570 per tonne CFR from Turkey and at $710-720 (€620-629) per tonne CFR from India on Wednesday.
Higher offers from Turkey were reported at €640-660 per tonne CFR but no deals were confirmed at these levels. Meanwhile, Egypt was heard offering material around €628-633 per tonne CFR.
As a result, Fastmarkets’ weekly assessment of steel hot-rolled coil import, cfr main port Southern Europe was at €555-629 per tonne on September 23, up from €550-620 per tonne a week earlier.

Book-and-claim could accelerate green steel transition: RMI
A book and claim (B&C) system for iron and steel could support a faster transition to net zero steelmaking, the Rocky Mountain Institute (RMI) says in a new report seen by Kallanish.
While multiple pathways already exist for decarbonising the sector, their deployment has been “frustratingly slow” due to high up-front costs and long lifetimes of existing assets, the clean energy think tank adds. On the buyers’ side, companies willing to pay a premium for low-emissions steel often find themselves unable to directly procure it.
A B&C model, RMI says, can help address this gap by enabling more market participants to support low-emissions steel supply beyond traditional procurement pathways. Essentially, the mechanism separates a product’s verified environmental attributes from the physical product. Producers can sell environmental attribute certificates (EACs) linked to verified low-emissions steel production, creating an additional revenue stream when physical delivery is not possible. For buyers, purchasing EACs offers a credible, transparent way to support green steel production and claim the associated emission benefits.
Some steelmakers such as Stegra already apply book and claim to the non-prime steel it produces. Last week, Google agreed to purchase EACs for a volume of up to 91,000 tonnes of steel from Stegra’s future steel production in Boden, Sweden. A year ago, the prospective steelmaker signed the first purchasing agreement for EACs with Microsoft.
“There is a clear demand for near-zero-emission steel and a willingness to pay a premium, especially in geographies where there is a cost for carbon,” Stegra was quoted as saying by RMI. “Unlocking the potential for customers more broadly to purchase the green value, through use of environmental attribute certificates, will spur further production for sustainably sourced steel.”
RMI proposes a dedicated B&C framework for iron and steel, featuring verified certification for low-emissions steel, a secure registry to issue, transfer, and retire certificates, and clear guidance for buyers to claim the associated emission benefits. These safeguards, it adds, are essential to prevent double counting, ensure climate integrity and build trust among market participants.
The think tank has developed its own framework for the sector, although it is not yet a formal certification standard or operational registry. Further testing and collaboration across the steel value chain will be required to strengthen certification, verification, tracking and governance the report concludes.
Steel remains ‘people’s business’ despite increasing complexity: conference
Buying steel in the 2020s has become a game of multiple skills and challenges, but ultimately, relationships and communication matter most, said speakers at the MBI Stahltag conference in Frankfurt on Tuesday.
“There was a time when a buyer only needed to buy steel,” Martin Brückner, managing director of conference organiser MBI Infosource, said in his opening speech. “Today, they need to know about emission trading, geopolitics, CBAM, artificial intelligence, and more; and, by the way, eventually they need to ask for the price.”
Provokingly, he said that “in Germany, we have the cleanest steel in the world, but no more customers who can afford it”. Brückner pointed out that “steel procurement will remain a people’s business. It takes trust, and a sense of judgement: Is the mill salesman being truthful about high capacity utilisation and long lead times, or is he only fibbing?”
A similar conclusion was drawn by Hans Boot of consultancy DDVC. “After all, man is an animal of communication,” he said at the event attended by Kallanish. “People want to talk with one another, and not only on [Apple calling application] FaceTime.”
This conclusion complemented several ideas he presented on artificial intelligence, which could help procurement, but is not yet extensively used. “The technology is there, we just need to train for it,” Boot said. The same is true for digital procurement platforms. Boot advocated a “Just do it!” approach. “I see people consider trying it, but after half a year they still talk about it, rather than giving it a try,” he observed.
He also addressed the widening range of tasks being taken on by purchasing departments. “In the future, the buyer will be more of an optimiser of supply chains, and will be called supply chain manager,” Boot said.
Moreover, he recommended that industry recruiters of Generation Z should consider people’s soft skills – “another term nobody used 20 years ago”.
Frankstahl subsidiary Steelcoin lists steel-backed token on Bullish
Steelcoin X (SCX), a token redeemable for physical hot-rolled coil, has been listed on digital asset platform Bullish Exchange, Steelcoin announced on September 22.
Steelcoin is a wholly-owned subsidiary of Austrian steel distributor Frankstahl.
SCX can now be traded against the euro around the clock through Bullish Exchange’s central order book and automated market maker. Bullish is providing the trading venue and liquidity.
Each SCX token corresponds to one tonne of HRC and is issued on the Ethereum blockchain. Holders can redeem the tokens for physical steel under the conditions set out in the project’s white paper. The minimum redemption quantity is one complete coil, typically weighing 20-30 tonnes and therefore requiring 20-30 SCX.
Unlike steel-related futures and exchange-traded products that are settled in cash, SCX is intended to be settled through the delivery of steel.
The token is issued by Vienna-based SC Steelcoin GmbH. The company describes SCX as a utility token compliant with the EU Markets in Crypto-Assets Regulation (MiCAR) and says its crypto-asset white paper has been notified to Austria’s Financial Market Authority.
Bullish Exchange president Chris Tyrer said the listing reflected growing institutional interest in tokenised commodities. Marcel Javor, founder of Steelcoin and owner of Frankstahl, said the initiative was intended to bring steel trading onto an institutional digital order book.
Bullish Europe is regulated under MiCAR as a crypto-asset service provider. The exchange is part of Bullish, which is listed on the New York Stock Exchange and also owns digital asset information provider CoinDesk.

Italy’s steel export value up 2.8% in H1 amid diverging flats and longs trends
In the first half of 2026, Italy exported a total of approximately 4.66 million mt of flat and long steel products, up 0.5 percent compared to the 4.64 million mt recorded in the same period of 2025. In terms of value, these exports amounted to approximately €3.84 billion in the January-June 2026 period, up 2.8 percent compared to €3.73 billion in the same period of 2025.
More specifically, exports of flat steel products amounted to 2.03 million mt in this period, down 11.9 percent compared to 2.30 million mt last year. The value of flat steel product exports decreased by 5.5 percent to approximately €1.88 billion, compared to €1.99 billion in the same period of 2025. Meanwhile, the average value per metric ton increased by 7.2 percent, rising from approximately €867/mt to €929/mt.
The long steel segment followed the opposite trend, with exports increasing by 12.7 percent to 2.63 million mt in the first six months of the year. The value of these exports reached approximately €1.95 billion, up 12.5 percent from €1.74 billion in 2025. Meanwhile, the average value remained largely stable, edging down from approximately €743/mt in the first half of 2025 to €742/mt in the period under review.
SteelOrbis’ analysis is based on Istat data on Italian exports to the global market and cover HS categories 7208-7212 for flat steel products and HS categories 7213-7217 for long steel products.


Germany’s crude steel output up 6.3% in Jan-Aug 2026
In August this year, Germany’s crude steel output increased by 1.7 percent year on year to 2.59 million mt, according to data released by the German Steel Federation (WV Stahl). In the January-August period of 2026, crude steel production in Germany rose by 6.3 percent year on year to 23.90 million mt.
In the given month, Germany’s pig iron output amounted to 1.65 million mt, down by 5.5 percent year on year, while production in the January-August period increased by 5.7 percent to 14.94 million mt.
Meanwhile, the country’s hot rolled steel output moved up by 4.1 percent year on year to 2.36 million mt in August and by 4.2 percent to 21 million mt in the first eight months of the year.
EU scrap restrictions to non-OECD nations could wreak havoc on ferrous trade flows: sources
Restrictions on the export of scrap metal from the European Union to certain countries outside of the Organisation for Economic Co-operation and Development (OECD) from next year are expected to realign supply chains for secondary ferrous materials, sources told Fastmarkets on Tuesday September 22.
A draft published by the European Commission on Friday September 18 showed a proposed list of countries outside of the OECD which would be allowed to continue importing EU-origin scrap metal classified as “waste” from May 21, 2027 under the revamped Waste Shipment Regulation (WSR).
Twenty-four nations outside of the OECD submitted applications to continue receiving non-hazardous EU waste in compliance with the revamped WSR back in February 2025. The revamped WSR came into force within the EU in May 2026, with the export restrictions to non-OECD nations delayed for a further year.
Although applications from some European countries outside of the EU were approved for imports of metal scrap including Ukraine, Moldova and North Macedonia, the vast majority of applicant countries were rejected, the list shows.
Applicants had to demonstrate that imported waste would be managed in an “environmentally sound manner,” the Commission stated without elaborating. The proposed list is open for feedback until October 16, with adoption still planned for the fourth quarter of 2026.
Market panic
The draft has raised panic in key ferrous scrap importer markets over recent days, sources said, because if there were no major amendments, it could lead to European steel scrap being locked out of several major buyer markets like India, Pakistan and Egypt.
One way for recyclers to avoid their scrap metal being restricted by the WSR rules is to ensure that their material is not classified as a waste product by obtaining end of waste (EOW) status from an EU-accredited auditor if their material is of high purity, Fastmarkets understands.
But it is not known how many EU recyclers have obtained EOW status and for how much of their scrap metal output.
“Export restrictions on recycled metals are the wrong way to go. Introducing them via waste law does not make it any better,” Murat Bayram, president of the Germany-based Circular Metal Association (CMA), said on Tuesday. “Those who close international markets do not create additional demand or more competitiveness in Europe.”
“If European metal producers do not buy the available quantities, sales markets will disappear, material values will come under pressure and surpluses will grow,” he added.
Sebastian Will, deputy chairman of German metals recycling trade association BVSE, called for “open markets and real demand instead of new export barriers.”
Realignment in trade
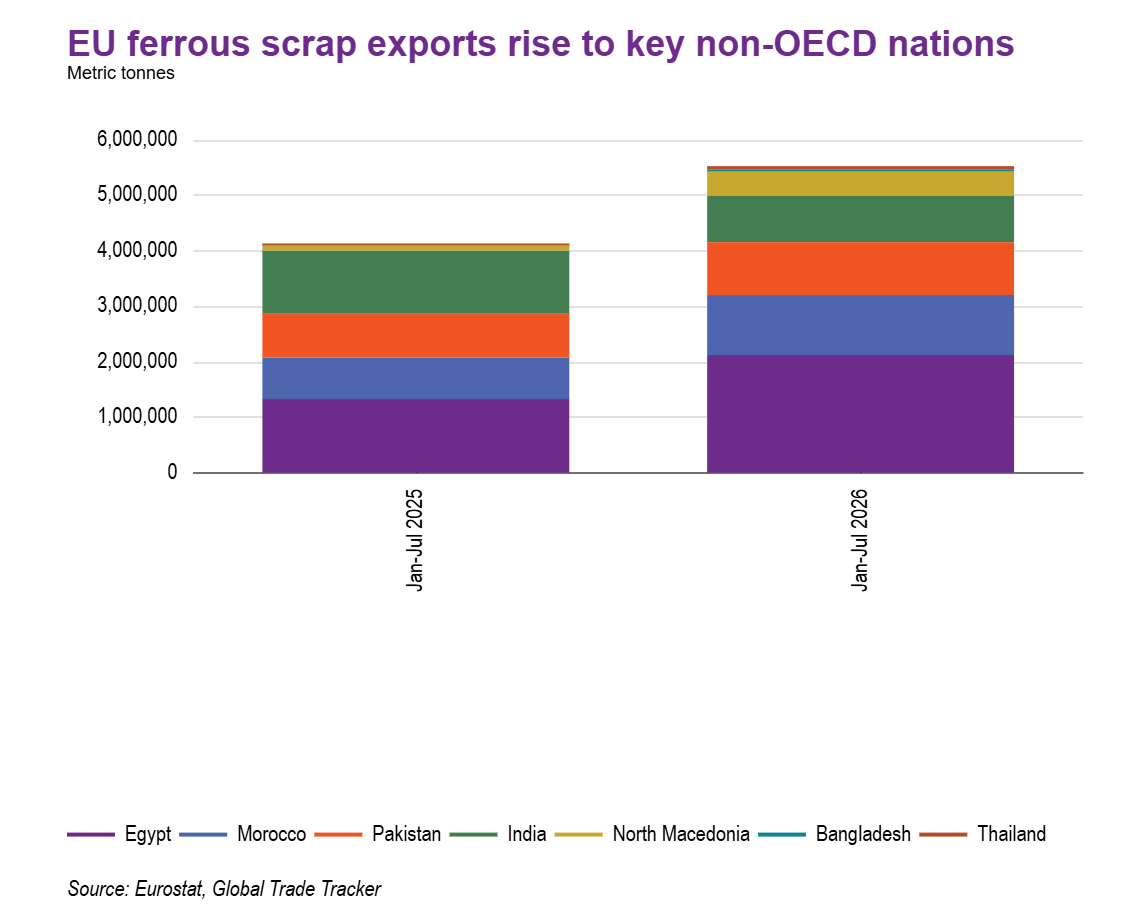
The EU is the world’s largest ferrous scrap exporting bloc, exporting 13.76 million tonnes under harmonized system (HS) code in January-June 2026, according to Eurostat data, up by 10.3% year-on-year.
Its largest single buyer, Turkey, is not affected by the proposed restrictions because it is a member of the OECD, but there is potential trouble for importers in Egypt, Pakistan and Morocco – which make up positions two to five on the list.
“I think it could cause quite a significant realignment rather than simply removing tonnage from the international market,” a major exporter source said this week. “Turkey is OECD so EU exporters can continue selling there, and I would expect more European scrap to be pushed towards Turkey and the EU domestic market.”
“The bigger impact could be in India, Pakistan and Bangladesh – those markets would have to replace EU supply from origins such as the UK, US, Japan, Australia and other Asian or Middle Eastern exporters,” he said. “That should increase competition for available scrap from those origins and potentially support higher CFR premiums in South Asia.”
“Egypt and Morocco will be most affected in terms of European steel scrap,” a second major scrap exporter source said.
There is still time for an appeal, so “there is not too much panic in the market yet, but for exporters, [this could be] very bad,” he said.
Egypt imported 2.12 million tonnes of steel scrap from the EU in the first six months of 2026, up by 59.7% year-on-year, according to the Eurostat data, while Morocco imported 1.08 million tonnes in the same period of time, up by 44.9%.
Both countries are raising ferrous scrap use due to rising local melting capacities for production of materials like rebar, and Egypt’s continued import safeguards of steel billet, according to market sources.
Knock-on effect in South Asia
Should key consumer markets in Asia such as India and Pakistan not receive approval to import EU waste materials under the final determination, demand for scrap in alternative East Asian export markets is expected to rise further, sources said.
This will have “an indirect but powerful impact” because importers from India and Pakistan relying on EU scrap will shift their focus to nations that export larger volumes to Bangladesh, such as Singapore, Malaysia and Australia, a Bangladeshi source said on Friday. “This will ultimately impact prices in South Asia.”
Asian ferrous scrap traders in East Asia said that although there is still time given this is a draft decision, demand from South Asian importers which currently buy from the EU may be redirected to Japan, Australia or New Zealand.
“If not from them, then where would they get their scrap from?” a Singapore-based trader said, highlighting that Bangladesh is especially vulnerable given its scrap import dependency.
The source, however, also cautioned that there might not be sufficient scrap to go around, adding that a good portion of scrap exported by Australia and Japan is already headed to Bangladesh.
Pakistan was the largest South Asian buyer of European steel scrap in the first half of 2026, with 952,110 tonnes – up by 18.5% year-on-year – while India purchased 832,375 tonnes – down 26.2%, according to the Eurostat data.
Fastmarkets’ calculation of the steel scrap shredded, index, import, cfr Port Qasim, Pakistan was $418.68 per tonne on Friday September 18, up from $365.19 per tonne on September 23, 2025.
Bangladesh imported just 40,154 tonnes from the EU over the same period, but imported major volumes from Asian and Oceania origins this year.
This includes 906,910 tonnes of imports from Japan, 499,707 tonnes from Australia and 462,887 tonnes from Singapore, according to Bangladeshi customs data.
UK position
One major exporter country in Europe not directly affected by the WSR rules is the United Kingdom, given the UK left the EU following a referendum in 2016.
Sources said they did not expect the UK to replicate the EU’s WSR rules at this time, which would allow UK-based scrap exporters unfettered access to non-OECD export markets.
“From a UK perspective it could actually create quite a sizeable opportunity,” the first exporter source said. “If UK material remains freely exportable while equivalent EU material is restricted, UK container exporters potentially become more strategically important to India, Pakistan and Bangladesh.”
“Given the volumes involved, I could certainly see buyers becoming much more focused on locking in UK supply,” he said, adding that he hasn’t “seen anything at this stage suggesting the UK will automatically follow the EU” given its waste shipment regime is now separate after the UK left the EU.
The second exporter source agreed, noting that he doesn’t think the UK will adopt similar WSR rules, and regards this as a benefit of the UK leaving the EU.
The UK is a pivotal exporter of ferrous scrap, and – like EU exporters – sells large volumes into key non-OECD markets including Egypt, Morocco and Pakistan.
UK exports of steel scrap were 4.92 million tonnes in January-July 2026, up by 7.5%, according to UK customs data.

European Commission proposes India, Pakistan scrap export ban
The European Commission has proposed major scrap importers India, Pakistan and Bangladesh be prohibited from procuring ferrous scrap from the EU starting 21 May 2027, Kallanish notes.
The Commission included the countries on its draft list of non-OECD countries that could be authorised to import non-hazardous waste from the EU once the Waste Shipment Regulation provision comes into effect next year. However, ferrous scrap was among the materials proposed by the commission not to be included. This stipulation also applies for Egypt and Saudi Arabia, among others.
Authorities have opened an online consultation on the draft list until 16 October.
The Waste Shipment Regulation, adopted in 2024, bans waste exports to non-OECD countries from next May; however, countries can request exemptions, but must demonstrate their capacity to manage waste sustainably.
The first list of countries authorised to receive waste from the EU will be established by the end of 2026. This list will be updated regularly and at least every two years, with the possibility for countries which are not on the list to reapply.
In a staff working document, the European Commission provides its assessment for each country. For ferrous waste, India’s application insufficiently demonstrated that pollution controls apply to treatment operations, the document notes. There is “no comprehensive” regulatory coverage of air emissions reduction for heavy metals, dust, dioxins and furans and PCBs, nor detailed requirements for wastewater treatment stages based on best available techniques.
“The regulatory framework lacks key provisions covering energy efficiency, including requirements for a stable shredder feed, energy efficiency plans, and energy balance records,” the Commission adds.
For Bangladesh ferrous scrap, “the management of residual waste and the incomplete implementation of pollution control measures during treatment raise concern. While Bangladesh has some basic controls in place, the framework does not fully cover key landfill safeguards, site verification and record-keeping requirements, or a comprehensive application of best available techniques. The application also lacks sufficient evidence on technical measures related to emissions control, energy efficiency, material recovery, wastewater management, and the handling and pretreatment of scrap.”
Although Pakistan met a number of requirements, it did not provide key requirements essential for metallurgical treatment: maintaining a stable shredder feed, increasing recovery of secondary materials, ensuring efficient energy use in secondary copper production, or preventing diffuse emissions during scrap pretreatment, the document states.
Egypt did not provide data on the proportion of metal waste that is recycled and referred to a lack of data, although it did indicate it is taking measures to increase the rate of recycled metal waste.
Saudi Arabia’s application did not demonstrate a ban on waste dilution or mixing for treatment residues and a ban on landfilling separately collected waste intended for reuse or recycling, the Commission says. The use of annual compliance testing and of independent laboratories were also not demonstrated. It also did not provide requirements for maintaining a stable shredder feed, implementing energy efficiency plans or energy balance records, controlling scrap quality to minimise pollutants, or preventing and reducing diffuse dust emissions.
Author: Adam Smith Austria


EU imposes GOES provisional safeguard, includes laminations, cores
The European Commission has imposed provisional safeguard measures on imports of grain-oriented electrical steel (GOES) products until 26 February 2027. The measure, welcomed by steelmakers’ association Eurofer, comprises tariff-rate quotas coupled with price thresholds, Kallanish notes.
Following an investigation launched in March, the Commission concluded that provisional measures were urgently needed to protect a strategic EU industry that is under threat from high import pressure – fuelled by global overcapacities and the closure of traditional export markets. Also included are cores that are already incorporated in transformers. The measures thereby also provide protection to transformer manufacturers downstream.
The analysis of import trends of the product concerned shows a 120% increase in import volumes in absolute terms during the period considered – 2021 to 2025 – a 141 % increase compared to EU production and a 66 % increase compared to EU consumption.
The price thresholds range from €2,800-5,000/tonne ($3,214-5,740) while the quotas for GOES range from 30,694 tonnes for China to 4,790t for South Korea, and for laminations and cores from 14,162t for Turkey to 2,694t for “other countries”.
“Europe cannot expand and strengthen its electricity grids without maintaining a European supply of Grain-Oriented Electrical Steel. This safeguard strikes the right balance: preserving a viable European GOES production base while keeping the market open to the imports needed by transformer manufacturers,” says Eurofer director general Axel Eggert.
The cost of the measure to EU electrification should be limited. Estimates indicate the measure would add only around 0.002 cents per kilowatt-hour to overall grid costs. GOES accounts for a small share of transformer costs, while transformers account for only a limited share of total grid investment, the association notes.
“By covering not only GOES coils but also laminations, cores and transformer cores incorporated in imported transformers, the measure prevents import pressure from simply shifting downstream. This ensures that EU transformer makers are not placed at a disadvantage against importers using artificially low-priced GOES outside the EU, while preserving access to the imports needed to compete in European and export markets,” it concludes.

EU mills/distributors interdependent, energy determines investment
EU mills and distributors are increasingly relying on each other amid limited export competitiveness and tighter import measures, while energy prices trump all other considerations for steelmaking transition investments in the bloc.
So concluded a panel of steelmakers’ representatives at last week’s EUROMETAL Regional Meeting Central Europe in Warsaw, attended by Kallanish.
Given the energy and carbon costs put on EU mills that foreign competitors are not burdened with, “we can forget about exports really, and being competitive exporting outside Europe,” exclaimed Jiri Mravec, head of innovation & transformation at Trinecke Zelezarny (TZ). “So without European customers, we don’t survive the next month … We are in this fight side by side and together. I mean, steelmakers and the whole downstream value chain, And in crisis, you find your friends.”
European customers will meanwhile shift towards domestic mill procurement due to the complexity of navigating the new trade barriers. This shift has been gradual so far because of the high stocks accumulated in prior quarters, said Tomasz Plaskura, chief marketing officer East Europe – ArcelorMittal Europe Flat Products.
“In terms of competitiveness, of course, it’s our primary objective to stay competitive in Europe in the entire value chain,” he noted, adding he agreed with the need to extend import measures downstream.
The Emissions Trading System (ETS) has so far meanwhile just been a stick rather than a carrot for mills. In terms of allowances, TZ is overallocated for its blast furnace alone, but when taking into account its captive power plant that utilises BF off-gases, it is short off allowances and burdened by the cost. “We are already having discussions on how do we put this in [our steel] prices in terms of some CO2 surcharge or something,” Mravec noted.
“If we just increase the price by €160, we are out of the market very quickly. So it forces us to decarbonise, but they force us to decarbonise in the times when we are poor … We don’t have the Ebitda margin to go to banks,” he added.
“If you plug in €200 per megawatt hour of electricity in the Excel, it will give you no ROI for any electrification business case, and no one’s willing to pay for the green steel extra premium, that I can confirm,” he continued. CBAM “has to be working really well” for mills to achieve the steel prices required to make the investment feasible.
Fellow Czech mill Nova Hut, currently a re-roller, faces the “unique situation” of needing to purchase ETS allowances for its reheating furnaces and also navigating CBAM to import the required semi-finished steel feedstock, said Nova Hut chief executive Radek Strouhal.
“It’s not very easy with the CBAM because we are approaching the suppliers asking about certification … During February, we received cross benchmark figures, so we were offering material in the last quarter, last previous year, and not knowing what will be the price, just estimating where the benchmark can be,” he continued.
The firm’s plan to install an EAF “is the only future we can have”, he added. However, it will need “predictable” electricity prices to operate. With EU gas prices shooting up in September, it would be difficult to imagine having to pay €200/MWh for electricity from the grid, he added. Nuclear power “is the only way”.
Competitive energy prices are “the only driver to keep those [steelmaking electrification] investments in Europe” as they form the business case, more so than subsidies, Plaskura said.
Mravec said TZ’s EAF subsidy application is “hitting the wall with financing”. The firm’s strategy is to operate an EAF alongside a BF to have flexibility. “I am 100% certain there will not be a successful hydrogen DRI in Central Europe. This is relevant for particular geographic regions where you can get so cheap renewable electricity that you produce so cheap hydrogen to be able to be cost competitive,” he concluded.


Author: Adam Smith