

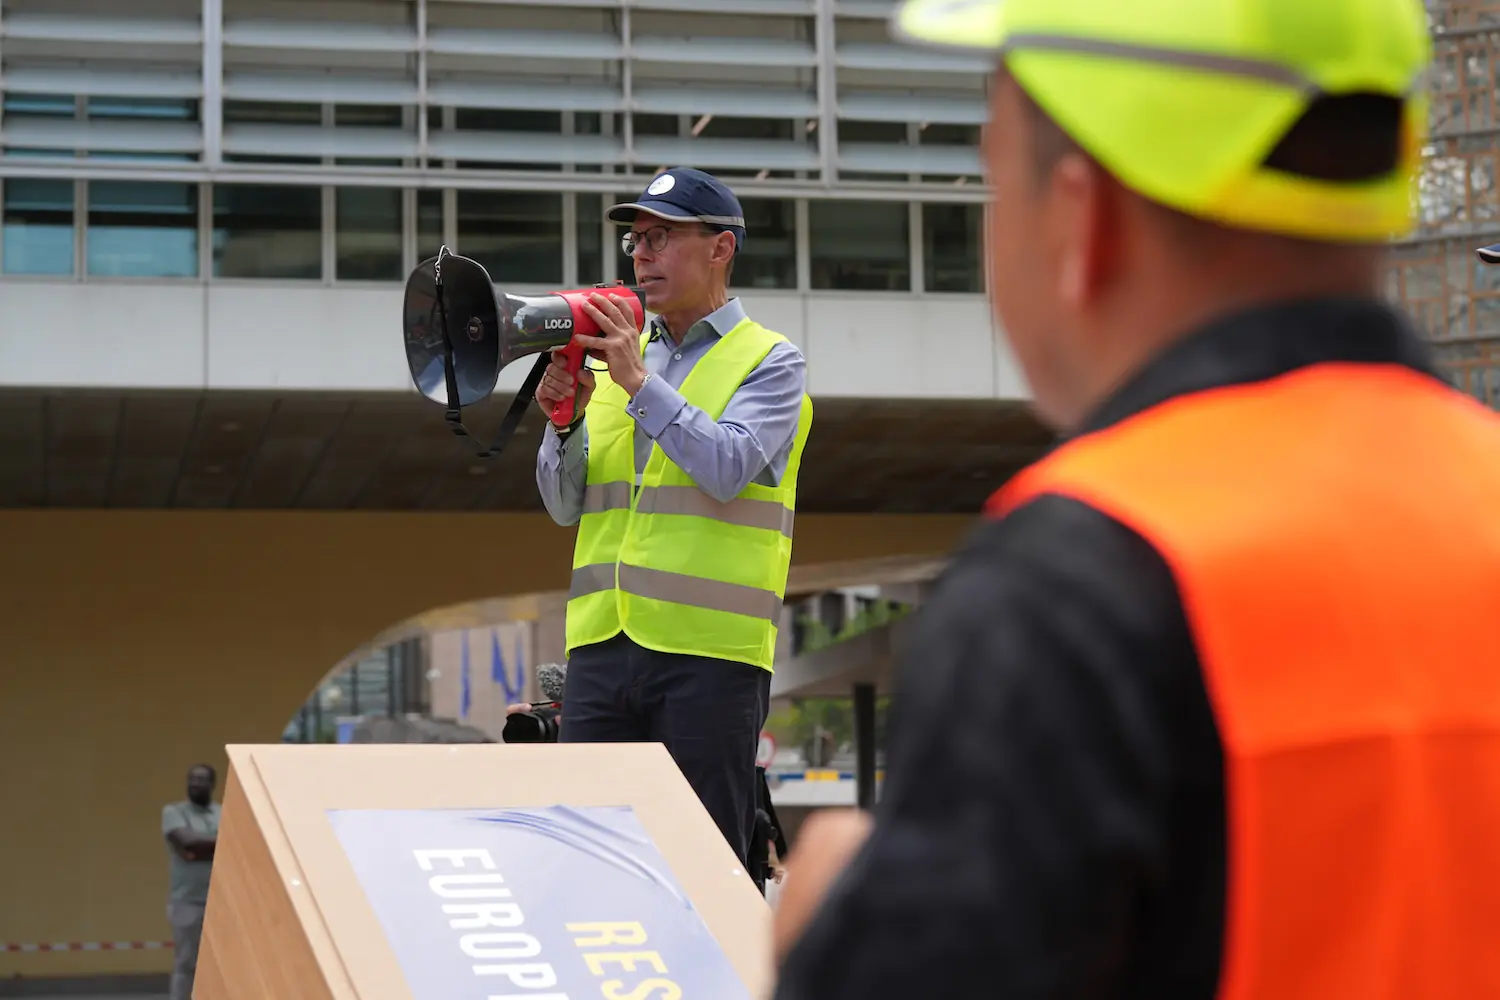
European Parliament adopts position on extending CBAM to downstream steel and aluminium products
The European Parliament has today adopted its position on the extension of the Carbon Border Adjustment Mechanism (CBAM) to downstream steel and aluminium products, marking an important step in recognising that carbon leakage has increasingly shifted beyond primary materials and into manufactured goods.
For several years, EUROMETAL has highlighted the growing imbalance affecting European manufacturers, service centres, distributors and traders, as imported steel- and aluminium-containing products have continued to enter the EU market without being subject to equivalent carbon-related obligations.
The Parliament’s position acknowledges this challenge by supporting a broader application of CBAM to downstream products. While this represents significant progress, EUROMETAL believes that further work is needed to ensure the mechanism effectively delivers a genuine level playing field across the entire European manufacturing value chain.
In its reaction published today, EUROMETAL identifies four key priorities for the next stages of the legislative process:
- Extend CBAM coverage to all relevant steel-intensive and aluminium-intensive products.
- Accelerate implementation to avoid further carbon leakage and industrial relocation.
- Develop an effective solution for European exporters competing in global markets.
- Address the cumulative impact of regulatory costs and trade measures affecting manufacturing competitiveness.
EUROMETAL welcomes the European Parliament’s recognition that carbon leakage increasingly occurs through downstream manufacturing rather than primary materials alone. However, the Federation considers that the current proposal still leaves important product categories outside the scope of CBAM, creating opportunities for circumvention and continuing to expose European manufacturers to unfair competition.
As discussions continue between the European institutions, EUROMETAL will remain actively engaged in advocating for policies that protect the competitiveness of Europe’s manufacturing value chain while supporting the European Union’s climate objectives.
The Federation reiterates that effective climate policy and industrial policy must go hand in hand. Ensuring fair competition across the entire value chain is essential to maintaining manufacturing, investment, innovation and quality jobs in Europe.
Read EUROMETAL’s full reaction to the European Parliament’s position on downstream CBAM here.

Gestamp: Europe must protect automotive value chain amid growing Chinese competition
Spanish automotive components manufacturer Gestamp has warned that the decline of Europe’s automotive industry could have far-reaching consequences for other industrial sectors, including steel, amid increasing competition from Chinese automakers.
Speaking to the Financial Times, Gestamp chairman and founder Francisco Riberas stated that Europe’s automotive industry is facing an existential challenge as Chinese manufacturers strengthen their position in electric vehicles and European vehicle production continues to decline. According to Riberas, European vehicle production has fallen by 20-25 percent since 2017, when global automotive output peaked.
Automotive industry supports broader European industrial base
Riberas stressed that the automotive industry acts as an anchor for several other European industries, warning that losing automotive production could result in the erosion of Europe’s broader industrial base. European automotive manufacturing currently accounts for approximately seven percent of the region’s GDP and supports nearly 14 million jobs. While Riberas said Europe should welcome investments by Chinese automakers, he stressed that such investments need to generate local production and employment throughout the supply chain. According to him, Chinese automakers currently producing vehicles in Europe still source most of their components from China, while Gestamp has only a limited number of contracts with Chinese automakers operating in Europe.
Riberas stated that it is therefore essential for Chinese manufacturers to increasingly source locally produced components, warning that merely assembling vehicles in Europe using imported Chinese components would undermine the European automotive value chain. He noted that traditionally every job at a European vehicle manufacturing plant has supported three jobs in the region’s automotive component industry. The Gestamp chairman also pointed to differences in financing conditions, arguing that European automotive companies face disadvantages compared to Chinese competitors, which he said have access to significantly more favorable financing.
Gestamp supports EU Industrial Accelerator Act
In this context, Riberas expressed support for the EU’s proposed Industrial Accelerator Act (IAA), describing defensive measures as necessary to provide European industry with time to improve its competitiveness. The proposed legislation includes a 70 percent local content threshold for automotive components for investments seeking access to subsidies or public contracts, while also providing for greater scrutiny of Chinese foreign direct investments exceeding €100 million in certain strategic sectors.
At the same time, Riberas stressed that protective measures alone would not be sufficient. He called for a broader European strategy for the automotive industry, including increased investment in technology, digitalization and artificial intelligence to improve competitiveness.
Author: SteelOrbis Editorial Team


European Parliament votes on strengthening CBAM for steel-intensive products
Today, the European Parliament is scheduled to vote on amendments to the Carbon Border Adjustment Mechanism (CBAM), including proposals aimed at extending its scope to additional steel-intensive products.
Ahead of the vote, the European Steel Association (EUROFER) called on Members of the European Parliament (MEPs) to address what it describes as remaining loopholes in the current CBAM framework.
According to EUROFER, while imported steel is subject to carbon-related obligations under the CBAM, many products manufactured from steel remain outside its scope. The association argues that this creates an uneven competitive environment, allowing imported manufactured products to enter the EU market without facing equivalent carbon costs.
EUROFER supports amendments adopted by the European Parliament’s Committee on Industry, Research and Energy (ITRE) that would extend CBAM coverage to additional steel-intensive products.
Commenting ahead of the vote, Axel Eggert, Director General of EUROFER, stated:
“Europe’s steelmakers are investing billions to produce cleaner steel, but they cannot make that transition without a level playing field. MEPs have the opportunity to strengthen CBAM so that investing in low-carbon steel production in Europe makes economic sense.”
In addition to extending CBAM to more steel-intensive products, the European Parliament is also considering amendments relating to stainless steel production. These include proposals to account for emissions associated with ferro-nickel and nickel pig iron used in imported stainless steel, as well as measures intended to close potential loopholes linked to inward processing arrangements.
The outcome of today’s vote will contribute to shaping the future evolution of the CBAM framework as the European Union continues to balance climate objectives with industrial competitiveness.

Buyers resist price hikes for local HRC in Europe, import deals rare
The market leader was said to be targeting €800 ($930.76) per tonne delivered in Northern Europe, which is netting back to €780 per tonne ex-works.
This was considered high by customers with most recent deals in the region varying within the range of €740-760 per tonne ex-works.
Sources said that the level of €750 per tonne ex-works was most common in recent transactions; however, if a supplier was selling material that may include significant extras, discounts could be applied.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was calculated at €745 per tonne on September 10, down by €5 per tonne from €750 per tonne on September 9.
The index was down by €3.75 per tonne week on week but up by €27.5 per tonne month on month.
The Italian market remained quiet. While allocation of the material remains limited as Metinvest has not resumed offers since the restart of the Valsider mill, which is reporting a significant backlog, buyers were in no hurry to book volumes available in the market within the range of €730-740 per tonne ex-works.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €732.50 per tonne on September 10, unchanged day on day.
The index was up by €10.83 per tonne week on week and €21.87 per tonne month on month.
The effect of the reduced availability of the material was also seen in Central Europe, where suppliers also raised prices due to the absence of offers from Ukraine.
Ukraine’s sole flat steel supplier Metinvest came under a Russian attack on its Zaporizhstal Iron & Steel Works in mid-August and therefore halted its exports of flat steel.
Offers in the region varied within the wide range of €740-770 per tonne CPT during the week to Wednesday, September 10, which is netting back to €720-750 per tonne ex-works, with the upper end considered unworkable by buyers.
Fastmarkets’ weekly price assessment for steel hot-rolled coil domestic, exw Central Europe was €720-730 per tonne on Wednesday, September 9, up from €715-720 per tonne on September 2.
Later on Wednesday, after the assessment was filed, tradeable levels were estimated within the range of €730-755 per tonne CPT or €710-735 per tonne ex-works.
On Thursday, reports emerged of mills selling at lower levels, reaching €750-760 per tonne delivered or €730-740 per tonne ex-works.
Import
The import market was largely quiet with rare deals heard as buyers have become extremely cautious when it comes to purchasing import material, considering reduced quotas and higher penalties for exceeding them, as well as uncertainties over the final Carbon Border Adjustment Mechanism (CBAM) costs.
A 20,000-25,000 tonne Vietnamese cargo was heard booked at $670 (€576) per tonne CFR in Southern Europe.
Indian HRC was reported traded within the range of $665-680 (€572-585) per tonne CFR, depending on the tonnage.
Following the recent sales, Indian suppliers were said to have withdrawn from the market, with new offers indicated at no less than $700 (€602) per tonne CFR.
An Indian source reported offers as high as $715-725 (€615-623) per tonne CFR.
Turkish material was available within the range of $630-650 (€541-560) per tonne CFR.
Reports of Egyptian HRC offers came at $690-700 (€593-602) per tonne CFR; however, they could not be confirmed by an Egyptian supplier, with one source saying that a new round of offers had not yet begun.
Fastmarkets’ weekly price assessment for steel hot-rolled coil import, cfr main port Southern Europe was €540-585 per tonne on September 9, widened upward from €540-565 per tonne on September 2.
On a DDP basis, Turkish material was heard offered in Italy and Greece at €710 per tonne.
Asian material was available within the range of €740-750 per tonne DDP.
Fastmarkets’ weekly price assessment for steel hot-rolled coil import, ddp Southern Europe was €710-740 per tonne on September 9, widened downward from €720-740 per tonne on September 2.
Author: Vlada Novokreshchenova


Polish rebar and wire rod prices steady amid limited trading activity
“Producers are trying to push prices higher due to increased energy and gas costs. However, the market remains flat, and buyers are currently waiting to see how the situation develops,” a distributor source told Fastmarkets.
Market participants described demand as subdued, with buyers maintaining a wait-and-see approach despite producers’ attempts to increase prices in response to higher production costs.
In the wire rod segment, indications were heard at 2,900-3,100 zloty ($780-834) per tonne delivered.
Fastmarkets’ weekly price assessment for steel wire rod (drawing quality), domestic, delivered Poland, remained unchanged at 2,900-3,100 zloty per tonne on Friday.
In the rebar segment, limited indications and offers were heard, although no transactional activity was reported to support those levels.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, CPT Poland, was 2,650-2,680 zloty per tonne on Friday, unchanged week on week.
Author: Nia Radenkova

Arvedi bids for Italian auto steel distributor AMCLN after ArcelorMittal withdrawal
Arvedi is seeking full ownership of the business, rather than only the 51% stake that ArcelorMittal had agreed to purchase from the Italian components maker under a broader bank-debt restructuring agreement.
ArcelorMittal withdrew from the transaction after Rome intervened under its “golden power” rules. The conditions imposed by the Italian state included maintaining existing operations for at least five years and requiring state approval for any workforce or operational restructuring, according to sources familiar with the matter cited by Bloomberg.
The collapse of the buyout paved the way for Arvedi, which had shown interest earlier in the process, to return with an offer for the entire company and plans to increase throughput across its facilities.
AMCLN is currently operating well below capacity, with processed flat steel volumes estimated at 500,000-600,000 tonnes per year compared with a nominal capacity of close to 1 million tonnes per year, an Italy-based distributor told Fastmarkets on Thursday September 10.
“The acquisition would allow Arvedi to streamline downstream distribution and move closer to end-users, bypassing intermediate supply chains,” the distributor said.
The transaction could have a significant long-term impact on the Italian flat steel distribution market, particularly by intensifying competition for independent steel service centres (SSCs), a second Italy-based distributor said.
ArcelorMittal and CLN established AMCLN in 2015 to process and distribute flat carbon steel, with ArcelorMittal initially holding a 49% stake. AMCLN employs about 400 people and recorded revenue of €801 million ($931 million) in 2022. The European Commission had cleared the group’s planned full takeover in late April 2026 before Rome intervened.
The withdrawal comes against the backdrop of long-standing friction between ArcelorMittal and Rome over the former Ilva steelworks (Acciaierie d’Italia), involving disputes over production levels, environmental commitments and governance.
ArcelorMittal declined to comment when contacted by Fastmarkets, while Acciaieria Arvedi and CLN had not responded to requests for comment by the time of publication.
Author: Hristo Rimpopov
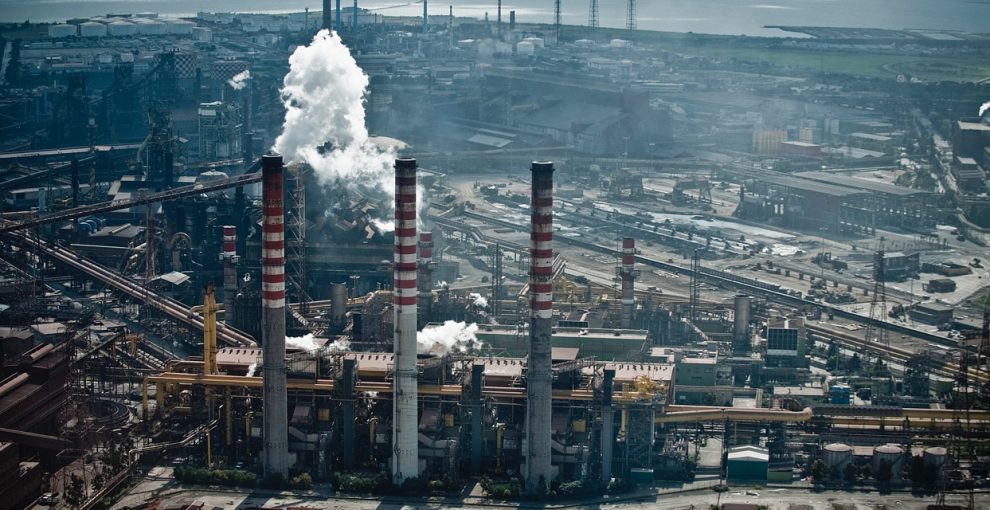
Italy risks being left with one primary HRC producer after court upholds Ilva shutdown
The Milan Court of Appeal on Friday upheld an order requiring the shutdown of blast furnaces at the former Ilva steelworks in Taranto, dealing a major blow to operator Acciaierie d’Italia (ADI).
In their ruling, the judges wrote that balancing competing interests “can only favor the health protection reasons for which the suspension of production in the hot area was ordered.” Citing recent Constitutional Court rulings and Article 41 of the Italian Constitution, the court stressed that private economic initiative cannot be conducted in a manner that causes harm to health or the environment.
The decision rejected ADI’s appeal against a July 27 ruling by the same court, which had instructed the company to cease all hot-end operations within 90 days. Under that order, operations may resume only after all asbestos has been removed from the site and measures are implemented to bring dust emissions within statutory limits, after judges highlighted that asbestos is linked to mesothelioma, a cancer diagnosed in Taranto and nearby Statte at four times the expected national rate.
The site employs around 8,000 direct workers and supports a wide contractor network in a city of under 200,000 people. Following the ruling, Italian metalworkers’ unions Fim, Fiom, and Uilm called on the government to immediately convene a meeting at the prime minister’s office, demanding a freeze on layoffs and warning of a potential “social explosion” if the plant’s future is reduced to job cuts and state-subsidized furloughs.
In response, Prime Minister Giorgia Meloni announced that the government would reconvene the standing working group on the steelworks immediately. Meloni said that Rome is “working with decisions that are beyond our control” to find a solution, underscoring that the Taranto dossier remains one of the files the government is dedicating the most time to.
ADI had warned that shutting the facilities risks jeopardizing future production, noting that blast-furnace cooling procedures could make restarting operations impossible without extensive and costly repairs. A permanent shutdown of Taranto’s hot end would leave Acciaieria Arvedi as Italy’s sole primary domestic hot-rolled coil (HRC) producer. While other domestic players roll coil, they operate strictly as re-rollers reliant on external slab feed rather than primary steelmaking.
Currently, the Italian domestic flat steel market is quiet, with low downstream demand leading to minimal negotiated volumes and no fresh trading activity reported. Supply tightness persists, as Metinvest’s Ferriera Valsider mill has resumed HRC rolling following an engine-related force majeure declared in late August, but continues to withhold spot offers due to an extensive order backlog.
With no new bids, offers or transactions heard on Thursday September 10, the market was still anchored to indications heard on Wednesday September 9. On that day, a supplier indicated workable levels for October delivery at €750 ($872) per tonne delivered (netting back to €730 per tonne ex-works), while two buyers reported mill offers at €730-740 per tonne ex-works with no deals concluded. Buyer-reported minimum levels of €710-720 per tonne ex-works were widely dismissed by sellers and other market sources as too low and no longer available.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €732.50 per tonne on September 10, unchanged day on day.
Author: Hristo Rimpopov

German EPP pushes narrower ‘Made in Europe’ rules
German delegation in the Parliament’s centre-right EPP group is taking a cautious stance on the Industrial Accelerator Act (IAA), arguing that ‘Made in Europe’ criteria should be “targeted”.
The IAA aims to favour European-made goods in public support schemes and public procurement. In an internal note published by Contexte, a dozen EPP delegations set out their positions as work on the parliamentary report begins.
The German delegation, the group’s largest, also said it wants equivalent status to remain available to third countries with trade agreements with the EU, provided they offer reciprocal access to public aid and procurement markets.
“Where steel and aluminium are already covered through CO₂-related requirements, no additional overlapping origin thresholds should apply,” they wrote. The delegation also rejects any binding reindustrialisation target, while the Commission has proposed raising the EU industry’s share of GDP to 20% by 2035.
The EPP therefore appears divided on several issues, including the 20% target and which third countries should qualify for ‘Made in Europe’ status.


German steel output slips as weak demand interrupts recovery
German crude steel production fell year on year for the first time in 2026 during July as persistently weak demand interrupted the sector’s recovery, steel industry association Wirtschaftsvereinigung Stahl said Sept. 9.
Crude steel output totaled 2.68 million metric tons in July, down 1.8% from the same month of 2025. The decline was driven by the blast furnace-basic oxygen furnace route, where production dropped 4% year over year to 1.83 million mt. By contrast, electric-arc furnace steel output increased 3.3% to 849,000 mt.
Pig iron production also weakened in July, falling 4.5% from a year earlier to 1.66 million mt. Hot-rolled steel production was more resilient, rising 1.4% to 2.54 million mt.
Despite the July slowdown, German steel production remained substantially above 2025 levels over the first seven months of the year. Crude steel output reached 21.31 million mt in January-July, an increase of 6.8% from the corresponding period of 2025.
Annualizing the January-July production rate would result in output of about 36.5 million mt for 2026, compared with approximately 34 million mt produced in 2025, according to the association.
The year-to-date figures showed a marked divergence between Germany’s two main steelmaking routes. Basic oxygen furnace production increased 8.5% year over year to 14.59 million mt in January-July, while electric-arc furnace output rose by a more modest 3.4% to 6.72 million mt.
Pig iron production totaled 13.29 million mt over the seven-month period, up 7.3% year over year. Production of hot-rolled steel products increased 4.2% to 18.65 million mt.
The July contraction indicates that weak demand continued to constrain Germany’s steel sector, despite the stronger cumulative production performance recorded so far in 2026.
On Sept. 8, Platts, part of S&P Global Energy, assessed domestic hot-rolled coil in Northern Europe at €730/mt ($850/mt) ex-works Ruhr, and in Southern Europe at €720/mt ex-works Italy, both stable day over day.
Author: Annalisa Villa
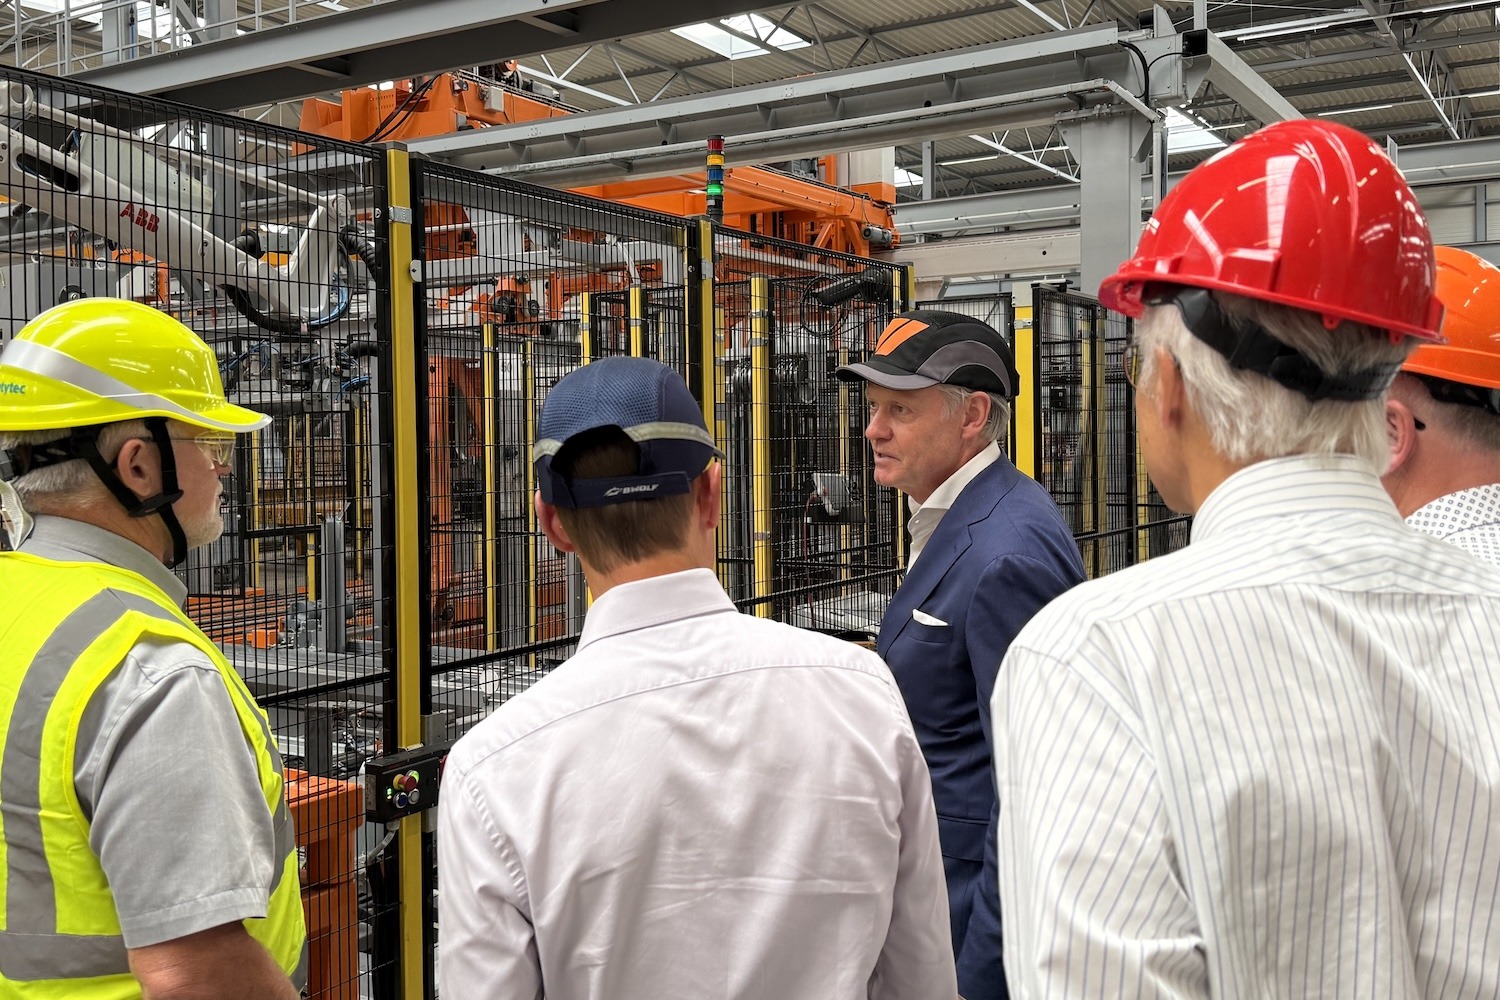
EUROMETAL SSC Working Group meets in Maastricht
Twenty-nine participants representing 19 companies gathered in Maastricht on 10 September for the EUROMETAL Steel Service Centres (SSC) Working Group meeting for Germany, Austria, Switzerland, Belgium and the Netherlands.
Hosted by Vogten Staal BV at Buitenplaats Vaeshartelt, the meeting was opened by Thomas Niederhofer of Knauf Interfer Stahl Service Center, Chairman of the Working Group and Vice-President of EUROMETAL, together with Jack Papen, Managing Director of Vogten Staal.
Participants discussed the growing regulatory and operational challenges facing steel service centres, including CBAM, customs requirements, quota administration, logistics, packaging rules and load securing.
EUROMETAL President Alexander M. Julius presented the federation’s current political priorities and reported on the European Convoy for Industrial Competitiveness held in Brussels on 7 September. He reiterated the need for a level playing field across the entire steel value chain, ensuring that steel-intensive manufactured products entering the European market are subject to equivalent carbon, customs and trade obligations.
Konrad Rainer of Cargo Safetytec delivered a presentation entitled “Load Securing and Transport Safety— Initial Solutions”, addressing key responsibilities and practical considerations for the safe transportation of steel products.
The meeting also highlighted the new melt-and-pour documentation requirement taking effect on 1 October 2026. Members were encouraged to obtain the necessary evidence from their suppliers without delay.
Given the complexity of the new EU Packaging Regulation, the Working Group will organise a dedicated online session to help companies develop a shared understanding of the forthcoming obligations.
The day concluded with visits to two Vogten Staal sites in Maastricht, giving participants an opportunity to gain first-hand insight into the company’s operations.
EUROMETAL thanks Vogten Staal BV for hosting the meeting and site visits, as well as all participants and speakers for their valuable contributions.
