

FEDIL’s René Winkin: Brussels convoy underlines the urgency of European industrial action
René Winkin, General Manager of FEDIL, highlighted the European Convoy for Industrial Competitiveness during an interview with RTL Radio Luxembourg on 10 September.
Speaking ahead of the FEDIL Industry Day, Winkin discussed the need to strengthen the strategic autonomy and competitiveness of Luxembourg and Europe. He pointed to the demonstration held in Brussels on 7 September as a clear illustration of the urgency facing European industry. During the interview, the RTL journalist noted that the Brussels demonstration had brought industry representatives and workers together in the streets.
Winkin described this joint mobilisation as both significant and exceptional:
“If we fall behind, factories here will close—first perhaps in traditional industrial sectors, but eventually in technology sectors as well. This affects people. It is truly remarkable that industry associations are taking to the streets alongside trade unions. That is something rather exceptional.”
He stressed that Europe’s industrial competitiveness and strategic sovereignty are closely connected. In his view, European industrial policy must move beyond statements of intent and deliver concrete results at a much faster pace.
“For these two reasons, we in Europe need to pay much more attention to industrial policy again—not simply by announcing intentions, but by demonstrating that we can deliver at the necessary speed.”
From policy ambitions to concrete action
Strategic autonomy was the central theme of the 2026 FEDIL Industry Day, held under the title “Strategic autonomy: From policy ambition to competitive industry.”
During his RTL interview, Winkin identified investment, faster permitting procedures, digital capacity and access to suitable industrial sites as essential priorities. He warned that Europe’s growing dependence on external providers in strategic sectors could become dangerous unless action is taken quickly.
At the same time, he emphasised that greater European resilience should not result in blanket protectionism. Instead, Europe must create the conditions that enable its industry to invest, innovate and compete successfully on international markets.
The full interview is available on RTL Luxembourg.
ArcelorMittal and Moeve launch partnership for low-emissions steel technologies
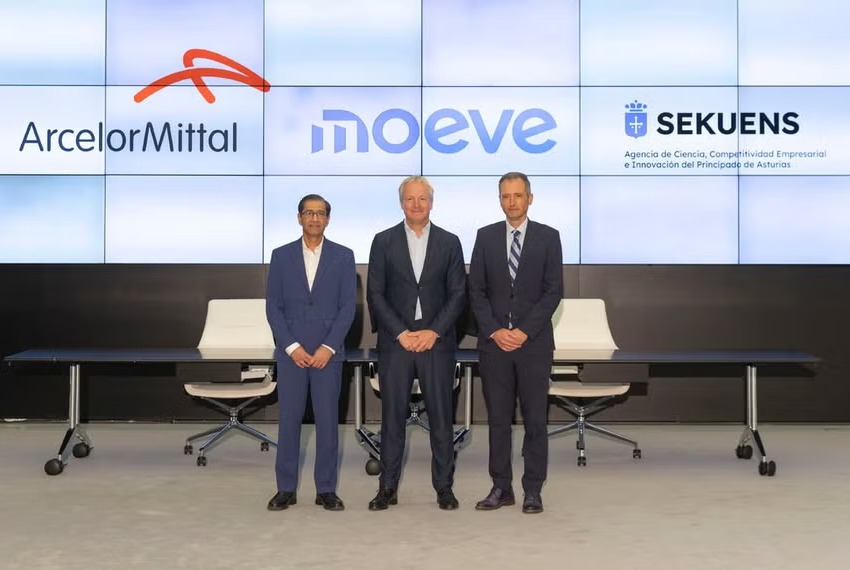
Global steelmaker ArcelorMittal and Spanish energy company Moeve have announced a partnership to establish a new platform aimed at developing technologies that use green molecules to support low-emissions steel production and industrial decarbonization.
The Green Molecules to Green Steel (G2G) platform will be established as a 50-50 partnership, subject to the necessary regulatory approvals, and will combine the companies’ expertise in innovation, energy solutions and industrial operations. The platform will be financed through the companies’ own resources and public support.
The Asturian Agency for Science, Business Competitiveness and Innovation (Sekuens) will support the initiative through existing and future innovation programs in Asturias. The participation of other regional and national public agencies and private entities may also be considered, provided they are aligned with the platform’s objectives and governance structure.
G2G to develop green molecule technologies for steel production
The partnership will focus on developing industrial demonstrators that can subsequently be scaled up at production facilities. Technologies under consideration will include green molecules such as biomethane and biogas, renewable hydrogen and its derivatives and second-generation biofuels, as well as other decarbonization solutions such as more efficient catalysts.
The platform, which will be supported by Moeve and ArcelorMittal’s innovation centers, will also explore carbon capture technologies, biotechnology for improving production processes and artificial intelligence for developing new materials. Startups, universities and technology centers will be able to participate in the collaborative innovation ecosystem.
Author: SteelOrbis Editorial Team


EU steel import quotas utilization reaches 99 percent for some products
According to European Commission data, several steel import quotas allocated to various countries have been exhausted in the final month of the EU quota period from July 1 to September 30. Quota utilization rates for some product quotas have exceeded 80 percent, while some have reached even 99 percent.
Among the exhausted quotas, Australia has used up its quota of 11,830 mt hot rolled coil (1A), while India has exhausted its quotas of 54,334 mt for organic coated sheets and 6,158 mt for other welded pipes. As regards quarto plate quotas, South Korea, Macedonia, the UK and Turkey have exhausted their quotas of 79,917 mt, 20,671 mt, 8,284 mt and 7,007 mt, respectively. In addition, Turkey has used up its quotas of 1,280 mt for railway material and 24,235 mt for non-alloy wire. China has exhausted its quota of 39,484 mt for merchant bars and light sections quota, while Algeria has used up its quota of 15,940 mt for rebar. Meanwhile, Ukraine’s quotas of 6,640 mt for hollow sections and 20,167 mt for other seamless pipes have been exhausted.
Under the “Other Countries” category, quotas of 24,933 mt for cold rolled sheets, 33,338 mt for metallic coated sheets (4A), 6,968 mt for organic coated sheets, 6,446 mt for tin mill products, 18,829 mt for quarto plate and 7,072 mt for non-alloy wire have been used up.
Under the “FTA-Other Countries” category, quotas of 12,761 mt for metallic coated sheets (4A), 22,585 mt for metallic coated sheets (4B) and 5,149 mt for hollow sections have been used up, while the 22,682 mt quarto plate quota under the “FTA-Country-Specific” category has also been exhausted.
The quotas with utilization rates above 80 percent can be seen in the table below.
| Product | Country | Quota volume (mt) | Usage (%) |
|
HRC (1A) |
Hindistan | 149,318 | 98.0 |
| South Korea | 115,457 | 85.38 | |
| Vietnam | 103,743 | 95.51 | |
| CRC | South Korea | 63,652 | 86.35 |
| Ukraine | 26,549 | 98.25 | |
| Electrical sheets (3B) | Taiwan | 5,166 | 95.68 |
| Metallic coated sheets (4A) | Taiwan | 33,783 | 94.12 |
| South Korea | 26,119 | 91.59 | |
| Stainless cold rolled sheets and strips | Taiwan | 13,246 | 90.96 |
| Other countries | 8,442 | 99.48 | |
| Merchant bars and light sections | Macedonia | 13,617 | 80.55 |
| Other countries | 11,809 | 98.2 | |
| Rebar | Egypt | 36,091 | 99.82 |
|
Wire rod |
Ukraine | 47,286 | 92.31 |
| Switzerland | 40,548 | 99.63 | |
| Egypt | 21,678 | 99.98 | |
| Angles and sections | Turkey | 13,455 | 99.55 |
| Other seamless pipes | Other countries | 9,824 | 95.71 |
| Cold finished bars | Turkey | 7,045 | 98.4 |
| Switzerland | 6,054 | 89.69 | |
| Non-alloy wire | Ukraine | 20,689 | 86.76 |
Author: SteelOrbis Editorial Team

EU slowly digests new local flats price levels, import activity remains sporadic
No significant price change has been seen in the flats market in the EU over the past week, but, while supply of CRC is considered to be a bit tight, based on the recently announced import limitation, in the HRC segment with the official offers being stable the mills’ targets have not been met fully by buyers, at least not yet.
In Italy, while the targeted levels have been voiced since last week at €750/mt ex-works, the reality is that deals are scarce and for now most deals are not exceeding €720-730/mt, with rare deals barely touching €740/mt ex-works. In Spain, with ArcelorMittal aiming at €790/mt and closing at €750-760/mt delivered maximum, other mills are offering at €750/mt ex-works, with deals being done at €735-740/mt delivered, SteelOrbis understands. In the northern countries of the EU, while the targets are up to €760-770/mt ex-works, the reality is closer to €735-740/mt FCA/delivered still. However, few have doubts regarding the uptrend in the EU. “Once the inventories from old prices are finished, they [domestic buyers] will not have much choice but to accept local prices, since imports are quite limited at the moment,” a market source commented to SteelOrbis.
In the import HRC segment, few offers are heard on CFR basis since buyers are cautious and would like to avoid risks as much as possible. According to sources, following deals from India for sizeable volumes at $680-690/mt CFR, some new offers have been voiced at $720/mt CFR, which is considered too high under the current market conditions. Turkey has been offering at around €550/mt CFR (with no AD duty included) while on US dollar basis offers have been reported at $630-650/mt CFR depending on the buyer, in line with last week’s levels. In the DDP segment, ex-Taiwan offers have been reported at €730/mt DDP Bilbao, while Turkey is offering at €710-720/mt DDP and Japan has been standing at €740/mt DDP, sources reported.
In the CRC and coated steel segments, the market situation has been roughly unchanged over the week in the domestic market, with CRC being priced at €850-880/mt and up to €890-920/mt ex-works across the EU. While the workable levels are at the lower end of the range, some sources report the supply of CRC in the market is somewhat tight. In the HDG segment, local prices have been maintained at €850-870/mt and up to €880/mt ex-works in some cases.
In the import segment, CRC from South Korea has been on offer at €880/mt DDP, while India has been voicing $810-820/mt CFR. Offers from Vietnam for 0.5 mm Z100 material have been at $860/mt CFR, while on DDP basis the same origin has been on offer at €920/mt, SteelOrbis has heard.
Author: SteelOrbis Editorial Team

Upward pressure persists on most European longs prices, mood fails to improve
Overall, the European longs market is showing mainly nominal upward price pressure: the increases sought by steel producers are supported by costs, while orders, buying interest and actual deal prices do not yet indicate a widespread recovery in demand.
According to market participants and as anticipated by SteelOrbis last week, German steel producers are aligned in seeking increases of around €20/mt, citing higher operating costs. However, these increases have not yet been reflected in transactions: “In fact, orders have been concluded at August prices, namely €640/mt delivered for rebar,” one market participant stated, adding, “The increase requests are mainly a signal to the market that prices will not decrease.”
In terms of demand, the situation in Germany appears slightly better than in Italy, mainly due to the launch of some infrastructure projects and defense investments, while the residential construction sector remains weak. Meanwhile, the German steel industry is determined to keep the government’s attention focused on securing reliable funding for industrial competitiveness and the green transformation as it prepares to submit its draft federal budget for 2027 to the Bundestag.
As for the Polish market, no major movements have been reported, and the overall sentiment remains cautious amid import pressure.
Sentiment in Spain is also rather weak. According to one market participant, “There could be a price rebound of around €10-15/mt, but it will mainly be due to higher costs and support from the export market outside the European Union,” he stated. “The wire rod segment is flooded with imports,” he also noted. According to one source, current drawing quality wire rod prices in the Spanish market are standing at €675-690/mt delivered, while mesh quality wire rod prices are at €660-670/mt delivered. Overall, the same source reported limited buying interest in the domestic market. As for exports, the rebar price to Irish and UK ports has been reported at €630/mt FOB, down by €40/mt compared to the latest indications.
In the import market, offer prices from Turkey continue to increase, although they are attracting limited interest in the European Union. According to reports, both rebar and wire rod for September-October shipment have increased by €5/mt week on week, standing at €565-570/mt CFR and €570-580/mt CFR on average, respectively. Offer attempts above the upper end of the range have also been reported for both products, but such levels do not seem workable under current market conditions.
€1 = $1.16
Author: SteelOrbis Editorial Team
Europe’s automotive sector faces growing Chinese competition: Gestamp
Europe risks losing its automotive industry, says Gestamp’s executive director Francisco Riberas. The head of the Spanish auto component supplier indicates European production remains 20-25% below its 2017 peak, whilst Chinese car manufacturers have gained market share through lower costs and more advanced EV technology.
“Europe’s wealth won’t last unless it can salvage its auto industry and establish a beneficial relationship with Chinese carmakers opening factories in the region,” he explains in an interview with the Financial Times, monitored by Kallanish. “The European car industry faced an existential crisis, having been asleep while China stole a march in electric vehicles and the US threw up import barriers against Chinese cars. So, losing the automotive industry could mean losing industry itself in Europe, and that would have far-reaching consequences.”
Riberas supports Chinese investment in Europe but argues that Asian manufacturers should increasingly source components locally rather than importing them. Otherwise, Europe risks becoming more than an assembly base.
“Who makes the cars isn’t the most important thing. What’s important is that they’re made here and create jobs here,” Gestamp’s ceo says. He emphasises that each job in a European vehicle plant typically supports three jobs in European component manufacturing.
The ceo also said that European manufacturers face less favourable financing conditions than their Chinese competitors.
“While the European auto sector is not considered attractive to the financial world, Asian companies have access to abundant funding that means they are often investing with a zero cost of capital in effect,” he points out.
Riberas supports the EU’s proposed Industrial Acceleration Act, including local-content requirement, but says the automotive sector also needs broader support through investment, technology, digitalisation and artificial intelligence.
“It’s not just about taking a protectionist approach. With each passing day, more companies are going under, and once that industrial base is lost, it won’t come back,” Riberas tells FT.


Italian plate prices tick up on improved demand
Italian heavy plate prices are gradually ticking up after declining in July on weak demand and subdued activity, Kallanish hears.
Mill sources report a price recovery and a decent level of sales despite the August break, with central Europe driving demand in recent weeks. Shipment levels have been good and order books are well filled, following a period of relative stagnation at the start of the third quarter.
Import restrictions are removing a significant volume of cheaper material that had been disrupting the market before the new quota regime came into force. Customers are now returning to European suppliers.
Meanwhile, production costs remain elevated, driven by rising energy and slab prices. Slab prices are stable month-on-month at $560-570/tonne cfr depending on quality and volumes.
Italian plate producers are quoting October lead times. Two sources say that while demand is not surging and business is done on a day-to-day basis, they are moderately optimistic about the outlook, and the lower end of the July price range is no longer available.
Values have increased some €30/t since July. Current prices for S275 plate are at €740/t (863.6/t)/t ex-works, while S355 is fetching a premium of about €20/t.
European manufacturers warn of industrial exodus over regulatory gaps
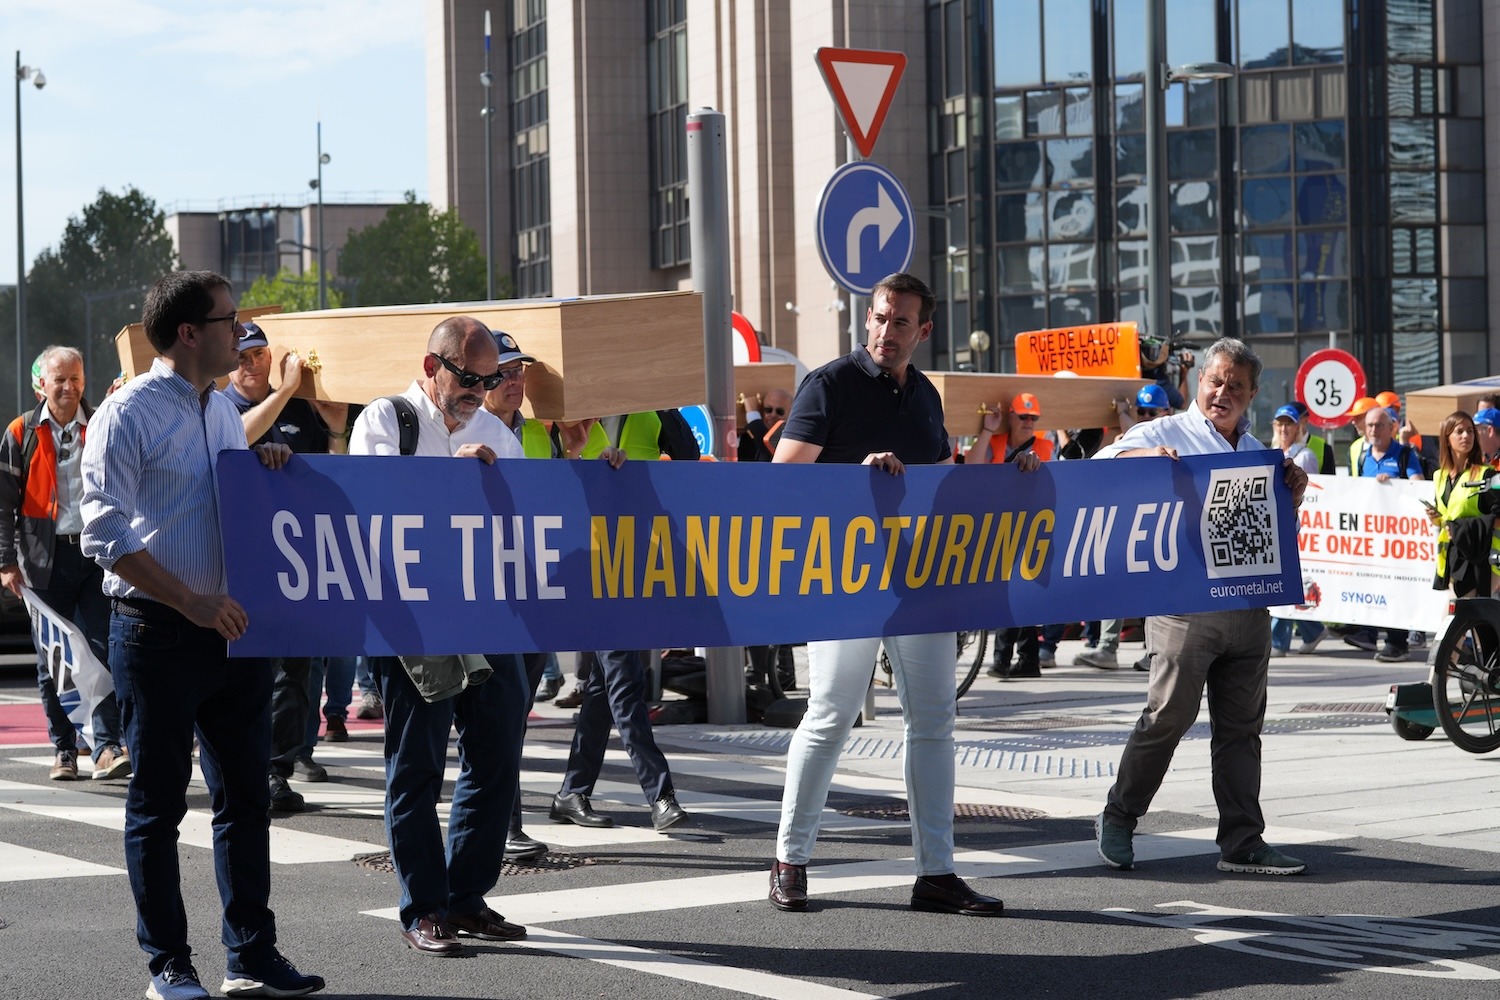
European manufacturers staged a dramatic protest in Brussels Sept. 7, carrying symbolic coffins around the European Commission’s headquarters, to warn that the continent risks losing critical industrial capacity unless policymakers close regulatory gaps that give cheaper, foreign-made goods an unfair advantage over domestically produced alternatives.
The European Convoy for Industrial Competitiveness, which brought together companies, workers, business associations and industrial stakeholders from across Europe, delivered what organizers called a “wake-up call” for EU policymakers.
The protesters highlighted a structural tension at the heart of EU industrial policy that has direct implications for commodity trade flows: while primary finished steel products such as hot-rolled coils, rebars and sections, are shielded from imports thanks to the new trade defense measures and the Carbon Border Adjustment Mechanism (CBAM), finished and semi-finished products manufactured from steel outside the EU are not and they can enter into the European market without facing equivalent obligations.
Steel-intensive finished products made outside the EU are not subject to the same carbon or trade requirements as those manufactured within the bloc. This disparity means European manufacturers bear higher production costs than competitors who import finished goods, a dynamic that is accelerating decisions to relocate production outside Europe and threatening what organizers describe as investment, industrial know-how, value creation and quality jobs.

EUROMETAL, the European associations of steel traders, service centers and overall main end users, said the convoy “does not call for protectionism” but for “fair competition,” arguing that extending appropriate trade and carbon measures to relevant steel derivatives and manufactured components would help establish “a genuine level playing field across the entire manufacturing value chain.”
The timing of the protest is significant. The EU’s CBAM, which entered its transitional phase in October 2023 and is due to become fully operational, currently covers direct imports of carbon-intensive materials, including steel, cement, aluminum, fertilizers and electricity. However, critics argue the mechanism does not adequately capture the carbon embedded in downstream manufactured goods that use these materials as inputs — a gap that EUROMETAL and its allies say distorts competition at the finished-product level.
If European manufacturers continue to face structurally higher input and compliance costs relative to non-EU producers of finished goods, demand for domestically produced steel and other industrial inputs could weaken over time as manufacturing activity migrates. That shift would have knock-on effects for European steel consumption, scrap flows and energy demand from heavy industry — all of which feed into refined products and industrial fuel markets across the region.
The EU’s new steel trade measure for primary finished steel products went into force July 1, with the commission presenting it as the first step toward regaining 34 million metric tons of steel production and capacity utilization lost since 2019.
Crude steel production fell 2.9% in 2025 to its lowest level on record, coming in almost 60 million mt below pre-2008 financial crisis levels, data from the European steel association, Eurofer, showed. Apparent steel consumption grew by 4.4% in 2025 in the EU, ending a prolonged downturn, although volumes remained well below pre-crisis levels. Last year, before the new measures were implemented, imports of semi-finished and finished steel products rose 14% year over year, reaching a record share of around 30% of EU steel consumption.
Author: Annalisa Villa
Europe’s largest commercial carbon capture and storage project begins operations


Merz calls on Commission to strengthen EU trade defence tools
At a joint 9 September press conference with European Council President António Costa, German Chancellor Friedrich Merz called for stronger EU trade defence tools, signalling a tougher stance from Berlin.
“We are seeing increasingly unfair trade practices,” Merz said, implicitly referring to China.
“We are in favour of free trade, but we’re anything but naive,” he added.
EU leaders had in June tasked the Commission with strengthening dialogue with Beijing while also reinforcing the EU’s existing trade defence toolbox — under which tariffs can be deployed to protect Europe from unfair foreign competition.
New instruments are needed “to effectively defend [the bloc’s] interests”, Merz said.
He said he expected “intensive negotiations” on the issue with Commission President Ursula von der Leyen at the 15–16 October European Council.
Germany is due to present proposals to tackle unfair trade practices ahead of then.
