


Denecke-Arnold becomes chairwoman of Salzgitter Flachstahl
Heike Denecke-Arnoldhas has been appointed as the new chair of the management board of Salzgitter Flachstahl, the strip-making unit of Salzgitter AG, Kallanish learns from the group.
She will assume the position in January, succeeding Ulrich Grethe, who will leave the company to enter retirement.
Heike Denecke-Arnold has many years of leadership and management experience in the steel industry and holds extensive expertise in the fields of sales, production, quality, and logistics, Salzgitter notes. She studied metallurgy and materials engineering at RWTH Aachen University where she completed her Ph.D.
“We are currently engaged in transitioning to low-carbon production processes. With her extensive know-how, Dr. Denecke-Arnold will integrate and drive forward the further implementation of SALCOS (Salzgitter Low CO2 Steelmaking),” says Gunnar Groebler, chief executive of Salzgitter AG. On the departure of Ulrich Grethe, he says that “his journey from trainee to chairman is a testament to what can be achieved with verve, expertise and personal integrity.”
SALCOS will also be Salzgitter’s key theme at the Euroblech trade fair in Hanover this week. At the stand of the group, a hydrogen model will provide visitors with a comprehensive overview of the individual components and progress of the transformation programme.
The group will be represented by all units concerned with coil/strip and plate. These are Salzgitter Flachstahl, Salzgitter Mannesmann Stahlservice, Ilsenburger Grobblech, Salzgitter Automotive Engineering, Salzgitter Mannesmann Handel, Salzgitter Mannesmann Stahlhandel, Salzgitter Mannesmann International, Universal Eisen und Stahl.
Christian Koehl Germany


Italian demand could improve amid coil uptick: Assofermet
Demand could improve in the coming weeks, driven by the recent uptick in coil prices, despite the expectation that consumption will not recover until early 2025, Italian trade association Assofermet says in a market note seen by Kallanish.
The market may have been shaken in the early days of October when ArcelorMittal announced a sharp increase in the price of coils. Although it is still too soon to predict a response, the cautiously optimistic stimulus announcement from the Chinese government indicates that the long-awaited price increases may not be far off, the association believes.
However, the note says that “the persistent weakness in demand is leading to challenges for service centres, which are struggling to manage volumes that are considerably below their production capacity.”
It continues that the significant import pressure experienced in recent months in Europe from steel producers in the Far East has been mitigated by the stringent restrictions of the safeguard quotas and a new anti-dumping investigation.
“Indeed, numerous [import] negotiations remained unresolved primarily due to concerns over the potential obligation to pay costly duties,” it adds.
Distributors and service centres report price stability for long products and all coil derivatives.
October started amid the heightened tensions of the conflict in the Middle East, coupled with concerning projections from major European automotive manufacturers, including Volkswagen group and Stellantis.
These developments suggest “a less than favourable outlook for our sector in the immediate future,” Assofermet says.
The prevailing sentiment of uncertainty, absence of a long-term strategy, and a wait-and-see attitude are likely to persist in the upcoming quarter, the association forecasts.
Earlier this month, Assofermet expressed concern regarding potential EU anti-dumping duties on hot rolled coil from Japan, Vietnam, Egypt and India, which could result in a material shortage on the domestic market.
Paolo Sangoi, president of Assofermet’s distribution segment, told Kallanish in a previous interview that a shortage may occur, potentially resembling the events of 2021 and 2022, if demand increases and consumption improves.
Natalia Capra France

Large projects to support UK steel demand
Improving UK steel demand in 2025 is likely to be supported by new construction projects as interest rates start to trend lower, market participants said at last week’s joint NEASS & ISTA meeting attended by Kallanish.
“I think 2025 will be slightly better than 2024, but I don’t think it’s going to be what we want or need,” said Tom McDougall, commercial director at All Steels Trading. “I think we’re waiting for 2026 before the cost of finance comes down and there are some bigger projects looking to take shape – data centres, infrastructure projects.”
He noted for the recently announced price increase by ArcelorMittal to be successful, certain factors would have to happen, aside from increased demand, which remained lacking.
“The influence that will potentially have some impact is the British Steel situation; they are potentially looking at shutting the blast furnace down and introducing importing slabs and billets for the re-rolling production. We believe there’s a shortage in stocks, and part of the reason for that, to some extent, is the British Steel situation,” he noted. He added the firm is “usually able to infill off stock levels [from their own warehouses].”
“From an outside perspective, it appears their warehouse space is being used up for rail stock … They [may] think there will be a transitional period between getting the re-rolling lines up to speed and shutting the blast furnace, and therefore might need some contingency stock in place on the rail,” McDougall continued.
He is currently seeing holes in stock levels for some long products, especially sections.
Mike Astbury, head of UK sales at ArcelorMittal Distribution, also noted a current lack of product availability from British Steel.
“There is a big question mark with regards to the future of British Steel, what will happen either way and what kind of timescale will there be for any transition,” he added.
He also foresees 2025 being an improvement on 2024, which he said has been “worse than anticipated”.
“There are several significant projects which have got the go ahead. London seems to be coming back to the market,” he continued. “Data centres are now going to be the bedrock and saviour for sections for the next 2-3 years,” he said, adding that Amazon was also building significantly sized distribution centres.
Rob Ridge, strategic business development director at Barrett Steel, additionally saw that there were some reasonably sized projects.
“Going into 2025 we are seeing some very large projects coming through … It’s a step in the right direction; cash is now being released to fund these large projects,” he said.
Julian Thompson, managing director at Salzgitter Mannesmann UK, concurred on more positivity for 2025, amid a return of London high rise projects, and new data centres. However, he also had concerns over the future of British Steel.
“The British Steel question marks hangs over everybody, and that could be quite significant for next year’s demand,” he said. “If there’s more trouble to their production and it gets worse, then there will be more imports required.”
Sentiment was mixed during the meeting, with other participants noting some projects were more than a year away and were not seeing the funds being released. Falling interest rates would take time to filter through during 2025 and would not return to the very low levels previously seen.
The demand picture remains unclear, with many customers not in a hurry to buy, limiting growth, while others saw demand stabilising across the various steel product groups.
Approached by Kallanish on Friday for comment about the blast furnace shutdown reports, British Steel said: “We are in ongoing discussions with the government about our decarbonisation plans and the future operations of our UK business. While progress continues, no final decisions have been made.”
Carrie Bone UK
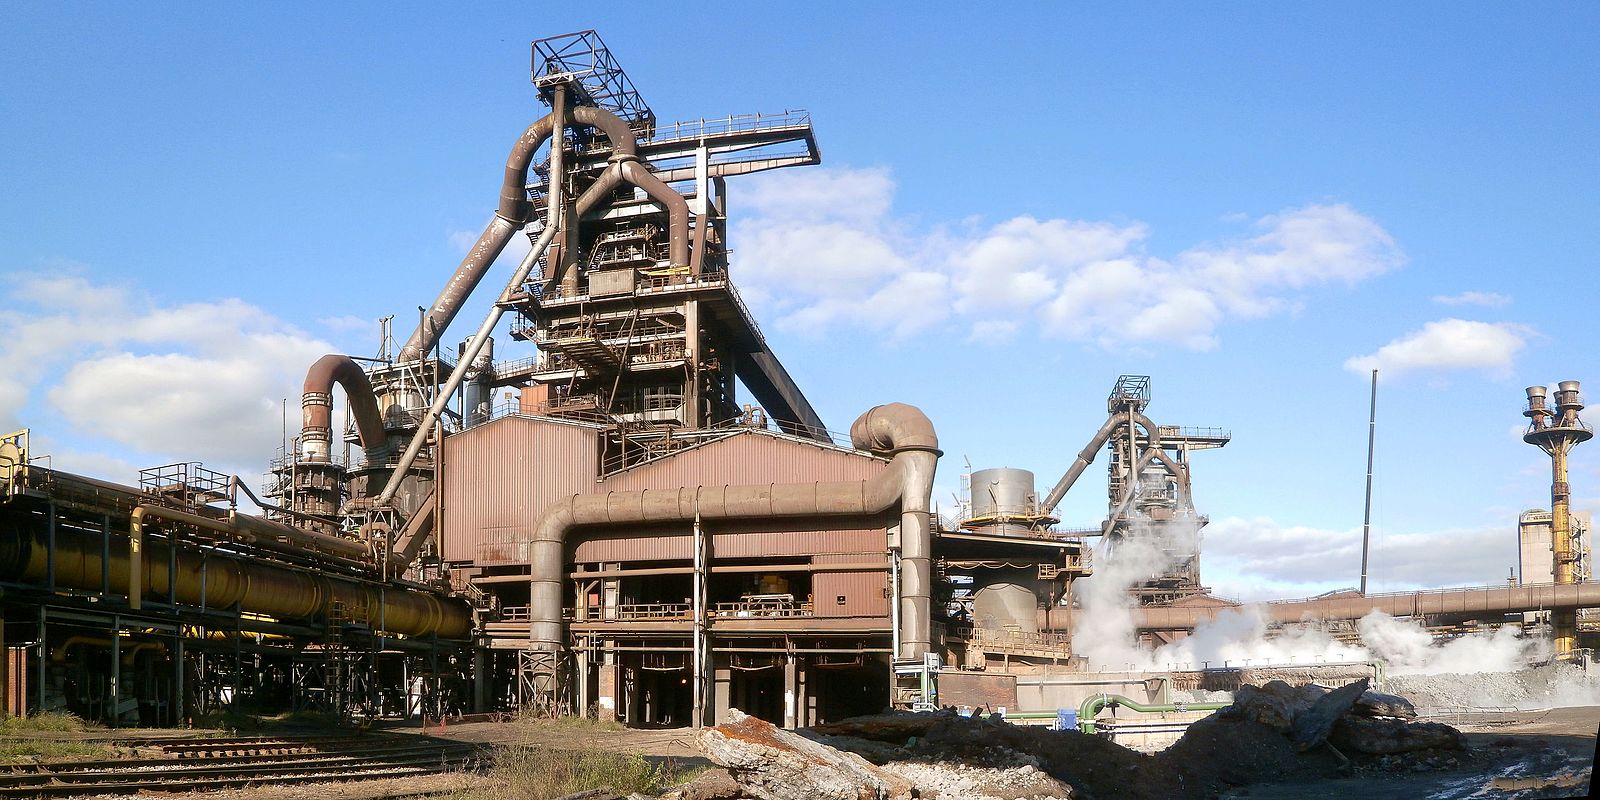
ArcelorMittal idles Gijón steelworks, wire rod plant
ArcelorMittal has temporarily halted part of its long steel production in northern Spain, the company tells Kallanish. The situation is a consequence of weak demand and the struggle to compete with low-priced imports.
ArcelorMittal decided on Friday to halt the Gijón steelworks and wire rod plant until 27 October.
“Wire rod is one of the products that is being most affected by the enormous volume of imports from outside Europe,” the company’s spokesperson explains. The wire rod plant has had to stop several times this year due to the worsening market situation.
The stoppage of the steelworks and wire rod plant is expected to affect more than 400 workers.
ArcelorMittal, however, indicates that the temporary lay-off plan will not affect all employees, as many of them will be offered holidays or undergo medical examinations.
Todor Kirkov Bulgaria

European HRC prices stable amid limited activity
Most Northern European consumers refrained from buying finished steel on Monday, in anticipation of greater clarity on the direction of HRC prices after the EuroBLECH international sheet metal exhibition, taking place in Hanover, Germany on October 22-25.
Some sources told Fastmarkets they expect HRC prices to stabilize during the event and that an uptrend would be seen after the fair.
But some buyers were more skeptical and predicted that prices might even fall after the fair due to the persistently slow demand in the region.
At the beginning of October, ArcelorMittal announced a €40 ($43) per tonne increase to its European offer prices for HRC – a move that was later followed by other European steel producers.
In Northern Europe, HRC was on offer at €580-590 per tonne ex-works, sources said, with offers for the first-quarter of 2025 of up to €600 per tonne ex-works.
Some mills in the region, meanwhile, were still struggling to sell November-delivery material and sources said that some offers from before ArcelorMittal’s price hikes were also still available.
Fastmarkets heard some deals reported at €530-550 per tonne ex-works.
Buyers, meanwhile, estimated the workable price for November/December-delivery HRC in Northern Europe at €540-560 per tonne ex-works.
Fastmarkets calculated its daily steel HRC index, domestic, exw Northern Europe, at €553.13 per tonne on Monday, unchanged from October 18.
The index was up by €3.75 per tonne week on week, but down by €3.33 per tonne month on month.
In Southern Europe, Fastmarkets’ daily steel HRC index, domestic, exw Italy, was calculated at €551.25 per tonne on Monday, also unchanged from Friday.
The Italian index was up by €6.25 per tonne week on week, but down by €6.25 per tonne month on month.
One local supplier was heard offering HRC at €580 per tonne delivered, which would net back to €570 per tonne ex-works.
According to a buyer source, a discount of €15-20 per tonne from that price was possible.
Others told Fastmarkets that while the supplier was not leaving much room for negotiations and was insisting on the advertized price, buyers estimated the workable level at €540-555 per tonne ex-works.
Import offers remained uncompetitive compared with local prices, meanwhile, and Fastmarkets understands that most consumers currently prefer to buy material from the domestic market.


Artrom Steel Tubes modernizes furnace to reduce energy consumption
Romanian pipemaker Artrom Steel Tubes has successfully modernized its rotary hearth furnace to reduce energy consumption and emissions.
The upgraded furnace uses advanced burner technology to lower natural gas and CO2 emissions by 45%.
This project is part of the company’s broader initiative to become more sustainable and competitive in the market for seamless steel pipes.

Slow Italian longs consumption prompts stoppages in November
September presented significant challenges for long product sales in Italy while insights from sellers and buyers indicate that October is unlikely to show any improvement, sources tell Kallanish.
Prices appear stable on a month-to-month basis, with minor fluctuations of €10/tonne ($10.84/t).
The Italian merchant bar sector is currently experiencing major difficulties due to sluggish order volumes. Prices remain largely stable as the primary producers have successfully maintained their position against falling bids.
Extended production reductions in the segment are anticipated in November to align demand with supply. Some producers are stopping for three weeks while other longs mills will take advantage of the 1 November public holiday to cut production for 1-2 weeks and implement temporary layoffs.
“There is no work downstream,” an agent comments. “Customers are not even in a wating mood. They just call us when they need material and do not even negotiate prices. They buy what is necessary for the next two weeks to match their low orders”.
The market outlook suggests that difficulties will persist through year end, with sources expressing scepticism regarding the potential for price increases in this weak environment.
“In September and October, the market seems frozen; we have been suffering on merchant bar but have gathered a few more orders for sections,” another agent says.
The better demand for sections is attributed to the current low availability as the main producer is said to be late with deliveries, according to sources. Beams supply is forecast to remain extremely limited. According to sources, prices for the first category are at around €800/t delivered. The current range for domestic merchant bar is at €280-290/t delivered or €700-710/t delivered, including size extras.
ArcelorMittal has recently announced it is to increase its prices for long products throughout Europe. The decision was driven by the present unsustainability of prices and the increasing costs of raw materials globally.
According to sources, the steelmaker is increasing prices of all commodity grade longs, including rebar, beams, and drawing quality wire rod, by €40/t.
Natalia Capra France

Consumers want green steel, state aid inevitable: Arnaud Guerendel
Given the vast cost involved, state aid is inevitable for steelmakers to be able to transition to low-emission steelmaking, while the majority of consumers have shown a willingness to pay a premium for green steel, says Vulcan Green Steel vice president of sales Arnaud Guerendel.
“Steelmakers’ limited financial sources make it questionable to transition current carbon emissions to zero, as the capex is $1 billion needed for every million tonne of steel capacity for hydrogen-based DRI and EAF route production transformed from blast furnaces,” Guerendel said during Kallanish Flat Steel 2024 in Istanbul last week. “Government aid is unavoidable.”
Some 30-35% of steel applications will be sustainable in Europe by 2035, equating to 25-35 million tonnes/year of low-CO2-emission flat products demand.
Citing a BCG survey of consumers in a few major countries, Guerendel said 57% of consumers care about net zero carbon emissions and consider this when making their next purchases of food packaging, DIY, household, and other consumer goods. When it comes to buying cars, the willingness of consumers to pay a premium for zero carbon emissions varies between 84% and 88%, depending on the type of engine (combustion engine and EV). For white goods, this willingness is at 94%.
The sensitivity and goodwill of buyers is being exploited, however. A study in Europe found that 42% of green claims were exaggerated, false or misleading, suggesting greenwashing on an industrial scale.
Scrap shortages are meanwhile also inevitable, Guerendel observed. In the best case scenario, the recyclability ratio even for the most advanced circulation system will reach only 30%. Whatever scrap trade restrictions are chosen therefore, these will not prevent a shortage.

Demand for green direct reduced iron will therefore be the primary beneficiary. DRI’s share of total metallics demand is projected to rise from the current 6% to 13% by 2050, with production expected to grow nearly five times faster than total metallics demand, reaching 320mt.
It is anticipated that by 2050, almost half of all DRI produced will be hydrogen-based. As new processing hubs emerge, it is expected that by 2050, approximately 25% of DRI supply will be traded, compared with just 7% at present. DRI exports from the Middle East are expected to reach 35-40mt, Guerendel concluded.
Burak Odabasi Turkey

Market unlikely to recover before H2 2025
Panelists at Kallanish Flat Steel 2024 in Istanbul expressed mostly a bearish outlook for the market until at least the second half of next year.
Tayfun İşeri, chairman of Turkey’s Flat Steel Product Exporters, Importers and Manufacturers Association (YİSAD), emphasised he is an optimist but is pessimistic about the market outlook for the first time.
The steel industry has been “hectic” for the past two years, he noted at last week’s event. Global trade has regionalised and the WTO has lost its respect. The Russia-Ukraine war, the Turkey earthquake and the Palestine-Israel conflict, as well as high interest rates and inflation have impacted steel demand and will continue to do so. Chinese exports, which will exceed 100 million tonnes before the end of 2024, pose a threat to steel prices and production in 2025, İşeri noted.

Selçuk Yılmaz, speaking at his first conference since becoming Yıldız Demir Çelik general manager last month, said Turkey’s imposition of a 6.1-43.31% dumping duty on HRC imports from India, China, Japan and Russia has already impacted domestic HRC pricing. Next year, there may be an anti dumping investigation into galvanizing, cold rolled and pre-painted steel imports in Turkey, he added. Operating profits are decreasing amid high energy costs, while production capacities are rising.
Kallanish Asia editor Tomas Gutierrez stated that Chinese steel demand will fall consistently in the foreseeable future, meaning China will need to export its surplus. Noting that overall fundamentals are weak and the recently announced stimulus packages are insufficient to support the steel industry, Gutierrez pointed out that economic confidence is required to trigger a demand recovery.
Stemcor managing director Dick Sands said construction has been hit by high interest rates, while global sentiment is very negative today. “The only thing that can move mountains is sentiment. We need positive sentiment,” he affirmed. Although wars are having a negative impact on steel demand at present, once they end, this will boost demand.
Trade cases are likely to increase on Chinese material, Sands continued, adding that he is no longer confident China can manage its economy.

GMK Center chief executive Stanislav Zinchenko stated that although he expected 1.4% annual growth next year, which would be good for the European economy, European steel demand is unlikely to improve in the next six months. The market is currently at the bottom of the demand cycle, with demand to return by 2026-2028.
The Indian market has been stagnant for almost a year. “We failed to see the expected infrastructure investment projects after the [Indian] election. The biggest challenge for India is exports which decreased by 50% in the nine months this year, while imports grew 60% … India should decide about protection measures to compensate for export losses and stimulate its local market,” Zinchenko concluded.

EU HRC prices largely stable ahead of Euroblech conference
Market activity remains subdued as most participants are expected to attend the Euroblech steel conference in Hanover, Germany. A Germany-based service center source confirmed that “there will not be much substantial business taking place this week.”
Pessimistic economic forecasts for the German and Austrian economies contributed to ongoing weak real demand in the European steel market. A Germany-based service center source rumored that “some European mills will try to cut production and cut some blast furnaces.” However, this remains to be seen.
Platts assessed Northwest European HRC at Eur555/mt ex-works Ruhr Oct. 21, stable on the day.
An offer was reported at Eur560-570/mt ex-works Ruhr. Tradable values were reported at Eur545-570/mt ex-works Ruhr.
Platts assessed domestic HRC in Southern Europe at Eur545/mt ex-works Italy, stable on the day.
Offers were reported at Eur560-600/mt ex-works Italy.
Platts assessed imported HRC in Northwest Europe at Eur520/mt CIF Antwerp, stable on the day.
Platts assessed imported HRC in Southern Europe at Eur535/mt CIF Italy, stable on the day.
Platts is part of S&P Global Commodity Insights.
