


Italian coil market stagnates, prices decline
The hot rolled coil market in southern Europe is currently experiencing significant stagnation. Overall order levels in both Europe’s import and domestic HRC markets are notably subdued.
“Steel consumption has decreased by approximately 20% this year, with certain end-user sectors experiencing more significant declines than others, particularly agriculture and automotive,” a service centre in Italy tells Kallanish. Coil derivatives, including tube and sheet, are going through a substantial drop in sales accompanied by decreasing prices.
European mills are seeing an overall decrease in orders and are operating with reduced lead times. “The complete value chain is experiencing a crisis and facing margin pressure. The current prices and market dynamics are no longer sustainable,” notes another coil buyer in Italy.
Import prices for HRC from Asia into Italy have significantly decreased since August, and there is a lack of purchasing interest. Asian suppliers are offering at €530-550/tonne ($589-611) cfr in Italy, but European and Italian steelmakers have lowered their asking prices to match import offers, making local purchasing more alluring.
Inventory levels in Italy remain relatively high, suggesting no immediate necessity for HRC procurement. Most buyers are going to wait and watch rather than make a purchase.
Countries that have exhausted their EU quotas have been replaced by alternative suppliers like Turkey, which has provided competitive offers. Currently, prices for service centre quality HRC in Italy are at approximately €550/t base delivered, or around €530/t base ex-works.
Market participants expect further price reductions in the upcoming weeks. In July, prior to the August summer break in several EU countries, HRC prices in Europe were reported at €615-620/t base ex-works.
Natalia Capra France


CBAM is step forward but not enough to rebalance global markets, European IREPAS conference attendees say
CBAM, a carbon tariff for all carbon-intensive products imported into the European Union, was passed by the European Commission in December 2022 and its transitional phase began in October 2023.
Starting in October 2023, buyers of goods originating outside the EU must purchase certificates which equal the total emissions in the production of the goods.
There is no limit to the number of certificates that can be purchased to avoid restricting trade.
The cost of these certificates are calculated by the European Commission on a weekly basis according to the average price of the closing EU Emission Trading System (ETS) carbon dioxide (CO2) allowances for each week.
Impact of CBAM
CBAM can help to address imbalances related to European companies who are constrained by carbon taxes attempting to compete with countries who are not subject to any regulatory strictures, Louis Redshaw, Founder of Redshaw Advisors, told IREPAS attendees.
CBAM will help reduce carbon leakage, Redshaw said.
Carbon leakage was described when, for reasons of costs related to climate policies, businesses were to transfer production to other countries with more relaxed emission constraints, in turn resulting in an increase in their total emissions.
By placing a fair price on the carbon emitted during the production of all carbon-intensive products entering Europe, European mills, who currently need to pay for carbon credits equivalent to their carbon emissions, will be on a more equitable basis with importing countries who do not currently have the same taxes in place.
Some European market participants, however, were skeptical about how effective CBAM would be in rebalancing the playing field.
Carbon credits
European companies must buy carbon credits, normally from the government, to produce steel. When a company buys a carbon credit they can generate one ton of CO2 emissions.
The development of carbon credits turned carbon dioxide into a commodity, which could be monetized like any commodity.
Currently, the top 10% of the lowest emitting steel producers in Europe do not pay for carbon credits, while the remaining 90% of European steel producers have to pay varying amounts for carbon credits to offset their carbon emissions.
Pre-CBAM, European domestic mills were burdened by the cost of climate policies which non-EU countries were not, making them uncompetitive.
“CBAM will help to make competition fair. If importers are not taxed similarly to European mills, the European steel industry will die,” Redshaw said.
The greater a producer’s emission, the more they need to pay for carbon credits, thus incentivizing them to invest in decarbonizing processes.
By ensuring all countries importing steel into Europe have to pay similar amount, sustainable goals do not stop EU countries from being competitive or profitable.
Market responses
Many conference attendees felt that CBAM could help support European mills remain competitive when faced with so many economic challenges.
Some non-European exporters who were already providing CBAM certificates to buyers in Europe importing their stock, reported high levels of bureaucracy involved with submitting the correct information quarterly.
“It will help to put a fair price on the carbon emitted. Steel producers in Egypt who export to EU have already been asked to fill in necessary paperwork for CBAM. This is a very bureaucratic procedure and may become a burden in the future for producers,” a producer source from Egypt told Fastmarkets.
“CBAM will help support European mills and global targets towards becoming more sustainable,” a second producer source from Egypt said.
Skepticism
Some sources, especially in Europe, did not think CBAM would either encourage global decarbonization or significantly rebalance global markets.
CBAM has put a cost on carbon, but it is not enough to counter the other factors which have resulted in a lack of balance in the global markets, these sources said.
These factors included foreign country subsidies, lower gas and electricity costs, lower labor costs and lower or no regulations in the construction sector, the sources added.
These more skeptical market participants felt that by just putting a price on ‘carbon’, other key areas which required addressing were not being considered.
“Europe has been affected and limited by its own desire to become carbon efficient and this has been a contributing factor to Europe losing market share of steel production, weakening domestic demand and becoming uncompetitive domestically,” a German trader said.
Europe is currently trying to decarbonize, digitize and remain profitable, sources said. But, at least in the short term, the goal of decarbonizing is at odds with the goal of profitability, Fastmarkets heard.
“European producers don’t just have to deal with the carbon issue, they also have to deal with high energy costs because of high taxation on energy and renewable energy transformation and high energy costs and importing expensive raw materials and finding the money to invest in decarbonizing technology,” a producer source from Spain said.
Whereas there is a lot of pressure from every side to transition to low-carbon environment in Europe, this is not the same in non-EU countries.
In other countries, for example China and Algeria, where the steel industry is buoyed up by subsidies, carbon tariffs like CBAM will not incentivize them to decarbonize.
“China will just pay the increased costs with the massive government subsidies they receive. They will continue to emit just as much carbon and will continue to have far lower costs,” a trader at the conference said during a panel discussion.
“Even with CBAM and all countries importing into Europe having to pay for the cost of their carbon footprint, they still remain more competitive because of cheaper energy costs and cheaper labor costs,” a second producer source from Europe said.

Seven key things Fastmarkets learned during Irepas Fall 2024 meeting
More than 490 delegates from around the world gathered in Paris on September 15-17 to network and to participate in this key event for long steel producers.
Here are the seven main topics that were discussed at the conference:
Chinese dominance
China’s dominance in the international steel market has strengthened over the past year amid a drop in domestic demand and insufficient production cuts, and it was highly likely to continue in 2025.
Yeoh Wee Jin, secretary general of the South East Asia Iron & Steel Institute (SEAISI), described this year’s events in China as “a third tsunami” during a panel at the Irepas event. He expected the country’s steel exports to exceed 100 million tonnes this year, compared with 89 million tonnes in 2023.
Fall in iron ore prices
The decrease in steel production in China resulted in a fall in iron ore prices, as well as the accumulation of a significant stock of iron ore. Wilhelm Alff, chairman of the Irepas traders’ committee, said that iron ore stocks at Chinese ports currently totaled 149 million tonnes.
Fastmarkets’ daily index for iron ore 62% Fe fines, cfr Qingdao, has averaged $91.87 per tonne so far in September, compared with an average of $135.03 per tonne in January this year.
Meanwhile, scrap collection in Europe and the US has slowed down, Jens Björkman, the chairman of the raw material suppliers’ committee, said. This helped to support prices for the product despite delayed demand in Turkey.
The Middle Eastern country has switched to purchases of Chinese steel billet since the summer, when prices for the material became low enough to make production of rebar from billet more attractive than from scrap.
Fastmarkets’ daily index for steel scrap, HMS 1&2 (80:20 mix), North Europe origin, cfr Turkey, has averaged $363.36 per tonne so far in September, compared with $414.12 per tonne in January 2024.
Consequently, iron ore prices fell by almost 32% in the period under consideration, while those for scrap fell by 12.23%, making the blast furnace steel production route more profitable.
“Everybody wants to be a blast furnace-based steel producer for the next six months,” Alff said.
Shift in Turkey
Chinese steel prices remained attractive, including those for billet, so it was highly likely that Turkey would continue to meet its needs through billet imports, which would result in lower steel output in the country.
This situation could also exert pressure on scrap prices.
Trade defense
Turkey itself was limited in its long steel export opportunities at the moment, considering the imposition of trade defense measures in the US and in Canada, the almost-complete take-up of import quotas in the EU for the third quarter of 2024, with tonnages already sold for delivery in the fourth quarter, and with recent restrictions on the supply of steel products to Israel.
Some countries that formerly procured long steel from Turkey – such as Egypt, Algeria and states in the Gulf region – have become exporters themselves, according to the chairman of the Irepas producers’ committee, Murat Cebecioglu.
Yemen, plus a few other countries in the Middle East, and Latin America were currently the key destinations for Turkish long steel exports, he added.
Regional differences
Looking at the EU, Cebecioglu said that business has seemed to be at a standstill in the region for more than a year, and little or no improvement was expected in the next six months or so, a point on which other delegates at the event agreed.
Gulf Co-operation Council (GCC) countries were currently in a slightly better position than those in other regions because their economies were moving in the right direction.
New projects in Saudi Arabia, for example, were creating demand in the region, with the construction and real estate sectors being the driving forces.
Yeoh said that ASEAN economies were also growing, albeit more slowly because of the generally unfavorable situation globally. He said that the construction sector was booming across the region, except in Thailand. Meanwhile, manufacturing was weakening, mainly due to soft external demand.
Earlier this year, he said that ASEAN steel demand was expected to reach 76.5 million tonnes in 2024, up from 73.5 million tonnes in 2023.
Overcapacity in Asia
Meanwhile, unsustainable overcapacity and de-greening were in prospect in Southeast Asia, with at least 104.4 million tonnes per year of new capacities expected to come onstream by 2030. These would push the region’s total capacity to 181.5 million tpy if they were all implemented, Yeoh said.
Around 83.6 million tpy of new capacity would be based on blast furnace-basic oxygen furnace technology, Yeoh said, while only 20.8 million tpy would be based on direct reduced iron (DRI) and electric-arc furnace (EAF) capacities, and this would lead to an “explosion” of greenhouse gas emissions by the region.
Decarbonization
At the same time, Europe’s imposition of its CBAM regulations and the global trend for decarbonization were other major topics at the Irepas event.
Since its start in October 2023, buyers of goods originating outside the EU must purchase certificates corresponding to the total volume of greenhouse gas emissions created by the production of the goods.
The costs of these certificates are calculated by the European Commission on a weekly basis, related to the average price of the closing EU Emission Trading System (ETS) carbon dioxide (CO2) allowance for each week.
By placing a fair price on the carbon emitted during the production of all carbon-intensive products entering Europe, European mills that currently must pay for carbon credits equivalent to their carbon emissions will be put on a more equitable basis with producers that operate in exporter countries that do not impose similar taxes.
Opinions were divided on the effects of the CBAM rules on the European market – and beyond it. Many delegates to the Irepas event felt that CBAM could help European mills to remain competitive when faced with economic challenges. Some sources, however, did not think that CBAM would either encourage global decarbonization or significantly rebalance global markets.
CBAM has put a cost on carbon, but it was not enough to counter the other factors which have resulted in a lack of balance in the global markets, these sources said.
These factors included foreign country subsidies, lower gas and electricity costs, lower labor costs, and fewer or no regulations in the construction sector, the sources added.
Global overcapacity was also expected to slow the decarbonization transition and to hamper innovation, Luciano Giua, economic and policy analyst at the Organisation for Economic Cooperation & Development (OECD), said during the event.
Published by: Vlada Novokreshchenova, India-Inés Levy


EU HRC market remains largely stable as buyers avoid bookings
Domestic prices for European hot-rolled coil remained largely stable on Sept. 20, as buying activity remained limited in the market due to low end-user demand.
“Buyers, such as service centers and distributors, are not in a great position to offload material,” an Italy-based mill source said. “Therefore, they are not in a great rush to buy. End-user demand is just not enough.”
“Pricing is not the problem,” a distributor source said. “Problem is low/no demand.”
Platts assessed Northwest European HRC stable on the day at Eur555/mt ex-works Ruhr on Sept. 20. Tradable values were reported at Eur550/mt EXW Ruhr from a buy-side source.
Platts assessed domestic HRC prices in Southern Europe also stable on the day at Eur555/mt EXW Italy, with tradable values reported at Eur540-580/mt EXW Italy.
Sources said that production overcapacity in Asia has made it difficult for European suppliers to compete with them. However, interest in imports still remained weak due to concerns around safeguard duties and anti-dumping investigations.
“Production overcapacity in Asia is making things difficult for EU suppliers,” a service center source said.
Platts assessed imported HRC in Northwest Europe at Eur540/mt CIF Antwerp, down Eur5 on the day.
Meanwhile, Platts assessed imported HRC in Southern Europe at Eur540/mt CIF Italy, up Eur5 on the day.


Steel customers show green premium willingness: McKinsey
Steel is leading the energy transition metals when it comes to consumer willingness to pay a green premium by 2030, according to a report by McKinsey & Company, seen by Kallanish.
The Global Materials Perspective 2024 reports that 42% of steel customers were ready to pay some extra premium to secure supply if green materials are in deficit by 2030, above that of aluminium (37%) and copper (20%) customers.
While 44% of steel customers were not ready to pay extra and would switch to a grey alternative, this remained a lower percentage than those in the aluminium (59%) and copper (60%) sectors.
Across all materials, less than 15% of customers indicate a willingness to pay premiums of around 10% for low-carbon materials. However, the research notes regulatory measures could change the outlook, such as the EU Emissions Trading System (EU ETS) and Carbon Border Adjustment Mechanism (CBAM), amid higher costs for carbon emissions.
It adds that the energy transition is changing the materials landscape by accelerating demand growth for materials that are utilised in low-carbon technology such as electric vehicles. A long-term shift is taking place in terms of the materials needed, increasing the importance of the metals and mining portfolio, while at the same time driving a reduction in the use of thermal coal in energy.
In response, companies might seek to either switch to sourcing low-carbon footprint materials or invest in innovative solutions to reduce process emissions.
Elsewhere, the report notes that in metals and mining, around 80% of revenues stem from just five materials, steel, thermal coal, copper, gold, and aluminium, accounting for $4 trillion.
Of this, thermal coal and steel account for approximately 60-70% of revenues, with production volumes more than 30 times higher than all other materials combined. Gold, copper, and aluminium make up another 15-20%.
However, despite the long-term shift in material choice, steel was one of the few materials that has a somewhat weaker growth expectation, with demand projections remaining strong until 2035. With the exception of steel and thermal coal, demand is expected to outpace absolute historical growth in the coming decade compared with the previous decade for all the other energy transition materials in the report, including lithium and nickel.
In 2023, total production emissions from the metals and mining industry accounted for approximately 15% of global emissions. Assuming no external shifts, the share is estimated to decrease to approximately 13% by 2035.
This decrease in emissions is driven by the net effect of several factors, according to the report. This includes changes in production of thermal coal, a 50% decarbonisation of the global power grid, as the share of renewable energy increases, improved circularity as more recycled material is collected and utilised, efficiency improvements, and assets transitioning to net zero production.
Steel was also looking at a more “modest” decrease in emissions from in a “business as usual” perspective over the coming years than other materials. However, the research notes for the sector, approximately 40 million tonnes capacity of such transitions have already been announced by 2035, which would lower global emissions by as much as 60mt of CO2.
Elsewhere, the report notes that despite a turbulent environment, finances were healthy until 2023 – yet 2024 has a gloomier outlook. The past two to three years have posed some challenges for the materials industry, with high price volatility driven by increased supply chain disruptions and volatility in energy prices, among other factors. While the industry has experienced previous cycles of boom and bust, these recent fluctuations are unprecedented in scale.
Despite the challenges, the materials industry has shown strong financial results over the past few years when compared with historical averages, with revenue growing by 6% per annum since 2000. Revenues grew by approximately $2.4 trillion (more than 40%) from 2020 to 2023, primarily driven by metals and mining, which grew by $1.7 trillion (an increase of approximately 75%). During the same period, Ebitda in metals and mining nearly doubled, increasing from $500 billion to $900 billion.
Overall, balance sheets are healthy, with net debt over Ebitda ratios of 1.3 times – well below the through-cycle average of 1.8 times – providing companies with more investment capacity.
It notes, however, that 2024 is projected to be a more challenging year for the industry as overall economic growth slows and the shift toward low-carbon technologies unfolds more slowly than expected. These factors are putting downward pressure on price levels, especially for battery materials.
Carrie Bone UK

Voestalpine steel division discontinues fabrication activity
The steel division of voestalpine group will withdraw from the business of cam units and sliding elements, Kallanish hears from the Austrian company.
It will gradually discontinue the business activities of its company voestalpine Camtec GmbH in Linz by the end of the business year through March 2026. In the last business year, the unit’s revenue came to €12 million ($13.4m).
Voestalpine Camtec specialises in the production of cams and maintenance-free sliding elements made of brass, copper, and aluminium. It primarily supplies automotive manufacturers and suppliers, as well as the mechanical engineering industries. Despite market leadership in the German-speaking region and a recent improvement in capacity utilisation, production at the Linz site is no longer economically viable, voestalpine says.
Due to increased costs for energy and labour, along with the simultaneous massive increase in price pressure from non-European competitors, primarily from China and India, the activity is no longer competitive. The unit also suffers from weak demand from the European machinery and toolmaking sectors. The 53 employees affected have the opportunity to transfer to other voestalpine business units in Linz, voestalpine adds.
Christian Koehl Germany

Logistics, lower demand limit AMKR production, exports: ceo
ArcelorMittal Kryvyi Rih (AMKR) can export finished products only to nearby European countries due to high transportation costs, says company chief executive Mauro Longobardo.
“In the middle of this year, the enterprise was able to reach half of the pre-war level of metallurgical production and improve the situation with iron ore concentrate mining,” he said at a conference organised by the European Business Association. “However, in the second half of 2024, AMKR faced significant external and internal challenges that threaten maintaining production at the planned level, its growth and further development, and threaten the loss of competitiveness.”
“Logistics restrictions for Ukrainian industrial producers are just one of the external factors holding back the expansion of production at our plant,” he added.
Longobardo also mentioned the slowdown in iron ore consumption by China as one of these factors, which led to a decrease in world prices for iron ore and limited the sales volumes of the Kryvyi Rih enterprise.
“European and other manufacturers have a number of competitive advantages, in particular due to the lower cost of electricity in the cost price and cheaper logistics,” Longobardo noted. “For example, we are talking about Poland, Romania and the Baltics.”
“In addition, steel markets in Europe are currently stagnating. The reasons for this are geopolitical uncertainty in the region, high inflation, a slowdown at construction companies, and rising prices for energy and raw materials,” the ceo observed. “This creates an excess of ore and steel products, and a number of producers in Europe are mothballing production capacities and suspending production.”
In July, AMKR warned that it will be forced to significantly reduce production and send approximately 1,200 employees on idle time due to new government standards for importing electricity (see Kallanish passim). On 1 June, the Ukrainian government decided the guarantee of unlimited electricity supply will only apply to those enterprises that import at least 80% of their consumption.
AMKR increased production in May due to the restart of blast furnace No.6 and coke oven batteries No.3-4 in April (see Kallanish passim). The steelmaker hiked May crude steel production by 28% on-month and 68% on-year to 208,000 tonnes. Rolled steel production rose 27% on-month and 66% on-year to 193,000t.
In the first quarter, AMKR increased steel production by 93% on-year to 278,000t and pig iron output by 49.8% to 403,000t.
Svetoslav Abrossimov Bulgaria
Polish construction sector anticipates 2025 pickup
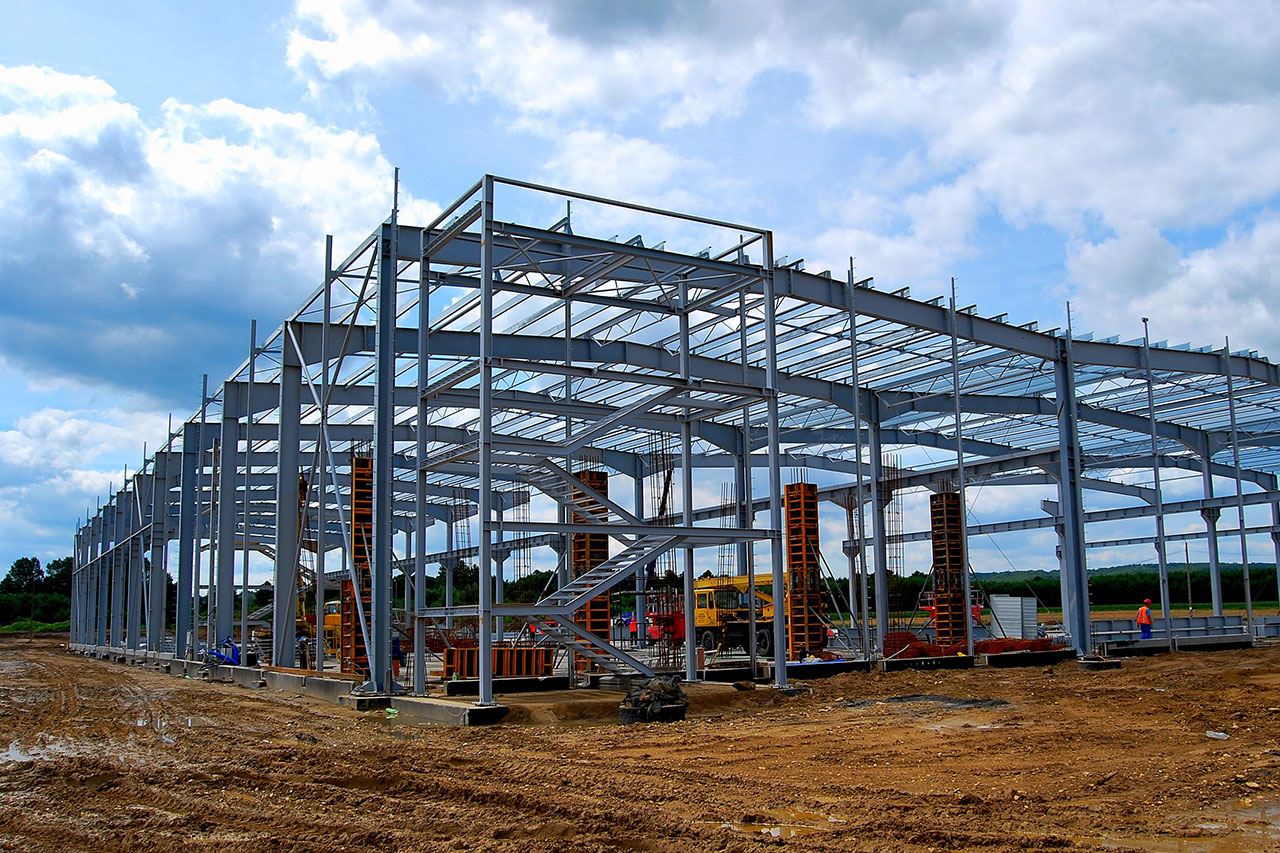
EU-funded National Recovery Fund (KPO) projects are set to spur construction sector investment in Poland from 2025, says one of Poland’s largest construction firms, Erbud. However, the shortage of qualified constriction workers could hamper the progress of these investments.
Besides this public investment, the government has announced the “Housing for a Start” programme that will subsidise people in a certain income bracket when paying rent. It is hoped this will spur private construction of more apartment buildings.
The first quarter saw slowing investment in Poland due to the reduced utilisation of EU infrastructure funds following the completion of the previous, 2014-2020 term, which resulted in lower infrastructure sector output. Q2 however saw on-year investment growth, most likely driven by defence spending, Erbud notes.
Polish construction companies are reporting a lack of new orders. There are three main factors hampering activity. The receipt of EU KPO funds has been delayed, while the new government is reviewing all infrastructure projects, which has led numerous investments to be suspended. Finally, many infrastructure projects have not yet been implemented because they are in the phase of prolonged negotiations, especially in the energy sector.
“Investment growth may be driven in the coming years by the need to increase labour productivity, as well as partial automation of processes in the face of rapidly increasing labour costs and the need to implement the energy transformation, which entails the need for high investment outlays to expand generation capacity,” the firm says in its latest earnings report seen by Kallanish.
The Polish government projects total investment into renewable energy up to 2040 of PLN 726.4 billion ($189.5 billion), of which PLN 261.8 billion will occur in 2023-2030 and PLN 464.5 billion in 2031-2040.
Adam Smith Poland

Acciaierie d’Italia sales process advances, new suitors reported
Acciaierie d’Italia (ADI) is advancing its sales process, as the special administration has commenced the review of letters of interest submitted by the deadline of 20 September. Adolfo Urso, Italy’s Minister of Enterprises and Made in Italy (MIMT), indicated to the local press last week there is significant interest from numerous international and national companies.
During the summer months, representatives from Steel Mont, Metinvest, Oman-based Vulcan Green Steel (VGS), and Canada’s Stelco engaged in discussions regarding the potential acquisition of ADI’s mills located in Genova, Novi Ligure, and Taranto, Kallanish notes.
Marcegaglia has recently expressed interest in joining the race. An informed source indicates the re-roller’s interest may be limited to specific segments of ADI’s assets, particularly the tube mills and the Novi Ligure facility, which is one of the re-rolling plants located in northern Italy.
Various companies are considering potential acquisitions of certain assets from the former Ilva, particularly in northern Italy, including the Italian service centres Eusider and Sideralba. According to people with knowledge of the dossier, Arvedi is also considering this, and Nippon Steel is reportedly also mulling joining the race.
Dividing the business and selling its various assets is a viable alternative. Two knowledgeable sources do not think there is a genuine desire to purchase the entire company and believe Metinvest is more likely to move forward with its plan to construct a flat steel mill in Piombino. Taranto is an outdated facility that requires significant capital investment and has an inflated workforce.
MIMT and ADI’s special commissioners invited expressions of interest in July for the acquisition of the struggling steelmaker’s assets. The aim of the sale is to swiftly and effectively reduce CO2 emissions and enhance steel production in Italy, by bringing about a change in management. The commissioners have asked potential buyers to preserve employment.
ADI’s suitors have now been asked to quote a potential price in their offers, Kallanish understands. The special commissioners intend to pursue the sale “preferably” by transferring the assets as a whole, the say. Alternatively, if the commissioners do not deem the offers concerning the business as a whole to be adequate, the transfer will be achieved through separate sale transactions of specific business units belonging to ADI (see Kallanish 2 August).
Natalia Capra France

From flats to longs: Europe’s ‘green’ steel conversation expands
When it comes to Europe’s nascent “green” steel sector, conversation for the most part has centered on flat products.
After all, flats — including hot-rolled coils and sheets –, account for the bulk of both the continent’s steel production and consumption, and the flats sector was the first to see premiums for material certified with a lower carbon profile than standard steel.
The annual combined European flat product deliveries and imports averaged around 82.96 million metric tons from 2013-2022, according to European steel producers association Eurofer. During the same period, the annual combined European long product deliveries and imports averaged about 49.58 million MMt.
Premiums emerged last year in Europe for carbon-accounted flat steel, and Platts, part of S&P Global Commodity Insights, addressed market demand for price assessments and data to help bring transparency to trade in such products — launching first-of-their-kind daily carbon-accounted HRC assessments in May 2023.
And now that the green conversation in Europe has extended to other markets, including long steel products used in construction, Platts has also expanded its carbon-accounted assessment offerings.
Carbon-accounted longs enter the picture
Effective Sept. 11, Platts launched new weekly spot price assessments for European carbon-accounted rebar and medium sections.
The new assessments — which Platts understands to be the first carbon-accounted assessments for long steel — include a European Rebar Carbon-Accounted Steel Premium (Rebar CASP), a European Medium Sections Carbon-Accounted Steel Premium (Medium Sections CASP), a Northwest Europe Rebar Carbon-Accounted Steel Price and a European Medium Sections Carbon-Accounted Steel Price.
Based on industry feedback, the European rebar and medium sections carbon-accounted steel premiums reflect any differential achieved for the spot sale of rebar and medium sections, with total accounted carbon emissions of 0.6 metric tons of CO2-equivalent, or less, for every metric ton of steel produced.
The assessments include emissions from direct, indirect and associated upstream and downstream activities, such as processing of steelmaking raw materials, hot metal production, steel rolling and associated transportation and logistics — typically referred to by market participants as scopes 1, 2 and 3.
Carbon emissions must be certified by an internationally accepted independent organization, and market participants will be expected to supply proof of such certification upon request.
Trade in steel products using offsets to reduce overall emissions profiles, such as carbon credits sourced from voluntary carbon markets, will not be considered for inclusion in the assessments. Platts will consider trade where a mass balancing approach has been applied and validated by a certified internationally accepted independent organization.
Platts assessed the Rebar CASP at Eur40/mt, Sept. 18, down from Eur70/mt Sept. 11 and the Medium Sections CASP at Eur65/mt, Sept. 18,down from Eur92.5/mt Sept. 11.

‘Historic, strategic turning point’
It is easy to see why the construction sector has entered the green conversation. Construction — which relies heavily on longs like rebar and medium sections for support — is not only the largest end-use sector for steel, but is also one with high associated carbon emissions.
Steel production generates 7%-9% of global CO2 emissions and about 5% of overall emissions in Europe, according to the Institutional Investors Group on Climate Change.
And regulatory requirements, such as the European Union’s Carbon Border Adjustment Mechanism scheme, as well as accelerated decarbonization efforts around the world, have underscored the need for heavy industries like steelmaking to move quickly to reduce carbon emissions.
In a Sept. 5 paper titled ‘Investor priorities for transitioning the European steel sector,’ the IIGCC said “the steel sector’s decarbonization is essential” and that “creating a supportive policy environment for the transition of high-emitting sectors is critical for achieving Europe’s commitment to climate neutrality by 2050.”
To stimulate low-carbon steel demand, the IIGCC said public steel procurement could be used as a tool to drive decarbonization innovation and incentivize use of low-carbon steel products. Financial incentives could include point-of-sale subsidies, tax exemptions, post-purchase rebates or tax credits, the IIGCC said.
Such investment would mirror investment made by European steelmakers offering carbon-accounted steel — mainly through conversion to electric-arc furnaces or implementing hydrogen and fossil-free fuel production. The steelmakers that have technology upgrades and innovative steelmaking investments will be essential not only for Europe’s own industry, which faces a “historic, strategic turning point,” but in the global steel industry’s decarbonization journey as well, IIGCC said.
“Investors see Europe as well positioned to lead the global transformation of the steel sector,” it said. “The EU is a large, highly developed economy with generally high-end steel production that can seize the opportunities and show what is possible, paving the way for other regions to follow.”
Several factors holding back green market activity
While the release of investment funds by the European Union and individual governments in the region have helped to kick off technical enhancements to reduce producer emissions, there are still several factors that are holding back trading activity of lower carbon emission products.
A hampering factor for the acceleration of carbon-accounted steel is the lack of an internationally adopted industry standard. Associations and trade groups such as the German steel federation and Responsible Steel have started to publish guidelines in the hope that they would become standards, but they’ve yet to gain widespread adoption.
A difficult economic environment seen in 2024 has meant that those who do not necessarily need to buy material with a lower carbon profile have opted for less expensive conventional steel – or have limited their spot market buying activity.
Rising interest rates and a near-recession in Germany hit medium-sized businesses — the so-called Mittelstand in Germany and the backbone of Europe’s biggest economy. German manufacturing remains weak, while the automotive industry also is struggling.
Demand and price development for carbon-accounted steel remains deeply correlated with the conventional steel market, and in times of weak steel demand for the market at large, carbon-accounted steel remains heavily affected.
Analysts at Commodity Insights do expect some near-term upside, with a steel price recovery from December 2025 due to restocking and restricted import supply.
Once restocking activities resume and economic tightness ease, trading activity is likely to resume to previous levels, market participants contend.
It then will be up to steelmakers in Europe and abroad to execute on the vision of Europe as a global leader in the energy transition.
Laura Varriale | Christopher Davis