


German stockholders recover during first half-year
Germany’s stockholding distributors saw a “strong first half-year” with regard to volume and especially prices, says their federation, BDS.
The tonnage sold by distributors from January through June totalled 5.61 million, Kallanish learns from BDS. This means a proportional increase over full-year 2020, in which sales came to 10.35mt, but also over 2019 when they totalled 10.78mt. A catch-up effect kicked in already towards the end of 2020, when the monthly average tonnage was 850,000t in the fourth quarter, over 9% higher than in Q4 2019.
A look at inventories suggests sales could have been even higher if supplies of steel had been. This applies especially to all strip products, says BDS head of research Jörg Feger.
On 31 December 2020, inventories stood at 1.92mt, already 5% lower than at the end of 2019. Levels rose only slightly at the beginning of this year, and then dropped in March and April, which is very unusual for spring months, Feger notes. A slight recovery in May was followed by another dip in June. On 30 June, inventories totalled 1.92mt, 10% lower than one year earlier.
This is also reflected in the days-of-sale, which in 2020 averaged at 75, somewhat lower than in 2019, and dropped further over the course of H1 2021. By June, they stood at 60.
Christian Koehl Germany


Stainless steel imports jump in Turkey as consumption rises
Turkey imported 411,600 mt of stainless steel coil with widths above 600 mm in the first eight months of the year, higher than the 335,000 mt imported in the same period the previous year, as stainless steel consumption in the country rose notably with the easing of the pandemic, S&P Global Platts observed from the latest monthly Turkish Statistical Institute (TUIK) data.
The cost of these imports also rose notably to $834 million in that period, 38% higher on year, due to globally higher steel pricing.
China notably raised its share in the Turkish stainless steel market with competitive prices in that period. The country became Turkey’s top stainless flat steel supplier in January-August by shipping 155,000 mt to Turkey, 72% higher on year, the TUIK data showed.
Turkey’s stainless sheet imports from South Korea remained relatively strong at 96,600 mt in January-August, down by 10,000 mt on year.
Turkey also imported 25,400 mt of stainless steel coil from Spain in the eight-month period, while imports from Italy totaled 22,500 mt.
Turkey’s imports of stainless flat steel from Taiwan totaled 18,300 mt in January-August, the latest data showed.
Turkey’s sole stainless cold-rolling mill, Posco Assan TST, based in Izmit, Kocaeli, near Istanbul, has production capacity of 300,000 mt/ear of 0.3-3.0 mm thick stainless cold-rolled coil up to 1,600 mm wide.
— Cenk Can

German steel pricing sentiment bearish, higher Q4 stocks seen
German steel producers, end-buyers, distributors and traders were found to be mostly bearish on pricing over October, according to a monthly survey of sentiment in the country’s steel sector conducted by S&P Global Platts for October.
Most participants also agreed on expectations for higher inventories as lack of automotive demand, with a build-up of imports at European ports leaving steel mills fearful amid slow buying activity, according to the survey data.
The survey, which is used to compile an index demonstrating pricing sentiment, was conducted at the beginning of this month and showed the overall expectation for steel prices at 25, down a whopping 31 points from the previous month, with all participants largely in tune over the direction of prices.
Steel pricing sentiment has taken a downturn since the summer slowdown and has struggled to recover since then, with cheap imports and a semiconductor shortage hindering the automotive industry from consuming previously agreed steel volumes, leading to higher availability of steel.
Back in September, the European market remained very uncertain about prices and inventories, as the semiconductor shortage forced carmakers into intermittent production, with one known manufacturer Stellantis having to cut production from 24/7 to just five days a week and two major European original equipment manufacturers announcing a cease in production.
Since then, market participants have been very cautious to divulge workable prices at a time when transaction activity has been minimal, with buyers choosing to hold off spot purchases in fear of imminent lower prices as more import material clears European ports.
“Imports are a serious threat in this period and given the semiconductor issue remaining unresolved for the foreseeable future, auto demand will remain under pressure,” a European trader said. “We are in a buyers’ market now.”
With producers still in long-term contract negotiations with manufacturers, Western European mills are keen to keep spot prices firm, while Visegrad mills have finalized deals reportedly below Eur1,000/mt ex-works Ruhr.
“Currently, the barrier is at Eur1,050/mt ex-works Ruhr,” a German distributor said. “I see a potential towards Eur1,000/mt.”
Hot-rolled coil prices have dropped considerably since their peak toward the end of June 2021. The daily Platts HRC assessment stood at Eur1,047.50/mt EXW Ruhr Oct 8, down nearly Eur143/mt from a record high of Eur1,190/mt June 25.
Unwanted autos
As domestic prices rise, European inventories are starting to pile up as unwanted automotive volumes – coupled with recently cleared imports – flood the market.
While some mills stand confident that peripheral sectors like the heavy machinery and construction industries will be able to soak up the steel surplus, some European mills were heard to be channeling available steel volumes into exports.
“The cancellation of orders by automotive has forced EU mills to try and move volumes to export markets in order to not contaminate domestic prices,” a European mill source said.
A German distributor said: “Lack of automotive demand across Europe is causing increasing stocks. The availability makes mills nervous – there are no real transactions, inventories are growing, and no one needs to buy. People are sitting and waiting, mills are giving discounts to secure volumes.”
Stockholders and distributors were still busy with outstanding orders and assessing what orders they could cancel amid depressive sentiment.
The index for inventory sentiment stood at 77, suggesting a very aggressive rise in stored volumes from September, when the index stood at 57. End-buyers were the most bullish on inventory increases with an index of 75, while producers stood at 58 and traders at 38.
Capacity fears
Production forecasts for October were rather muted with the overall index at 51, denoting stability. Most bullish in this category were producers at 56, followed by end-buyers at 50 and traders at 46.
The European market has been expecting some additional production, with Thyssenkrupp having restarted its biggest blast furnace Oct. 1 after a reline. Salzgitter said in August it would restart its Blast Furnace C in November, which had been idled in 2019. A Salzgitter spokesperson said earlier this week the restart would be “under consideration.”
As inventories rise, market players have expressed their doubt about mills potentially adding more unneeded capacity to the market.
“I don’t know what to think of those mills restarting. It’s risky, but perhaps they want to catch as much volume as possible before there is a real collapse,” the European trader said. “We also have to consider that [steel body] Eurofer’s demands for quotas/tariffs are a bit unfair if there are unused European capacity falsely inflating prices.”
— Amanda Flint

Turkey approves Paris climate pact, sets 2053 as net zero carbon target
Turkey at last approved the Paris Climate Agreement at the parliament and it entered into force as of Oct. 7 after it was published in the official gazette.
Turkey was one of the few countries in the world that didn’t ratify the agreement, because the government opposed Turkey being listed as a developed nation at the agreement, which means the country will have more responsibility on climate than developing nations. Lawmakers protested this detail of the agreement while approving it.
Murat Kurum, minister of Turkish Environment and Urbanization, said he hoped the decision would help the country achieve net zero carbon status by 2053. Turkey is aiming to reduce the rise of emissions by 21% by 2030, Platts learned.
Turkey will update its targets of emissions in manufacturing, energy, waste, transportation, agriculture and in other fields in this regard and the subtopics of the planned work will be addressed in the Climate Conference that is expected to be held in January 2022.
Turkey published its “medium-term (2022-2024) economic program” on Sept. 5 in the official gazette, which was a program focusing on sustainable growth and “Green Transformation” in the nation’s key industries, including steel, to help achieve a more source-efficient, greener economy, as Platts has reported.
“Within the scope of the Turkey-EU Customs Union, necessary work and preparation will be made in dialogue with the EU by coordinating the public sector, the private sector, non-governmental organizations and universities to ensure adaptation to the European Green Deal regarding Turkish exports to the EU,” it said in the program.
Turkey’s “Green Deal Action Plan” proposes 32 targets to adapt with the EU’s Carbon Border Adjustment Mechanism (CBAM). In this regard, studies for a national carbon pricing mechanism could be also carried out, taking into account the EU’s carbon border adjustment mechanism and sectoral sensibilities.
Turkey will support research and development activities and technologies for green production. “Green Industrial Zones” will be constituted in this regard.
The Turkish steel sector has already accelerated its investments for “Green Steel Production” in recent years, like solar energy plants, metal recovery services and EAF quantum electric arc furnaces, reducing both operating costs and CO2 emissions.
— Cenk Can

Automotive: European inventories crash
Inventories across Europe are feeling the strain with destocking in Q1 of circa -200,000 units, followed by a sharp -700,000 in Q2.
While inventory data is not publicly available in Europe, recent events continue to highlight that inventory movements are a critical component to understand the likely evolution to build volumes.
European inventories are now showing new strains, with destocking in Q1 of circa -200,000 units, followed by a sharp -700,000 in Q2. We expect this to have continued into Q3 (-380,000), before starting to turn around in Q4 – although there is still uncertainty on this to some extent.
Indeed, the destocking we project over Q1-3 exceeds that suffered by the sector in Q2 2020: 1.270 million versus 1.020 million. But a devastating collapse similar to that suffered in the wake of the Lehman Brothers crash (1.540 million) should not be ruled out, and this merely highlights the scale of the crisis currently being felt by the sector.
European OEMs have been forced to trim build significantly, while incoming orders have slowed as both have been impacted by the chip shortage. Oddly enough, European days’ supply is looking heathy because we are in an unusual position where both the flow of build and the flow of orders are being impacted by what might be considered a unique set of circumstances.

If we were to assess the market’s potential demand, then, clearly, the industry would be supply-constrained across the board. Rather than 60 days’ supply, with constrained demand, we would probably be looking at circa 40 days’ supply, with reference to ‘real’ underlying demand.
However, some OEMs have been more severely impacted than others, as illustrated in the Inventory Assessment table below.
European inventories crisis is being felt across the board.
This table should be studied with an eye on the benchmark. At a glance, we can see that Ford and Tata Groups were operating well below their benchmarks in Q2. For Q3, meanwhile, Daimler and RNM joined the ‘critical list’.
What is clear, however, is that this inventory crisis is being felt right across the board.
With the notable exception of Ford, whose days’ supply holdings collapsed by 25% in Q2, all the OEMs show slippage in days’ supply holdings in Q3 and are now mostly operating below the level of inventories that they would ideally like to hold.


Most Indian flat steel quotas into Europe already met: EC
Indian flat steel volumes are vastly dominating European import levels, with most quotas for Indian flats already exhausted, according to European Commission data Oct. 7.
The Indian hot-rolled coil quota for October-December totaling 169,717 mt, cold-rolled coil quota totaling 150,937 mt and quota tally for hot-dipped galvanized category 4a of 49,651 mt were already exhausted.
Data showed that 34,478 mt of Indian hot-dipped galvanized category 4b was remaining out of a total country-specific quota of 70,874 mt, while approximately 780 mt was awaiting allocation as of 4:30 pm London time on Oct. 7.
For the Russian HRC country specific quota, 264,169 mt remained out of a total of approximately 416,848 mt, while 15,781 mt was awaiting allocation.
For Turkish HRC, 125,622 mt remained out of a total quota of approximately 330,388 mt while around 25,041 mt was awaiting allocation on Oct. 7 as of 4:30 pm London time.
Indian flats steel products seemed to have dominated the import quota into the EU for the October-December period.
“I was surprised by the Turkish quota. I was expecting it to be higher, but it looks like it isn’t being allocated that fast,” one European trader told S&P Global Platts. “The tonnage was lower than expected and India is super high as expected. The HDG quota is even worse and there are not many offers in the domestic market so the prices should be strong.”
Platts assessed Northwest European hot-rolled coil stable at Eur1,047.50/mt ($1,211.53mt) ex-works Ruhr on Oct. 7.
Indian HRC total import volumes awaiting allocation totaled 205,034 mt, around 121% of total quota, on Oct. 5, exceeding country-specific quota of 169,717 mt. Similarly, Indian HDG 4a import volumes stood at 182,438 mt on Oct. 5, approximately 367.5% of quota tally of 49,638 mt.
Rebar import quotas
In line with most Indian flat steel products, Turkish rebar imports showed a similar trend on the longs steel side. The country specific quota for Turkish rebar imports into the EU was already exhausted, EC data showed.
Sources reported that Turkish mills have sold around 110,000 mt rebar to Europe over the last three months, exceeding its country-specific quota. Therefore, even though, total quota tally for Turkish-origin rebar imports into the EU of 61,938 mt was already by Oct. 5, approximately 434 mt was awaiting allocation around 4:30 pm London time on Oct. 7, in addition to 5,047 mt which was awaiting allocation at 05:30 pm London time on Oct. 6, following exhaustion of total country quota.
“I think the figures are clear, we have to pay,” another EU trader said.
The trader said he would no longer buy from Turkish mills.
“We will see how many European buyers will be keen to take the risk,” he said. “The best would be for the Turkish organize themselves to share the quota on their end so that they don’t oversell globally to EU buyers.”
The volumes which will not be cleared during October-December period will be stored at ports awaiting allocation during the January-March 2022 period, where buyers are expected to pay storage costs.
“This has probably happened, and volumes are at the port for January, for sure,” the trading source said, adding, “Storage costs are nothing compared to [antidumping] duty.”
Platts assessed Turkish exported rebar at $672.50/mt FOB Turkey Oct. 7, up $2.50/mt on day.
Approximately 33,488 mt of the total October-December quota of 59,963 mt for Russian-origin rebar remained on Oct. 7, while 1,349 mt awaited allocation.
— Rabia Arif, Amanda Flint

Klöckner partners with Swedish H2 Green Steel venture
Klöckner & Co says it has partnered with Swedish start-up H2 Green Steel (H2GS) and secured unique access to substantial volumes of steel that is considered almost free of CO₂ emissions.
With this collaboration, Klöckner is boosting its offering of sustainable products and services significantly, Kallanish is told by the German-based distribution group. It says it is seizing the strategic opportunity to deeply integrate the new and attractive business activities arising from green steel into its business model.
“As part of our corporate strategy, we are working at full speed to implement this new offering, which will make us a pioneer of sustainability in the steel industry,” says Klöckner chief executive Guido Kerkhoff.
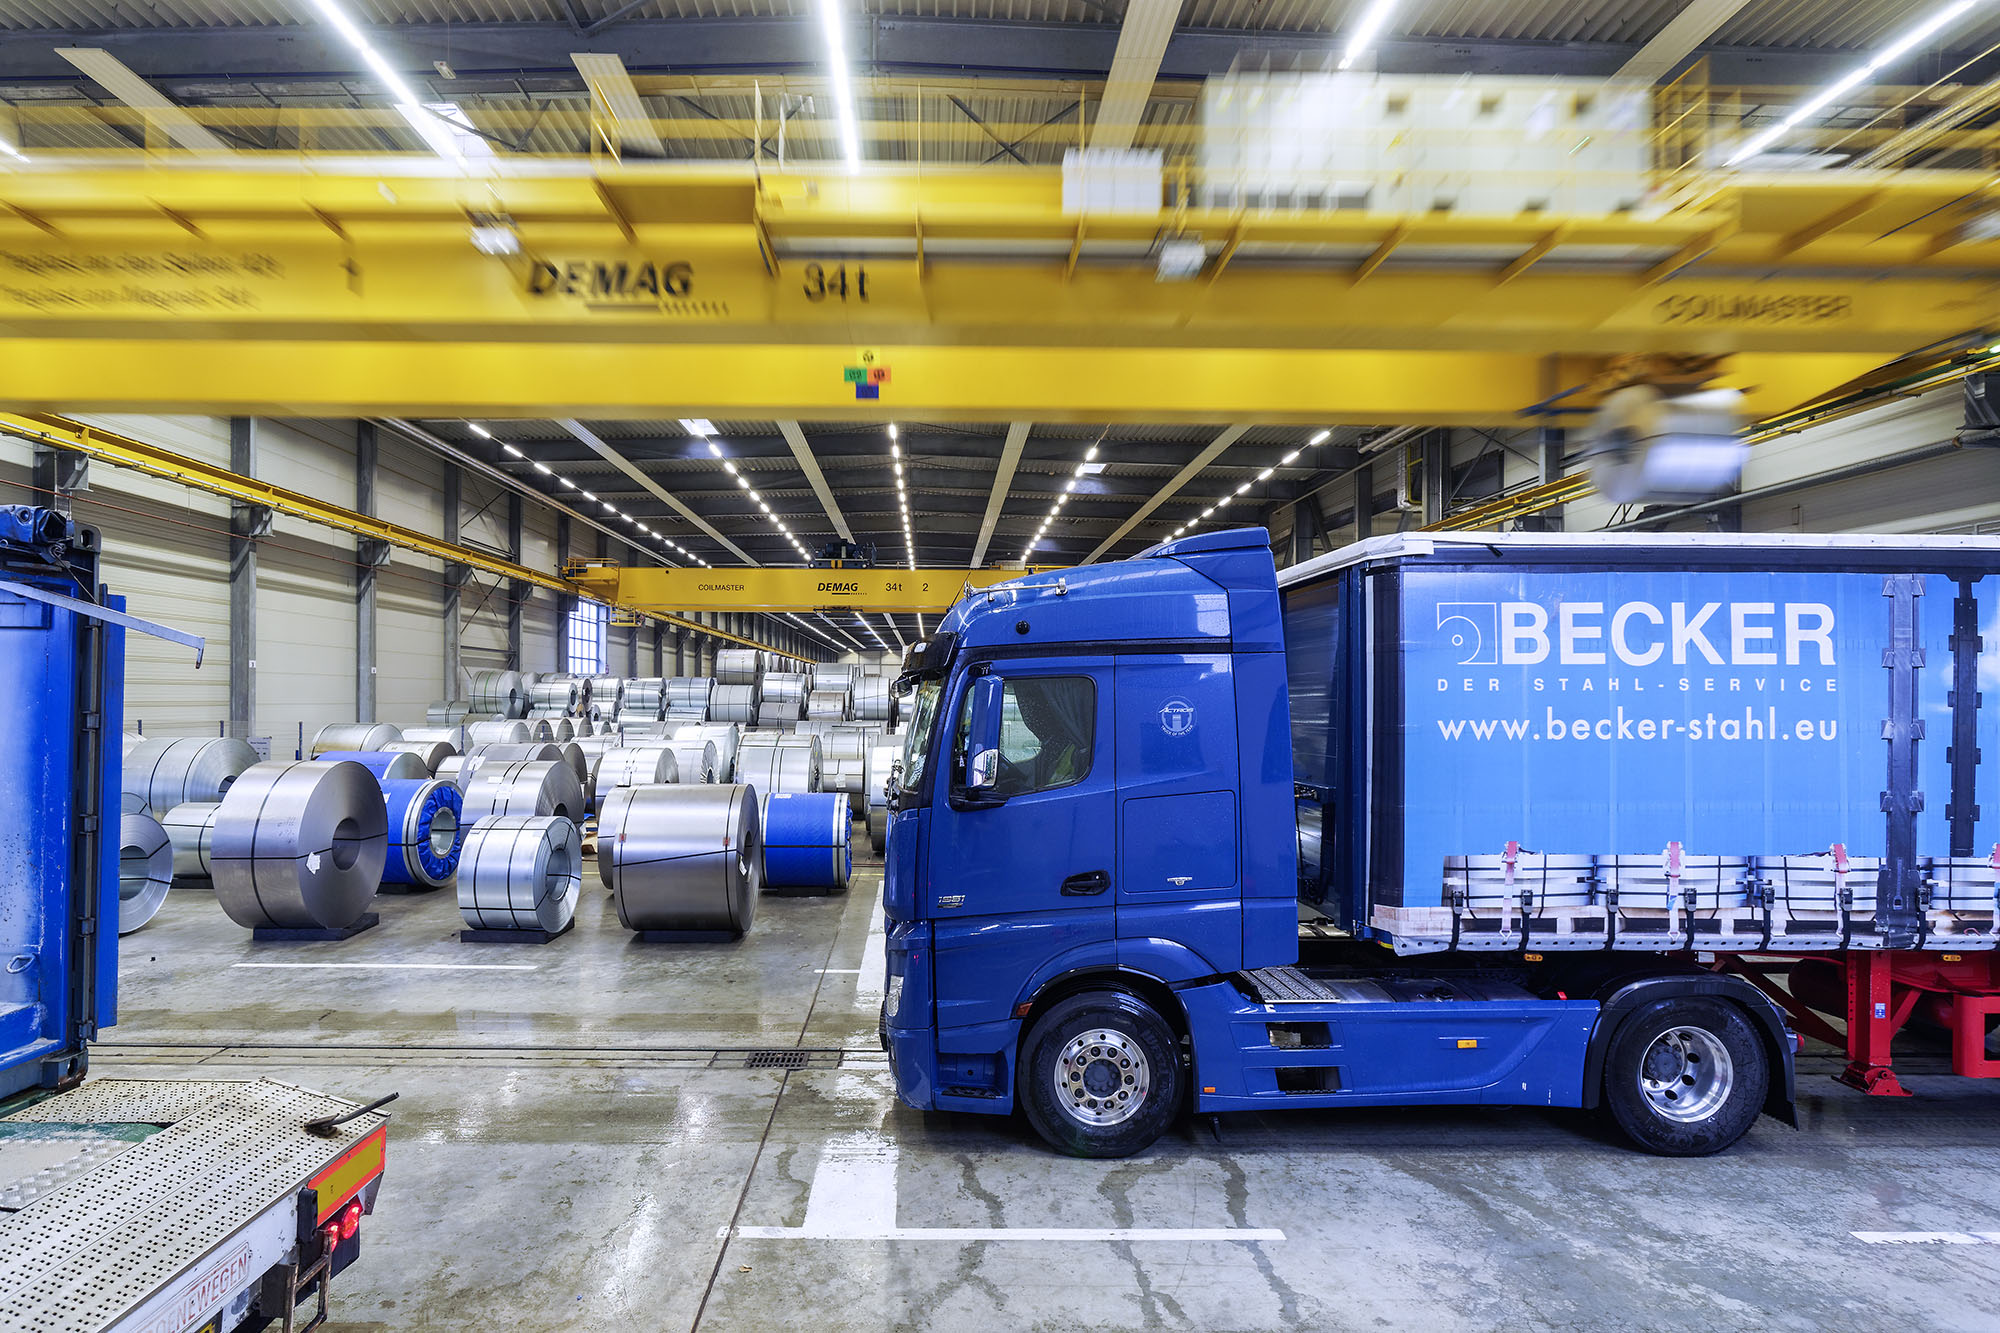
The company is securing significant quantities of green steel for its customers at an early stage. Starting in 2025, the initial partnership defines the delivery of annual volumes of up to 250,000 tonnes, which may be extended in the future. The flat steel supplied by H2GS will be processed primarily by Klöckner subsidiary Becker Stahl-Service. The products will be offered to customers especially in the European automotive and domestic appliance industries.
Klöckner notes it is committed to the UN Global Compact initiative “Business Ambition for 1.5°C”, thus aligning its business activities with science-based targets in order to limit the global temperature increase.
Christian Koehl Germany

Mechel-Service eyes future shipments increase
Mechel’s trading arm, Mechel-Service, posted a 9% on-year increase in deliveries in January-September to 1.23 million tonnes.
Sales of hardware products grew by 129%, structural shapes by 28%, beams by 29%, and reinforcement and wire by 3% and 38%, respectively.
“We continue to develop sales of high-margin products and this year we plan to increase the sales of ropes and hardware from Mechel’s Beloretsk Metallurgical Plant, as well as the products of the rail and section mill of the Chelyabinsk Metallurgical Plant,” says Mechel-Service director for sales Stanislav Karpov. “We plan to continue creating sub-sorting warehouses in Russia’s regions, as well as equipping covered warehouses.”
Earlier, Mechel-Service delivered 12,000 tonnes of beams for the construction of the Amur Gas Processing Plant of Gazprom (see Kallanish passim). Among the products supplied were I-beams, which have a high load-bearing capacity with a low specific weight. Its flanges distribute the load and reduce the risk of structural failure.
Mechel-Service posted a 4% on-year increase in shipments in 2020 to 1.52 million tonnes despite the impact of the Covid-19 pandemic. The company continued to supply large infrastructure projects in Russia, housing construction, construction of bridges and sports facilities.
Parent company Mechel saw first-quarter-2021 sales of long products fall 7% on-quarter and 13% on-year to 564,000t. Despite lower sales and output, revenue rose 10% on-quarter and 13% on-year to RUB 76.1 billion ($1.04 billion), while profitability rose to 24%.
Svetoslav Abrossimov Bulgaria
Thyssenkrupp starts commercial supply of low-carbon steels
Thyssenkrupp Steel delivered on Thursday the first batches of its climate-neutral steel, which it markets under the brand name “Bluemint”, Kallanish hears from the company. The first customer to be supplied with flat steel products of the Bluemint family is German bathroom builder Kaldewei.
Through the use of hot-briquetted iron, the company claims to have reduced its emission intensity per tonne of steel by 1.5 tonnes to 0.6t of CO2, an overall reduction of 70%. The emissions of the so-called upstream chain – Scope 3, meaning emissions that occur during the production and transportation of the raw materials – are retained.
Tk underlines that the approach has been independently assured by international certification body DNV, as well as by the Wuppertal Institute for Climate, Environment and Energy, the company’s advisor to the project.
“The methodology for calculating product-related CO2 savings is in accordance with the internationally recognised Greenhouse Gas Protocol for Product Life Cycle Accounting and Reporting Standard,” confirms Priti Hoffmann, sustainability lead, Benelux at DNV.
The launch of the Bluemint product family also means the start of active marketing measures for products with an allocated low CO2 intensity. Following the contract with Kaldewei, “we will gradually expand the commercialisation of Bluemint, and have already commenced negotiations with a number of additional customers,” tk Steel chief executive Bernhard Osburg.
Christian Koehl Germany

Assofermet formally requests review of EU safeguard system
Italian distributors’ association Assofermet has formally lodged with Italian authorities a request for a review of the EU safeguard system, which is affecting steel trade, Kallanish learns from Assofermet steel division president Paolo Sangoi.
The association noted that the request was well received by Italian economic development minister Giancarlo Giorgetti. The minister reiterated this week during the Made in Steel show in Milan that the safeguard system no longer works properly and needs revision.
Sangoi noted the negative effects of safeguard measures are visible clearly across Europe. He mentioned, for example, the long backlog at Italian ports due to the need to clear steel volumes using new available quotas. He also added that the steel distribution and processing network in Italy was forced to order from abroad due to the lack of volumes available internally.
“My group had to suffer three renegotiations of existing contracts with European suppliers during 2021,” Sangoi said, referring to the difficulties created by rallying prices and scarce availability in the domestic market.
The official European Commission document confirming the extension of safeguard measures earlier this year included the possibility of launching an annual review.
Emanuele Norsa Italy