


Pittini invests in new rebar rolling mill in Verona
Italy-based long steel producer Pittini has announced that it has invested in a new rebar rolling mill to be built at its Verona plant. The mill in question is expected to be operational by the end of 2025.
According to the producer, the new production line, designed to produce rebars for the construction industry, will feature advanced technological solutions focused on energy efficiency, process optimization and environmental sustainability. The new mill is a strategic investment that will further strengthen the production capacity of Pittini and consolidate its competitiveness in the Italian and central European markets.
The producer also unveiled its warehouse project in Sicily, aimed at optimizing logistics and improving the distribution of products along the northern and southern parts of Europe.


Made in Steel: Italian flats market between difficulties and signs of recovery
At Made in Steel 2025 held at Fiera Milano Rho, Italy, a roundtable was convened to discuss the current state and future outlook of the Italian and European markets for flat steel products. The discussion offered a clear-eyed, realistic, and at times moderately optimistic analysis, featuring insights from leading industry figures.
Andrea Gabrielli, chairman and CEO of Gabrielli Group, opened the panel by outlining a challenging start to the year, commenting, “2024 closed with an eight percent decline in flat product sales, bringing us back to levels even lower than the pre-COVID period,” adding, “The first months of 2025 have shown a slight recovery, but a 3-4 percent drop still persists.” He also pointed out the growing difficulties in procurement due to changes in EU safeguard clauses and provisional antidumping duties on imported HRC, which are significantly limiting import opportunities from third countries.
The perspective on welded pipe products was provided by Pierluigi Pegorari, CEO of Arvedi Tubi Acciaio, who described an apparent stability in volumes, but increasing pressure from market distortions. “Phenomena such as stockpiling are disrupting the entire distribution system,” he explained. “For us, the priority is not growth but consolidation in the downstream segment, focusing on special steels,” he said.
Gianfranco Imperato, CEO of Trasteel, offered an overview of slabs and plate products, acknowledging a difficult 2024 but also highlighting early signs of stabilization. “After a 6-7 percent drop in consumption across Europe, we are now seeing a slight realignment in margins thanks to reduced supply and a rebound in prices,” he noted.
Looking ahead, the speakers agreed on the need to tackle uncertainty with flexibility and a strategic vision. “The European manufacturing sector has lost competitiveness. We need to pay close attention to key industries like home appliances and automotive,” Gabrielli observed. Pegorari stressed the urgency of structural interventions, particularly to support energy and infrastructure.
Imperato concluded with a message of cautious optimism, stating, “The order book looks solid, but the market remains cautious. That said, the history of steel suggests that after every downturn a recovery inevitably follows.”
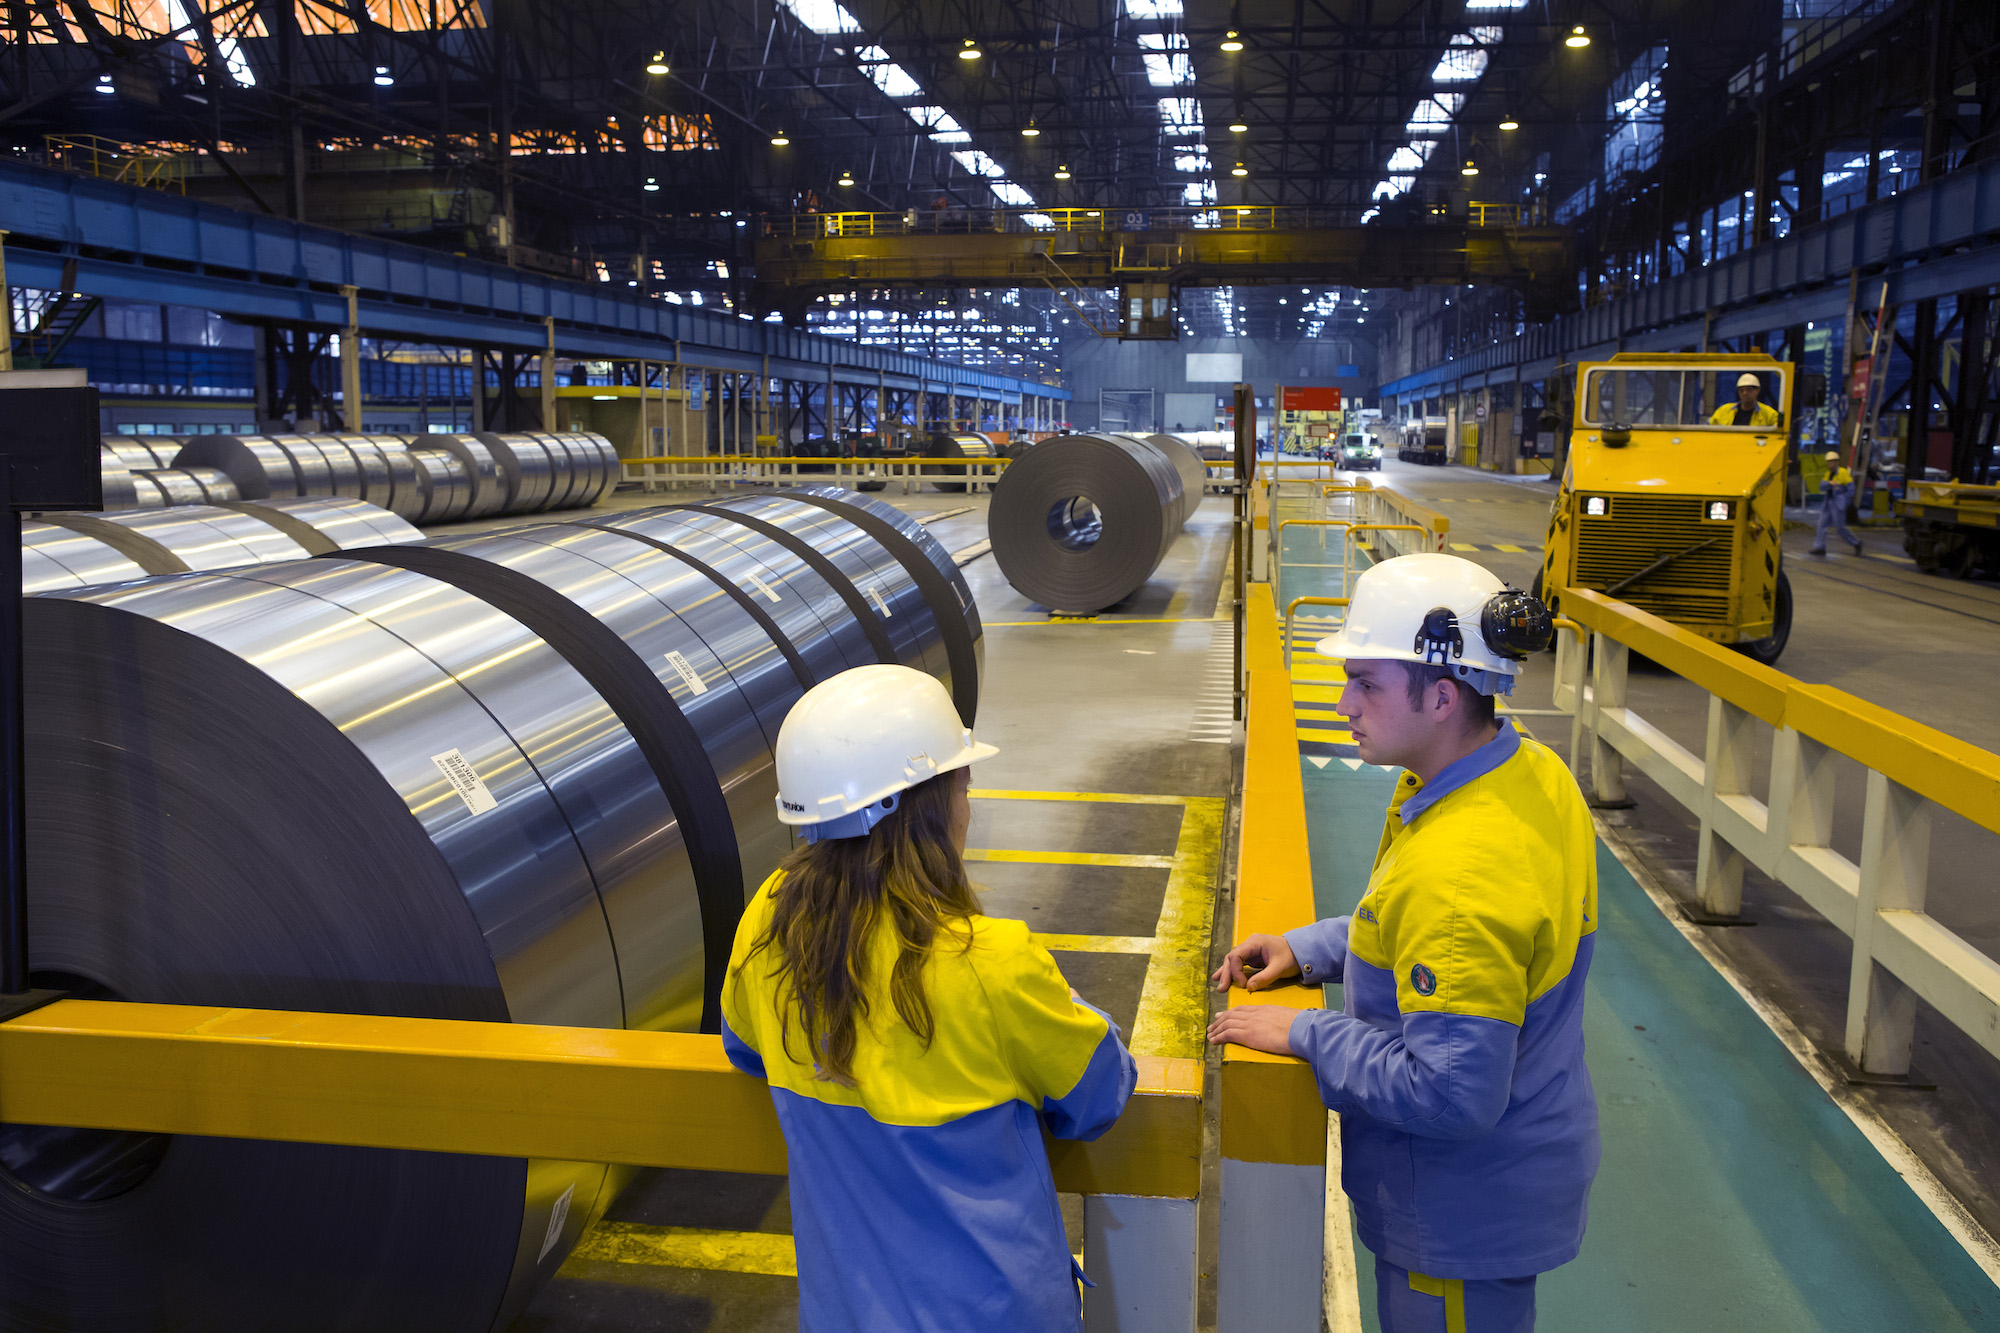
Tata Steel Nederland launches new HR steel product for automotive parts
Tata Steel Nederland has announced that it has launched a hot rolled steel product under the brand HyperFlange® to be used in automotive parts.
The tests conducted by the company have shown that CP800 HyperFlange demonstrates significantly higher resistance to crack growth than standard HSLA HR700LA.
“Through our HyperFlange products, we have optimized our steels to enhance edge ductility. This translates to fewer edge cracks, minimized material wastage, and reduced production line interruptions, all contributing to heightened productivity and efficiency in the car makers’ press shop,” Moe Ziaran, marketing manager at automotive chassis & components, said.

Polish domestic long-steel market quiet after May holidays
Prices for steel rebar and wire rod in Poland were unchanged over the week ended Friday May 9, in line with the recent slowdown in market activity over the early-May holiday period.
“The situation remains stable within the Polish market, with market participants still waiting to see what will happen with price trends,” a seller source told Fastmarkets.
Most market participants estimated the tradable market price for rebar at 2,640-2,700 zloty ($703-719) per tonne CPT.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar), domestic, cpt Poland, was 2,640-2,700 zloty per tonne on Friday, unchanged since April 25.
Trading was slow because buyers were being cautious about a possible reduction in scrap prices, which are a strong indicator for the long steel market.
“We expect scrap prices to go down quite a lot in the next few weeks, which will lower prices for steel,” another distributor source said, citing imminent market decisions by Polish and German scrap suppliers.
Wire rod
Prices for Polish domestic low-carbon drawing-quality wire rod were also stable in the week to Friday, sources told Fastmarkets. Some Polish mills were offering the material at prices of 2,800-2,950 zloty per tonne.
Industry sources estimated the tradable market at 2,770-2,850 zloty per tonne CPT.
Fastmarkets’ price assessment for steel wire rod (drawing quality), domestic, delivered Poland, was 2,770-2,850 zloty per tonne on Friday, unchanged week on week.
Regarding imports, one mill was heard offering wire rod for €700-720 ($787-809) per tonne delivered, while some traders were said to be offering low-carbon wire rod for €640-660 per tonne delivered.

Limited demand keeps putting pressure on HRC prices in Europe
Fastmarkets’ daily calculation of the steel hot-rolled coil index, domestic, exw Northern Europe was €646.75 ($727.11) per tonne on Monday May 12, down by €4.92 per tonne from €651.67 per tonne on Friday May 9.
One of the mills in the region reportedly dropped offers to as low as €635 per tonne ex-works, but even this price did not spark any trading, a buy-side source told Fastmarkets.
A second producer was also heard to be cutting offers, but, according to a source within the company, its prices remained in the range of €640-660 per tonne ex-works.
Estimates of workable prices were still coming in at €640-660 per tonne ex-works, but no business was heard done during Monday.
In Southern Europe, Fastmarkets’ daily steel hot-rolled coil index domestic, exw Italy was calculated at €610 per tonne on Monday, down by €1.67 per tonne from €611.67 per tonne on Friday.
The assessment was based on offers heard in the range of €600-620 per tonne ex-works, depending on the mill.
“[The HRC market in] Italy is really weak — high stocks at distributors and slow real demand,” one source said, adding that import offers are “getting interesting.”
Lately, July-shipment Turkey-origin coil has been available at €550-555 per tonne CFR to Italy, duty paid, Fastmarkets heard.
From Indonesia and Malaysia, offers for July-shipment coil were reported at €510-520 per tonne CFR, while Indian material was available at €560 per tonne CFR.
In Northern Europe, material from Indonesia and Malaysia was said to be available around €510 per tonne CFR, and coil from India was reportedly at €570 per tonne CFR.

4 things learned at Made in Steel trade fair 2025
Steel prices lose momentum amid low demand
Several weeks ahead of the trade fair there was a holiday stretch across Europe, so trading activity slowed down across all steel markets. Sources hoped the Made in Steel event would bring greater clarity on further trends, with some even expecting further price increase announcement for flat steel in particular from European steelmakers.
However, optimistic moods faded and no “price breakthrough” happened, industry sources said.
“[Hot-rolled coil] prices remained where they were. In fact, in May-June due to seasonality factors and overall weak demand, we might see downward correction,” a steel service center source told Fastmarkets.
Fastmarkets’ calculated the daily steel hot-rolled coil index, domestic, exw Northern Europe was €652.08 ($735) per tonne on May 8, down by €0.42 per tonne from €652.50 per tonne on May 7.
The index was down by €2.92 per tonne week on week and down by €2.30 per tonne month on month.
Offers voiced at €680-700 per tonne ex-works by first-tier suppliers in April were not eventually sealed in deals.
A similar trend was observed in long steel markets, with European steelmakers struggling to lift prices, while buyers were pushing for discounts, citing drops in prices for steel scrap, which is the primary raw material for long steel products.
“Buyers ask for €10-20 per tonne discounts, which we cannot give them, cause input costs remain high, energy, labor costs, etc., etc.,” a long steel producer in Italy told Fastmarkets.
Fastmarkets’ weekly price assessment for steel reinforcing bar (rebar) domestic, delivered Northern Europe was €655-680 per tonne on May 7, narrowing upward from €650-680 per tonne on April 30.
Trade defense measures disrupt supply chains
The introduction of tougher steel safeguards measures in April, followed by the implementation of provisional duties against Egypt, Vietnam and Japan, made steel imports even more complicated for European buyers, driving traditional suppliers out of the market.
In 2024, the EU imported 9.7 million tonnes of HRC, up from 9.24 million tonnes in 2023, according to Global Trade Tracker (GTT) stats.
Altogether, Egypt, Vietnam and Japan supplied 2.45 million tonnes of HRC to the EU in 2024, accounting for 25% of total HRC imports to the bloc, GTT stats showed.
“Importing steel was made close to impossible, especially for smaller companies which can’t handle the costs [of CBAM, duties, etc.],” a buyer in Europe said.
With a 13% quota cap on the “other countries” quota for HRC and reduced quarterly allocations for key suppliers by 10-25%, European buyers were getting increasingly cautions with new import bookings, seeking new suppliers unaffected by trade measures.
With traditional suppliers facing trade limitations, in 2025, new suppliers — Malaysia and Indonesia — were seen capturing a larger market share.
Sources noted that the sharp increase in HRC deliveries from these two origins might result in either an anti-dumping probe or their inclusion in the “other countries” quota, with the latter appearing more likely than the former.
For example, in January-March, Indonesia has already supplied 86,918 tonnes of HRC to the EU, compared with just 22,684 tones during the same period in 2024. Total HRC deliveries from Indonesia to the EU were 249,018 tonnes in 2024.
“An anti-dumping probe takes nine months or so. Plus, Indonesia’s domestic market is not transparent enough to compare domestic and export prices. It’s more likely they will be included in safeguards (which takes less time to be implemented),” a buyer source said.
Decarbonization slows down in Europe in the face of crisis
The European steel sector has been facing rising production costs, increased pressure from low-cost imports from Asia and the ongoing deterioration of the steel demand-supply balance in Europe, sources told Fastmarkets.
Crude steel output across Europe rebounded slightly to 129.5 million tonnes in 2024, compared with 126.3 million tonnes in 2023, according to the World Steel Association. But the total volume was still below the 159.4 million tonnes recorded pre-Covid in 2019.
“It’s not [attractive] to produce steel in Europe anymore,” a steel mill in Germany said.
Apparent steel consumption in the EU amounted to 127 million tonnes in 2024, down by 2.3% from 130 million tonnes in 2023 and lower than during the 2020 pandemic year, when it stood at 129 million tonnes, data from the European steel association Eurofer showed.
Real steel consumption shrunk by 3.8% in 2024 to around 132.7 million tonnes, from around 138 million tonnes in 2023.
While both steel consumption and production in the EU decreased, the share of steel imports in the European market has been rising, crowding out local supply, sources noted.
Carbon steel imports to the EU in 2024 totaled 26.36 million tonnes, up by 6.4% compared with 24.78 million tonnes in 2023, Eurofer data showed.
In such conditions, “investing billions of euros in decarbonization was becoming unmanageable,” a steel mill source in Europe told Fastmarkets.
“Every project needs return on investments. We put money into green energy, certifications, [Environmental Product Declarations], etc. And we struggle to charge premiums for decarbonized steel because buyers are not willing to pay a single euro more in such market,” a long steel producer told Fastmarkets.
In autumn 2024, the largest European steelmaker ArcelorMittal said it would postpone a final decision on several investments in direct-reduced iron (DRI) modules across Europe due to challenging market fundamentals.
The company has said it will be able to review investment priorities in Europe after the implementation of the EU’s Steel and Metals Action Plan.
In March 2025, Germany’s largest steelmaker thyssenkrupp put on hold a hydrogen tender for its green steel plant due to elevated prices but said that it was still committed to the Duisburg site’s green transformation.
Sources said that, in addition to the high premiums, the lack of public projects across Europe — projects that could insist on green steel procurement — and the lack of stimulus measures to encourage “going green” were limiting demand for green steel.
“If authorities do not push for green steel use through public procurement, [green steel] will remain a niche market,” a mill source said.
“The effect of energy prices and also the cost of steel within the green transformation is one of the key issues,” the distributor source said. “The distribution of green steel will be working… if we make green steel, put a label on it and make it part of public procurement.”
Fastmarkets’ weekly assessment of the green steel, domestic, flat-rolled, differential to HRC index, exw Northern Europe was €150-200 per tonne on May 8, stable week on week.
Fastmarkets’ weekly price assessment for green steel, differential to steel reinforcing bar (rebar), domestic, delivered Northern Europe was €20-40 per tonne on Wednesday, widening upward from €20-30 per tonne a week earlier.
European mills confirmed that they were selling most of their green steel volumes — both flat and long — to the Nordic countries.
“Buyers [of green steel] in Norway, Denmark and Sweden are more motivated to buy green steel. They know they can pass the costs [of green steel] down to the end user, because there are many public projects requiring green steel procurement,” a buyer source said.
CBAM costs might “wipe out” small companies
The EU’s CBAM is considered to be a major decarbonization driver. It is a tool intended to put a fair price on the carbon emitted during the production of carbon-intensive goods that enter the trading bloc.
However, CBAM’s complexity poses certain challenges for importers and brings additional costs. European steel buyers have expressed concerns about the lack of clarity in its implementation, the potential for circumvention and the potential for “lost added value” for the European manufacturing industry.
“Steel importers might start avoiding importing goods covered by the CBAM and instead buy items with higher customs classification instead of semi-finished products,” a trading source said.
“Small- and medium-sized steel importers are concerned with CBAM compliance costs, including supplier communications, software, data verification and so on,” a source in Germany said.
“We did the calculations based on our imports volumes in 2024, and CBAM handing costs are estimated to be €6.5 million. This is totally unmanageable,” a buyer in Northern Europe said.
In the fourth quarter of 2025, the European Commission will introduce CBAM amendments, including a potential extension of its downstream scope and additional anti-circumvention measures, Fastmarkets reported.


US, China agree 90-day tariff pause to continue negotiations
The US and China agreed on Monday to temporarily slash so-called reciprocal tariffs and respective countermeasures by 115% to 10%, Kallanish reports.
The announcement made in Geneva states that both countries will pause these tariffs for 90 days to continue negotiations towards “rebalancing trade.” A baseline 10% tariff rate will remain in place in both countries during the period. Other US tariffs on Chinese goods have also been retained, including the 20% rate related to fentanyl, US officials say in a press conference.
Additionally, China will suspend or remove the non-tariff countermeasures taken against the US since 2 April, which include export restrictions.
Their joint statement states that the trade talks in Geneva between China’s Vice Premier He Lifeng and US treasury secretary Scott Bessent and US trade representative Jamieson Greer created a “mechanism to continue consultations on economic and trade relations.”
The deal recognises the importance of bilateral economic and trade relations to both countries and the global economy. It also considers the need for a “sustainable, long-term and mutually beneficial economic and trade relationship.” The countries have agreed to continue advancing negotiations “in a spirit of mutual openness, continuous communication, cooperation and mutual respect.”
Bessent says that it became clear that “neither side want decoupling,” while noting Washington wants China to open for more US goods. He also indicates potential purchase agreements to help balance trade, stating that the US massive trade deficit with China stems from negligence by previous US administrations.
China’s commerce ministry notes that this round of talks has attracted great attention from the international community. Vice Premier He says Beijing is willing to work with the US to “inject more certainty and stability into the world economy.”
Other existing US tariffs on certain sectors, including a 25% tariff on cars and auto parts, remain in place. It’s unclear when a new round of talks will take place.
Analysts at ING say the trade war de-escalation is a “win-win” as it benefits both economies. Yet, they believe the agreement, “which significantly lowers tariffs without any concessions, is likely to be viewed as a particular victory for China.”
“This was a larger-than-expected de-escalation and represents an upgrade to the outlook, though the negotiation process will likely remain challenging,” they add.


EU HRC prices face downward pressure as market sentiment remains cautious
European domestic hot-rolled coil prices remained largely stable May 8, with sources citing a modest erosion of EUR10-20 across various regions.
“Prices have been pretty stable overall, but we expect a small dip in the short term, with HRC ex-Ruhr at EUR630-640 and ex-Italy at EUR620,” a mill source said. “We’re not seeing a lot of action in the market right now, and the outlook remains fairly weak.”
Despite this, there is optimism for the second half of the year, with expectations for a potential improvement as market conditions stabilize. However, concerns about the gap between domestic and import prices, combined with regulatory uncertainty, remain.
“Import activity is quieter, and there’s little insight on where it will go,” the source added, noting that a lack of clarity on the Carbon Border Adjustment Mechanism (CBAM) was exacerbating market hesitancy. “People are starting to calculate what it really means, but there are still many gaps to be filled by the commission.”
Platts assessed HRC ex-works Italy at EUR620/mt and HRC CIF Southern Europe at EUR530/mt, both stable day over day. Platts assessed HRC in Northwest Europe at EUR640/mt EXW Ruhr, down Eur5 day over day, and HRC CIF Antwerp at Eur540/mt, stable day over day.

EU flats market shows caution at Made in Steel trade fair amid rising volatility
Uncertainty was the dominant theme at this year’s Made in Steel trade fair in Milan, Italy, as Europe’s flat steel market grappled with weak demand, volatile trade dynamics, and mounting regulatory complexity.
As the steel industry gathered in Milan May 6-8 for the trade fair, market participants shared largely bearish outlooks for the flat steel pricing trajectory and expectations for the continuation of poor near-term demand visibility.
Despite the recent trend of increased mill offers across Europe, many attendees noted that regulatory uncertainties and a lack of concrete activity have kept prices under pressure.
“The fair has been quite muted so far. Sentiment is generally negative,” a Southern European mill source said. “There’s a lot of uncertainty—quotas, tariffs, the situation with the US—all of it is complicating things.”
But some sources noted more positive signs.
A German stockholder expressed optimism that a ceasefire in the Russia-Ukraine conflict and increased infrastructure spending under the incoming German government could help lift demand. “We’re hopeful this will improve sentiment in the second half of the year,” the stockholder said.
Imports are under pressure
Although European import quotas have seen mixed allocation rates across hot-rolled coil, cold-rolled coil, and hot-dipped galvanized steel, sources at the fair offered mixed views on price viability and buyer receptiveness to the different origins.
Numerous sources cited an influx of Indonesian coils, with offers heard during the fair at Eur 570/mt CFR Italy. Whether the material was workable for the wider market or more suited for piping applications remained a key area of debate.
Discussing the feasibility of imports in general, and the reduced uptake of the quotas, one trader referred to an atmosphere of uncertainty, partially due to buyer hesitancy in the first quarter during the European Commission’s safeguard review, with the impact still being felt. Similarly, looking forward, he said, “Buyers booking imported material from Asia are trying to delay for a few weeks to see what domestic prices and end-consumers are doing.”
“But any material that is ordered now won’t arrive until after summer; nobody has any demand visibility that far out, and they don’t want to take the risk.”
Despite the South Korean import quota for HRC being exhausted during the fair, market reactions remained muted. Many recognized that domestic availability in Northern and Southern Europe remained strong.
“It is a buyers’ market,” said a second trader, who anticipated that domestic HRC offer levels will drop by Eur20-30 in the coming weeks.
“We would like to see higher prices, but there is not a lot of business, and a lot of competition at the moment [among] service centers,” a service center source said. “We are very curious where mill margins are, as they will struggle to drop prices.”
The same source also pointed toward short-term demand visibility as significantly affecting market confidence, reporting that some customers were asking for small, additional volumes at the last moment, limiting the ability to do forward planning.
CBAM uncertainty looms
The EU’s Carbon Border Adjust Mechanism continued to polarize the market, with many arguing there was a continued lack of clarity or transparency on the emissions reporting mechanism or the potential price impact it will have.
Several market participants anticipated a price increase, citing the additional administrative burden following a shift in preference for customs-cleared material versus CIF cargoes and metal from origins with lower default values. However, the absence of EU-declared benchmark/threshold emission values and a corresponding benchmark carbon level for each production pathway remain common criticisms.
More broadly, sources suggested that the legislation was adding an additional layer of uncertainty, with confusion over how CBAM can be hedged and how the additional cost burden was coming at a moment when the market was under considerable cost pressure across the supply chain.
Cautious outlook
While some fair attendees held out hope that Made in Steel would bring fresh momentum to the market, most agreed that visibility remained limited and pricing pressure was mounting, especially on the domestic side.
“We’ll reassess after the fair,” said a buyer. “But the market feels cautious. Unless something shifts, we may see prices heading down.”
Market participants pointed to persistent uncertainty around trade policy, muted demand, and regulatory developments as key themes shaping the outlook for flat steel in the coming weeks and months.

German engineering welcomes chancellor, upbeat on first quarter
New German chancellor Friedrich Merz should quickly set course for a recovery in the country’s economy and industries, says mechanical engineering association VDMA.
The first 100 days of the new government will be fundamental for tackling social and economic challenges, and for industrial growth and competitiveness, says VDMA president Bertram Kawlath.
He asserts that “Germany must once again become a European driving force and, together with its European partners, vigorously push for a deepening of the internal market.”
More concretely, he asks that “improved investment and innovation conditions with accelerated depreciation and a widely usable research allowance” should be facilitated to ensure innovation.
Meanwhile, the mechanical engineering industry completed the first quarter with the first positive year-on-year balance of orders in three years, Kallanish hears. Q1 saw an overall increase in orders of 4%.
Domestic orders from January to March were 1% higher y-o-y, while orders from abroad were up by 5%. The disparity widened in March alone with domestic business down 3%, offset by a 6% increase in foreign orders.
“It is therefore all the more important that the new German government now directly introduces brave reforms to strengthen the country, to attract investment again,” demands VDMA chief economist Johannes Gernandt. “We are now seeing a turning point in international business, while domestic business remains difficult.”
Christian Koehl Germany