


LME scrap contracts still falling; weekly trading volumes surge
Scrap futures contracts on the London Metal Exchange saw further losses over the week to Sept. 9, while weekly trading volumes surged.
S&P Global Platts assessed the September scrap contract down $5/mt week on week to $445.50/mt Sept. 9, while the October contract dipped $2.50/mt to $451.50/mt. The November contract lost $6.50/mt on the week to $447.50/mt, and December contract dropped $4.50/mt to $445/mt.
The contango structure for the September-October portion of the forward curve strengthened slightly on the week, suggesting that futures traders expect physical prices might strengthen in the near term, though maintaining softened levels. The October-November portion of the curve shifted into backwardation and the backwardated structure of the November-December portion of the LME scrap forward curve softened slightly on the week.
Spot prices for physical imports of premium heavy melting scrap 1/2 (80:20) dipped $2.50/mt on the week to $442.50/mt CFR Turkey Sept. 9, amid uncertainty of future price direction for scrap and finished steel products.
“Inflow [of scrap to yards] is still not good at lower prices, so I hope no one will be under pressure to sell,” one EU recycler said.
Weekly LME scrap futures trading volumes over the week to Sept. 9 totaled 63,400 mt, the highest weekly volume since the week ending Aug. 5, up from 23,950 mt recorded last week.
For near-term rebar futures, the contango structure of the September-October portion of the forward curve strengthened on the week in line with scrap, while the October-December portion of the curve shifted into backwardation. This suggests futures traders’ expectations that physical rebar prices may stabilize in the near term, before softening over the fourth quarter.
Platts assessed the September contract up $1.25/mt on the week to $672.50/mt Sept. 9, while October gained $5/mt to $680/mt. The November contract was flat at $675/mt and December dipped $3/mt to $672/mt.
Turkish physical rebar export prices inched down 50 cents/mt on the week to $667/mt FOB Sept. 9 as continued lack of demand maintained pressure on rebar export workable levels, though market sentiment was more positive amid mixed expectations that freight rates might come down in the near term.
“There is a positive sentiment in the market this week,” one Turkish trader said. “Freight rates might come down, especially for bulk shipments for October and November. But it is not trustworthy as I am talking with a lot of shipping companies and there is no guarantee that freight rates will go down.”
Another Turkish trader highlighted low demand. “There are no inquiries in the market today. So even if you do buy, which you might be able to do [at] $5-$10/mt less than [mill offers]…who are you going to sell it to? There are no buyers.”
The daily outright spread between Turkish export rebar and import scrap was assessed at $224.50/mt Sept. 9, up $2/mt on the week.
Rebar futures weekly trading volumes this week on the London Metal Exchange totaled 18,930 mt, the highest recorded weekly trading volumes since May 27, up from 1,110 mt of traded volume last week.
— Rabia Arif, Viral Shah

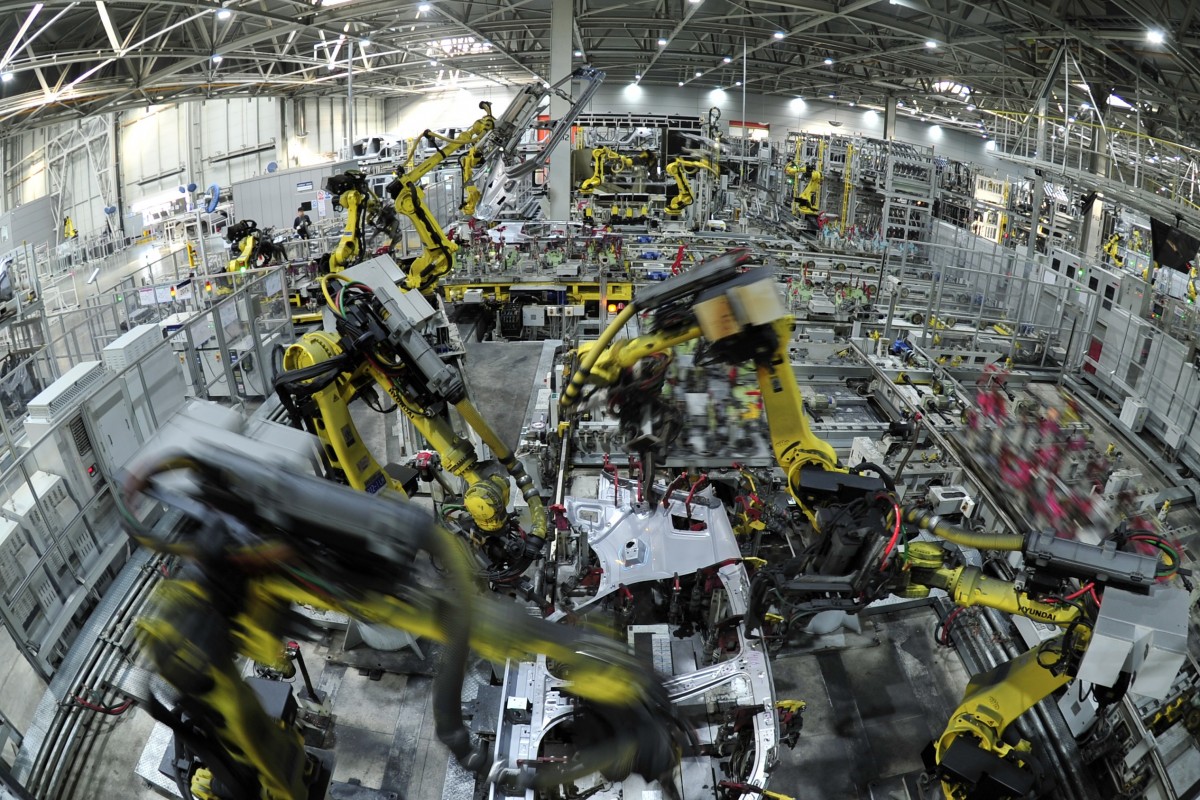
Toyota Motor cuts 2021-22 vehicle output on chip shortage, COVID-19
Japan’s Toyota Motor Corp has cut its full-year production outlook as a global semiconductor chip shortage and higher COVID-19 cases in Southeast Asia prompt it to lower output by 400,000 vehicles over September and October, the company said Sept. 10.
Toyota lowered its production forecast for the fiscal year ending March 31, 2022, to 9 million vehicles from an earlier projection of 9.30 million vehicles, the company said.
The company in a statement attributed the cuts to “a decline in operations at several local suppliers due to the prolonged spread of COVID-19 in Southeast Asia and the impact of tighter semiconductor supplies.”
The latest cuts come on top of an earlier plan to close 27 of its 28 vehicle production lines at 14 factories in Japan between Aug. 24 and Sept. 30. The reduction will affect 10 additional manufacturing lines at nine of its Japanese plants, reducing demand for automotive steel, as production of 70,000 vehicles will be lost in September, and 330,000 vehicles in October.
“We are continuing to assess expected production in October, and we will announce additional details in mid-September,” Toyota said. “Although the outlook for November and beyond is unclear, current demand remains very strong. As a result, the production plan for November and beyond assumes that the previous plan will be maintained.”
Around 30% of Japanese automakers’ factories are located in ASEAN countries, data from the Japan Auto Parts Industries Association showed.
| Toyota’s site closures: | ||
| Plant | Line | Closure period |
| Takaoka | No. 1 | Sept. 27 to Sept. 30 |
| Tsutsumi | No. 2 | Sept. 24 to Sept. 27 |
| Tahara | No. 1 | Sept. 17 to Sept. 21 |
| Miyata | No. 1 | Sept. 24 to Sept. 28 |
| Miyata | No. 2 | Sept. 24 |
| Iwate | No. 2 | Sept. 27 |
| Miyagi Ohira | Not applicable | Sept. 27 |
| Fujimatsu | No. 1 | Sept. 17 |
| Yoshiwara | No. 2 | Sept. 17 |
| Hamura | No. 1 | Sept. 17 to Sept. 21 |
Source: Toyota Motor Corp.
— Clement Choo
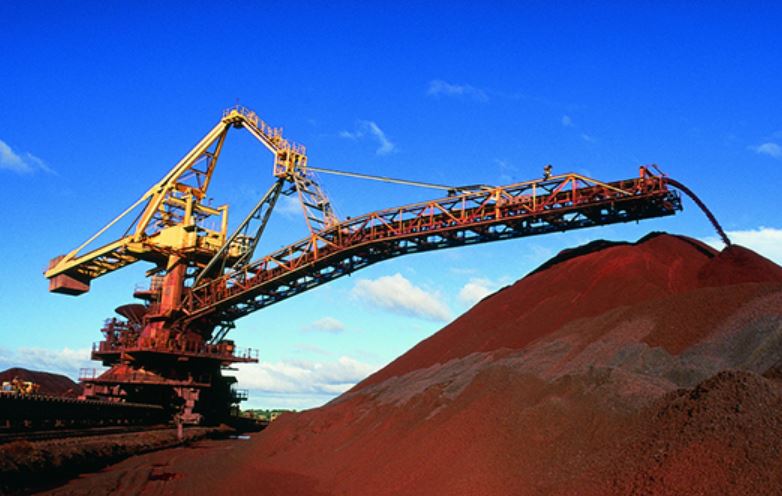
AMNS India commences iron ore mining at Odisha
ArcelorMittal Nippon Steel India (AMNS India) has commenced commercial production of iron ore at its captive mine in Ghoraburhani-Sagasahi, Odisha.
The firm’s Odisha mines have estimated reserves of 98.61 million tonnes of iron ore, Kallanish notes. The company plans to commence production at 2m t/year and subsequently ramp up to 7.16m t/y.
“We are pleased to start the mining operations at the Ghoraburhani-Sagasahi mine,” says AMNS chief executive officer Dilip Oommen. “AMNS India will continue investing in Odisha, a promising hub for Indian steel production.”
The steel company aims to transport the iron ore from the mines to its beneficiation plant at Dabuna, Odisha. The beneficiated ores will then be supplied to AMNS’s pellet plant at Paradeep.
AMNS previously commissioned its second pelletising plant complex in Paradeep, Odisha, increasing the company’s overall pellet making capacity to 20m t/y. The commissioning of the second plant at Odisha has doubled the pelletising capacity of the unit to 12m t/y. In addition, the company runs an 8m t/y plant in Visakhapatnam, Andhra Pradesh.
Sayed Aameer India


Vogel Stahl opens Maastricht unit for specialty grades
Vogel Stahl, a German service centre for hot rolled coil and sheet located on the Dutch border, has launched a new unit for speciality grades, located in Maastricht in the Netherlands.
The unit is known as Specialty Steel Sheet and Plate, but mainly offers sheet of 3-10 mm thick, Kallanish is told by Friso de Vries, managing director of Vogel Stahl. The new unit is headed by Robert Wesdijk, who in recent years was product manager at SSAB. He joined Vogel Stahl at the beginning of the year.
“Our idea is to be able to deliver quickly, to have the products right in stock, so that our customers can supply to their customers directly from our warehouse,” de Fries says. Customers can be processors and consumers, but to a large extent will be other distributors.
The house is a semi-exclusive distributor for Tata’s wear-resistant Valast 450 steel, among others, and remains open to more specialised grades from any supplier, de Vries emphasises. “We try to have any grade on coil, so that we can offer any length of sheet required,” he says. Cutting will be carried out to a large extent at associated company Laura Metaal in Maastricht.
Christian Koehl Germany

Italian beams, merchant bar prices flatten
Italian beams and merchant bar remain stable despite the declining values of rebar, scrap, and coils in the country, Kallanish notes.
Market sources say merchant bar is still traded at August prices of €460-490/tonne ($544-580) base ex-works. Large buyers are however waiting for prices to fall and have put off their purchases. Demand is said to be unreliable as buyers believe domestic material will lose €15-20/t this month. Including €420/t average size extras, local merchant bar remains at €880-910/t ex-works, sources suggest.
Section values also remain at high levels of €600/t base ex-works for the first category and €630-640/t ex-works from distributors. After the August holiday, demand has resumed significantly in September. Domestic steelmakers have full order books and are struggling to satisfy all clients’ orders. The same situation is registered for Spanish producers. Scrap price falls have not impacted domestic levels in the two countries.
In Italy, including €380-390/t average size extras, the first category of beams is at €980-990/t ex-works. Prices increase by €20/t for each subsequent category, sources say.
Natalia Capra France

Italian pig iron prices stop falling
Italian pig iron import prices are said to have rock-bottomed. Prices have decreased by $100/tonne compared to August, in line with the summer international lull, but traders and CIS pig iron exporters to Italy have now registered a surge in demand and appetite for material.
The latest transactions towards the end of last week were implemented at stable week-on-week values. Italian distributors are purchasing relatively high tonnages of CIS pig iron, to replenish stocks at the main Italian steel port of Marghera, at $550/t cfr on average for 7,000-8,000 tonnes, Kallanish learns from market participants.
The current price stability together with the surge in demand are causing sellers and traders to become more optimistic about their future activity. Mills continue buying between 1,000-2,000t of pig iron in consignment at Marghera at the equivalent of $550-560/t cfr, sources say.
According to rumours, traders are offering Donetsk mills’ material in Italy at $500-520/t fob Black Sea. Pig iron sales to northern European countries are in line with Italian prices but freight is significantly more expensive. This stands at approximately $40/t from the Black Sea to Italy and $80/t to reach northern European ports.
Meanwhile, Italian billet remains stable month-on-month at €590-610/t ($698-722) ex-works, with activity reduced. Appetite for CIS billet in Italy also remains limited.
Natalia Capra France

Acciai Speciali Terni to find buyer by end-September
A buyer for Italian stainless steel producer Acciai Speciali Terni (AST), part of thyssenkrupp, should be announced by the end of September, maybe earlier, according to Italian economic development minister Giancarlo Giorgetti. He was speaking earlier this week at a televised hearing at Italy’s parliament, Camera dei Deputati.
“As a government we are following the procedure in full transparency and have a good relationship with Thyssen … We have highlighted our expectations regarding the future of such an important and strategic company … The expectations are of a business plan that respects both employment and complies with all environmental standards, which for steel are significant in terms of impact,” Giorgetti said at the hearing watched by Kallanish.
Two Italian companies have been shortlisted for the purchase of AST, Italian steelmaker Arvedi and re-roller Marcegaglia. Both visited the facility in Terni in July. The interest shown from Posco and Baosteel seems to have faded, sources say.
In April, thyssenkrupp started the first phase of the sale, where buyers had access to some of AST’s production, sales and financial documents. This phase, which lasted two months, has been handled by JP Morgan, which is overseeing the entire process (see Kallanish passim).
Natalia Capra France
European demand supports Turkish mills’ July HRC exports
European demand, especially from Italy, supported Turkish mills’ HRC export volumes in July. This was despite the European Commission’s announcement Jan. 7 of provisional anti-dumping duties of 4.8%-7.6% on imports of HRC from Turkey for six-months, followed April 23 by definitive duties of 4.7%-7.3%, effective July 1.
Turkish mills’ overall HRC export volumes however, remained 80,000 mt lower than the same month the previous year, as exports to some of Turkey’s main HRC export markets remained below last year in July, amid trade barriers, S&P Global Platts observed from the latest monthly Turkish Statistical Institute (TUIK) data.
Turkish mills exported 43,500 mt of HRC to Italy in May, up by 16% on year, while exports to Spain totaled 26,300 mt, 20,000 mt lower on year.
Turkish mills’ July HRC exports to Portugal reached 27,100 mt, fourfold higher year on year, while exports to Belgium totaled 19,700 mt, around double on year.
Turkish mills also exported 17,600 mt of HRC to Greece in July, while exports to Egypt reached 15,400 mt.
Turkey’s other HRC export destinations in that month were: US (11,800 mt), Israel (8,600 mt), Canada (6,800 mt) and Albania (6,000 mt), the latest data showed.
Turkish mills’ hot-rolled coil prices, which reached as high as $1,200/mt EXW as of end-May, fell gradually week on week since that day. Some Turkish mills have pulled down their offers to as low $950-$960/mt in recent days, on slow demand, cheaper imports and lower raw materials pricing.
— Cenk Can
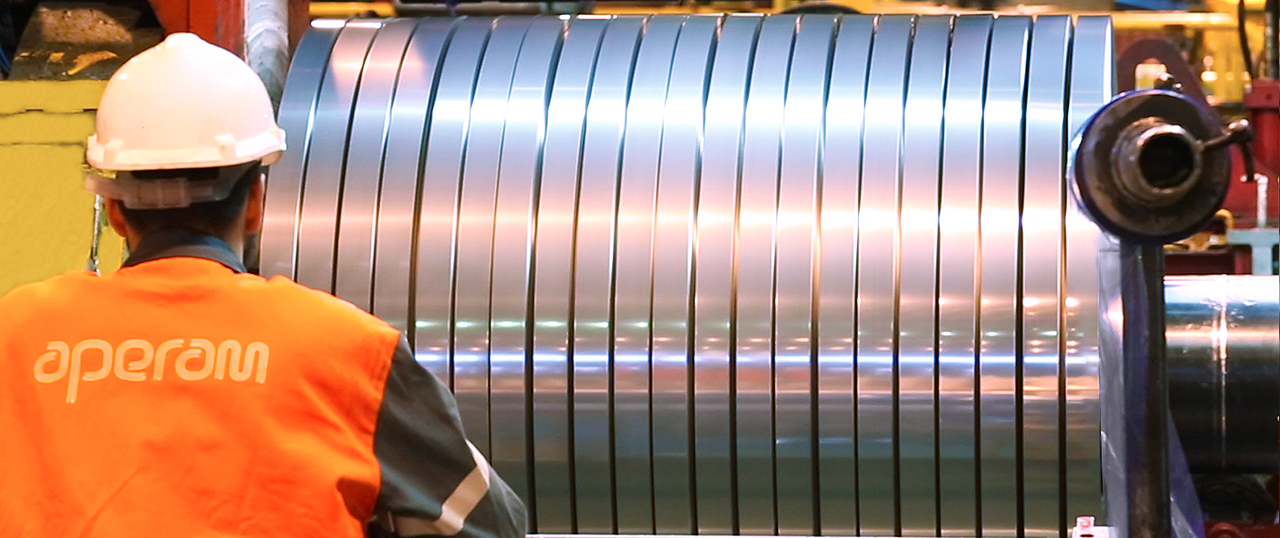
Aperam launches new rolling line at Genk
Aperam has commissioned the new annealing and pickling line for cold strip at its Genk unit, in Belgium, Kallanish notes.
The new line was supplied by SMS Group and secures an enlarged product range for Aperam. It adds material grades for the most demanding application and improves lead time and flexibility to meet market standards, the technology supplier claims. The line processes both austenitic and ferritic grades.
“This new annealing and pickling line represents the second line at Aperam’s Genk works supplied by SMS,” the supplier concludes.
Emanuele Norsa Italy
Supply catches demand, higher prices ‘new normal’: Irepas
Supply has caught up with demand in the global long products market, with lead times shortening, although prices higher than at the beginning of the fourth quarter of 2020 will be the new normal, says the International Rebar Exporters and Producers Association (Irepas). Moreover, freight rates are still significantly elevated.
Despite the return of market equilibrium, Section 232 and EU safeguards remain in force, and protected markets will continue enjoying their positions until measures are terminated, Irepas adds in its September short-range outlook seen by Kallanish.
“The slowdown in the Far East has dealt the market a strong body blow,” Irepas comments. “The Asian markets are making adjustments, but most would say that everyone is happy over there. The Indian and Vietnamese mills are exporting, while new plants in Indonesia as well as the Japanese mills are making historic profits. South Korean mills most likely will do the same.” There is strong competition between Turkish long product exports to Asia and Asian-produced material.
EU cut-and-benders’ stock levels are rising, as an increasing number of projects are being put on hold due to high prices for construction materials, including rebar. “The cut and benders are feeling a significant drop in order income and are holding their breaths to see how the EU mills will react to fewer order entries,” Irepas says. With summer holidays over, demand is however expected to recover and EU mill prices are therefore not expected to fall significantly, especially amid a lack of import alternatives.
US demand remains high but supply is gaining, although some shortages remain, especially on the West Coast. Imports cannot fill the gap due to shipping constraints. Costly freight is seeing mills offer on an fob basis. “Importers who buy on fob basis on all occasions are in for a surprise when cargoes are ready to ship. To add to the problem, most ports are full and do not wish to receive more cargoes,” Irepas observes. Credit has become an issue, with many buyers unable to insure the receivables.
Costly freight is discouraging international trade transactions, which will create short-term downward pressure on prices and long-term shortages in importing countries. Regionalisation is the current trend.
Chinese output cuts will spur the country’s demand for billet, which should support other regions, especially ASEAN producers, and could also buoy up steel pricing.
Almost all countries are looking at some type of stimulus plan and infrastructure spending, in particular, looks to continue for several years in Europe and North America.
Going forward, “some downward adjustments in the North American market may be seen and negativism is bound to spread and may affect other markets,” Irepas concludes.
Adam Smith Germany