EU action plan confirms melted/poured, CBAM, scrap focus
The European Commission published its Steel and Metals Action Plan on Wednesday, confirming it is evaluating the “melted and poured” rule, adjustments to the Carbon Border Adjustment Mechanism (CBAM) and a scrap export duty.
However, its wording on various points softened compared with the Plan draft leaked earlier in the week, Kallanish notes.
European steelmakers association Eurofer praised the Commission’s proposals but warns that “energy remains the elephant in the room” and that “further work to reduce energy costs is crucial”.
The final Plan states the Commission “will assess whether it should adapt its practice by introducing a ‘melted and poured rule’.” This compares to the draft, which stated the Commission has already decided to implement the rule in its trade defence measures. No schedule has been provided for the assessment process.
The Commission says it will “consider proposing”, by the third quarter at the latest, export fees or export duties, “if necessary”, to ensure sufficient availability of scrap in the EU. It will also assess introducing a reciprocity rule to countries that ban scrap exports to the EU or apply unfair subsidies to support their metal recycling industries.
The draft language was firmer, indicating the Commission would propose a reciprocation measure by Q3.
The Commission’s CBAM adjustments proposed in the draft have all made the cut. The difference is the timing for one of them. The Commission will issue in Q2 a communication providing analysis and options on how to address the problem of carbon leakage for CBAM goods exported from the EU to third countries.
The Commission also confirms it will strengthen the monitoring of trade flows and will proactively open investigations based on a “threat of injury”, without waiting for material injury to occur.
On energy, in the short term, the Commission is encouraging member states to use existing regulation that allows for reduction of environmental taxes and parafiscal levies, and reduction of electricity levies. The Energy Taxation Directive allows to decrease electricity taxation to zero for energy intensive industries.
The Commission is consulting member states on a clean flexibility state aid instrument based on PPAs and industry committing to consume clean electricity. It will also provide guidance to member states on the design of public support schemes for clean energy through two-way contracts for difference. This will provide temporary price relief to enable decarbonisation investments, the Commission points out.
On lead markets for steel, as announced in the Clean Industrial Deal, the Commission will propose as part of the Industrial Decarbonisation Accelerator Act to introduce resilience and sustainability criteria to foster clean European supply for energy-intensive sectors. These criteria – for example, clean, resilient, circular, cybersecure – will strengthen demand for EU-made clean products.
Finally, the Commission made the link between steel and defence, saying the former is “crucial” to guaranteeing the EU’s security and delivering on the ReArm Europe Plan/Readiness 2030 programme, also launched on Wednesday.
Adam Smith Poland

Norway to introduce its own CBAM in 2027
The Norwegian government has announced that it is planning to introduce the country’s own Carbon Border Adjustment Mechanism (CBAM) from 2027. The ministry of climate and environment and The Norwegian Environment Agency will work together on the scheme.
With its CBAM, Norway aims to prevent the European industry from losing its competitiveness and from relocating to other countries where environmental regulations are not stringent.
Andreas Bjelland Eriksen, minister of climate and environment, stated that the CBAM will set an equal price for emissions caused by the production of goods, whether they are produced in Norway or the EU, or are imported from other countries. Meanwhile, Jens Stoltenberg, minister of finance, pointed out that the CBAM will maintain the competitiveness of domestic industry, while providing incentives for other countries to cut their emissions.

European Commission to postpone sales of CBAM certificates to 2027
One result is that steel importers will no longer be obliged to purchase CBAM certificates quarterly in 2026, as was planned originally.
The amendments were presented as part of the Clean Industrial Deal proposed by the European Commission on Wednesday. This was intended to serve as a framework to tailor action in Europe’s energy-intensive industries, including steel and metals, and the clean tech sector, to support decarbonization initiatives.
The official version of CBAM amendments complied with the changes, which were leaked into the public space earlier this week.
But the delay to the beginning of CBAM certificate sales will not remove the financial burden related to CO2 emissions, it will only shift it to the next year, Fastmarkets understands.
“The changes may relieve some immediate pressure, but the financial risk exposure stays the same,” Louis Redshaw, chief executive officer of Redshaw Advisors, said. “Companies will still be [liable] for 2026 emissions but won’t need to fully account for them until 2027. This delay doesn’t remove the financial burden, it just shifts when it [will become effective].”
Another change was the introduction of a new annual de minimis threshold to exempt small importers from the CBAM requirements. This meant that only companies importing more than 50 tonnes (or 100 tonnes of embedded CO2) of net mass of goods, covered by the legislation, will have to comply.
But representatives of the steel and metals industries commented that this change would make little difference because their shipment volumes were usually well above the threshold.
European steel association Eurofer also said that, although the proposed Clean Industrial Deal and the amendments in the CBAM have managed to identify the right problems, they offered only partial solutions.
The association expected that more measures would be included in the Steel and Metals Action Plan, which was expected to be announced on March 4 during the Strategic Dialogue on Steel, organized by the European Commission.

EC unveils substantial changes to CBAM to ease industry concerns
The European Commission has proposed to tweak the timeline for the sale of carbon pricing certificates under its Carbon Border Adjustment Mechanism and move to a mass-based threshold to make the tax more streamlined and effective.
Analysts have noted that these changes, released as part of the EU’s Omnibus Package, could enhance the competitiveness of the bloc’s industry by exempting small importers and reducing the administrative burden for many companies.
Under the new proposal released on Feb. 26, importers will be able to purchase CBAM certificates starting in February 2027 rather than from January 1, 2026, to cover the emissions embedded in their imports for 2026.
“The calculation method for the certificate prices will not be affected, and certificates bought in a given week in 2027 to cover 2026 emissions will reflect the applicable weekly EU Emissions Trading System (ETS) price,” as calculated by the Commission, the document stated.
Another significant change proposed by Brussels is the adjustment of the exemption threshold, which critics have deemed too low as it is based on monetary value and applied on a consignment basis.
“A mass-based threshold of 50 mt is proposed to ensure that more than 99% of emissions remain within scope,” the document added.
This change would eliminate CBAM obligations for approximately 182,000 importers, or 90% of total importers, while still covering over 99% of emissions in scope, according to the Commission.
Simplify and strengthen
These proposals, which include several adjustments aimed at preventing unintended consequences, illustrate the complexity of the CBAM, according to Coralie Laurencin, senior director in the power and climate policy team at S&P Global Commodity Insights,
“The EU is committed to easing the paperwork for small businesses while still supporting CBAM,” she added.
“This mechanism is key to helping European industry, and the EU plans to improve and expand it to make sure it works well.”
The Commission clarified that the calculation method for the certificate prices will remain unchanged, with certificates purchased in 2027 reflecting the applicable weekly ETS price.
The price of CBAM certificates will be based on the quarterly average of the closing prices of EU ETS allowances, which will be calculated by the Commission to determine the applicable EUA price.
Raising the threshold
Importers below the 50 mt threshold will be exempt from the CBAM authorization and declaration obligations, as well as from the requirement to purchase CBAM certificates.
The primary reason for raising the exemption threshold is to reduce the impact of CBAM on small importers while simplifying the carbon tax, all while maintaining its environmental effectiveness.
“These updates emphasize the importance of a benchmark that considers not only the quantity of embedded emissions but also product terms,” a policy analyst with expertise on CBAM told Platts.
“If 99% of emissions are still covered, it confirms the environmental effectiveness of CBAM,” he added. “Although the postponement of certificate purchases is relevant, this adjustment affects only the purchasing timeline, not the surrender timeline.”
The Commission acknowledged that it considered setting a threshold based on carbon intensity but ultimately discarded that option to simplify the application process for importers.
Currently, CBAM is operational in the EU’s “transitional phase,” where importers must report emissions embedded in relevant products they bring into the bloc. However, starting Jan. 1, 2026, under its “definitive phase,” importers were expected to be obligated to purchase CBAM certificates. This proposal means these certificates will now only need to be purchased a year later.
Boost competitiveness
This represents a strategic reshaping of CBAM to support the reindustrialization of the EU, the policy analyst added.
“This potentially gives CBAM a dual role that includes enhancing competitiveness alongside its environmental objectives,” he noted.
This announcement comes amid growing calls from policymakers, politicians, and industry leaders to simplify the EU’s carbon border tax as the Commission seeks to balance industrial growth with environmental goals.
The sectors covered by the legislation include iron and steel, aluminum, fertilizers, cement, electricity, and hydrogen. The levy is designed to reflect the difference between EU carbon prices and carbon costs in exporting countries.
The price of CBAM certificates is based on the weekly average auction price of EU ETS allowances.
European carbon prices have fallen steadily in the past two weeks due to a weaker gas complex and muted demand, following a rise to 15-month highs of around Eur83/mtCO2e in late January.
Platts, part of Commodity Insights, assessed EU Allowances for December 2025 at Eur71.40/mtCO2e ($74.89/mtCO2e) on Feb. 25.
Authors: Eklavya Gupte, Irina Breilean
European aluminium, steel, iron importers speculate on effect of leaked CBAM changes
Reports of impending changes to CBAM have circulated since EU tax commissioner Wopke Hoekstra gave an interview to UK newspaper Financial Times on February 6.
But speculation increased among European importers of the goods affected by CBAM – including aluminium, iron and steel – following the February 24 leak of a document outlining proposed revisions.
The European Commission declined to comment on the document, which has been widely shared on social media and by other industry news outlets.
“We do not offer comment on leaked documents,” a European Commission spokesperson told Fastmarkets via email on February 25. “On CBAM more generally, the first Omnibus package on sustainability is indeed scheduled for discussion and possible adoption tomorrow, February 26, 2025.”
New exemption threshold for small importers
Under the current CBAM legislation, which was scheduled to come into effect from January 1, 2026, any entity importing more than €150-worth ($157) of aluminium, cement, fertilizers or iron and steel must report the CO2 emissions embedded in the incoming material.
But under the changes proposed in the leaked document, only companies importing more than 50 tonnes (or 100 tonnes of embedded CO2) of net mass of goods, covered by the legislation, will have to comply.
“A threshold set at a level of 50 tonnes will exempt the vast majority of importers from obligations under this Regulation while maintaining more than 99% of embedded emissions in the scope of the CBAM,” the leaked document was reported to say.
“This is what the European Commission should have done from the start,” Fastmarkets chief economist Stuart Evans said. “By excluding small emitters, the proposed changes bring CBAM into line with the approach taken for the [EU’s previous] Emissions Trading Scheme.”
One of the chief aims of CBAM was to reduce carbon leakage by ensuring that imported materials with embedded CO2 were subject to the same carbon taxes paid by European producers of similar material.
“It’s an easy win for the European Commission,” Evans said. “It is improved policymaking because it fundamentally doesn’t change the result. CBAM will still cover 99% of emissions but the cost of compliance will be far lower.”
The other change in the proposal was said to be a delay and simplification of CBAM certificate purchases. The leaked document proposed moving the start date of the CBAM certificate sale to February 2027, from the current official start date of January 1, 2026.
According to Dan Maleski, CBAM adviser at Redshaw Advisors, importers would have more time to comply with the requirements, but the costs associated with the emissions embedded in 2026 imports will still apply. “They will simply be incurred in 2027,” he said.
Speculation
The European Commission may have refused to comment on the leaked document, but it has already sparked speculation in the European metals trading community.
“I’m not surprised by this document,” an aluminium trader said. “CBAM in its official current form is ridiculous and clearly needs to be changed. But these proposals don’t address the real issue, which is that CBAM just looks at scope 1 emissions, which are a tiny part of the overall carbon footprint of a tonne of aluminium.”
“These proposals don’t get me too excited,” a second Europe-based aluminium trader said. “They need to include scope 2 emissions to make it an effective policy.”
The trader also pointed out that the new exemption threshold would make little difference for metal traders. “Our shipments are well above the threshold,” he said, “so this new proposal wouldn’t change the CBAM obligation for traders.”
But the trader did feel that the leaked document was significant. “It shows that CBAM won’t stand in its current form. It has started a debate,” he said.
“CBAM will happen,” Evans said. “But I wouldn’t be surprised if we see more changes down the line. The current trade policy of the US administration allows the EU to take a more muscular approach.”
Mixed reactions from the European steel sector
Fastmarkets’ sources in the steel sector shared mixed views on the latest proposals for amendments of CBAM coming from the leaked document.
“I do not think that the European Commission wants to step back from its green ambitions,” a distributor source engaged with imports of flat steel products told Fastmarkets. “There is still a lot to discuss and adjust in the current version of CBAM, and I think this is the aim of a potential proposal for amendment of the current regulation.”
A trader source, who actively imports flat steel products, also expressed satisfaction with the proposals.
But European steelmakers were more reserved. “[The amendments] will, for sure, weaken the system for a year,” a producer source told Fastmarkets.
A second producer source did not expect a significant effect on the domestic market, but the proposed legislative amendments were considered positive for the import industry because they would have one year more for preparation.
The source expressed a concern about the proposed exemption threshold, saying that “50 tonnes are nothing.”
The steel industry was currently responsible for around 5% of CO2 emissions in the EU and 7% globally, according to European Commission data.
CBAM 2.0: Is the EU making compliance easier or just postponing the pain?
Changes have been proposed to Europe’s Carbon Border Adjustment Mechanism (CBAM) that would simplify some processes, and reduce its scope, Kallanish learns from an obtained leaked draft amendment.
While CBAM will still come into force in January 2026, the requirement to purchase certificates will be delayed and payment will be simplified. Certificates will now need to be purchased from February 2027 to cover the previous year, removing the obligation to purchase certifications on a quarterly basis for the first year.
Gabriel Rozenberg, chief executive of software company Cbamboo, says that while the definitive CBAM period will still start in 2026, there is an easing up in term of cash flow and bureaucracy.
Other changes proposed will see more companies now exempt from CBAM’s scope, with the thresholds at 50 tonnes/year or less than 100 t/y of embodied CO2 emissions of imported goods. This move is believed to remove around 90% of companies from the mechanism’s scope.
EU documents show that for the first year of CBAM’s transitional phase, which only required reporting, iron and steel accounted for 69% of overall tonnages reported across targeted sectors. Given the large tonnages handled by steel importers, the minimal threshold exemption is unlikely to benefit this sector.
“The European Commission is tightening the focus on the big emissions that CBAM is designed to tamp down on,” Rozenberg notes.
He adds that some sub processes and side processing of metals and goods that have minimal emissions associated with them are now out of scope.
This consists of finishing processes that are carried out by separate installations not covered by the EU Emissions Trading System (ETS). The embedded emissions of those production processes, which are relatively low, should be excluded from the system boundaries of the calculation of emissions, the document says.
Meanwhile, penalties have also been increased for deliberate non-compliance, rising by 3-5 times.
“This is all about refining and focusing CBAM – making it stronger and clearer, while cutting out a lot of bureaucracy where that would have a low impact. CBAM will go ahead: on time, as planned, in January 2026,” Rozenberg adds.
Meanwhile, Dan Maleski, senior environmental markets advisor and CBAM lead at Redshaw advisors, tells Kallanish that while the changes may relieve some immediate pressure, the financial risk exposure stays the same. “Companies will still be on the hook for 2026 emissions but won’t need to fully account for them until 2027. This delay doesn’t remove the financial burden, it just shifts when it hits.”
“[This] grossly simplifies an overly-complex and burdensome regulation for importers of smaller quantities of goods: a positive development that made the EU CBAM appear overly-bureaucratic,” he adds. “The proposal maintains a proportionate approach to internalising the external cost of carbon pollution despite the threat of global border tariff escalations.”
Maleski also notes the uncertainty surrounding US President Donald Trump’s threats of reciprocal tariffs and how this will impact CBAM. The EU industry’s existing direct subsidy – EUA free allocation – will be reduced via free allocation reductions, so that a level playing field is baked into the mechanism.
Carrie Bone UK
Italy and France to back overhaul of CBAM to boost EU competitiveness
Italy and France underscored the need for the European Commission to reassess the EU’s Carbon Border Adjustment Mechanism (CBAM) to bolster the competitiveness of European industries amid the ongoing challenges of decarbonization.
Italy’s Minister of Enterprises and Made in Italy, Adolfo Urso, met with France’s Minister of Industry and Energy, Marc Ferracci, on Feb. 11, where they both called for the inclusion of CBAM as a key agenda item at the forthcoming EU Competitiveness Council meeting on March 6.
“We cannot allow strategic European sectors, such as steel and chemicals, which are essential for our industrial autonomy and for the economic stability of the continent, to be penalized by a system that does not take into account the real conditions of global competitiveness,” said Urso in a statement.
This comes as there has been a growing call among policymakers, politicians, and industry leaders to simplify the EU’s carbon border tax as the Commission tries to balance industrial growth with environmental goals.
“The geopolitical context requires Europe not to depend on external actors for essential materials and technologies. It is therefore crucial to correct the CBAM so that it is a truly effective tool, capable of protecting European industrial production and at the same time encouraging a sustainable transition in practice, not just in principle,” added Urso.
Streamlining CBAM
On Feb. 6, EU Commissioner for Climate, Net-Zero, and Clean Growth, Wopke Hoekstra, admitted that his team is considering excluding around 80% of EU companies from the Carbon Border Adjustment Mechanism to reduce their administrative and bureaucratic workload.
Hoekstra stated that almost 97% of all emissions covered by CBAM are produced by only 20% of companies, highlighting the need for some flexibility in implementing this carbon border levy.
CBAM is a carbon tax on emission-intensive commodities exported to the EU, currently covering the cement, iron and steel, aluminum, fertilizer, electricity, and hydrogen sectors. The levy is designed to reflect the difference between EU carbon prices and carbon costs in exporting countries.
With the definitive phase of the EU’s CBAM set to kick in on Jan. 1, 2026, importers of carbon-intensive goods will face levies based on the emissions associated with their imports.
Under the transitional phase of CBAM, which started on Oct. 31, 2023, traders must only report on emissions embedded in their imports without paying any financial adjustment. However, this mechanism will be phased in from 2026 to 2034, in line with the phasing out of free allowances in the EU ETS.
The decline in industrial and manufacturing output contributed to a reduction in the European carbon price last year. However, prices have rebounded significantly in early 2025. The suspension of Russian gas transit through Ukraine has led to higher coal power generation, pushing up demand for carbon permits.
EU Allowances averaged Eur66/mtCO2e ($68.13/mtCO2e) in 2024, down more than 20% year over year, S&P Global Commodity Insights data showed.
Platts, part of Commodity Insights, assessed EUAs for December 2025 delivery at Eur82.41/mtCO2e on Feb. 11.
Policies to accelerate steel decarbonization in Europe ‘critical’ in 2025: ArcelorMittal CEO
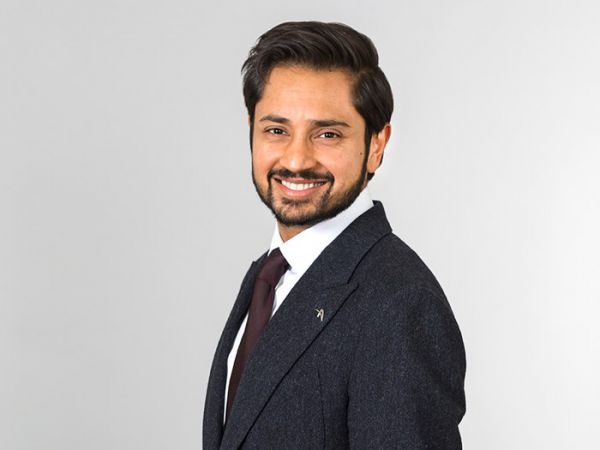
“Looking to the year ahead, while [steel] inventory levels are low and apparent demand is expected to improve, our industry continues to be characterized by global overcapacity, and we are supportive of policy to address this in our markets,” ArcelorMittal chief executive officer Aditya Mittal said in a Thursday press release accompanying the company’s fourth-quarter financial results.
“Further action is particularly necessary in Europe, which was impacted by increased imports in 2024, further adding to the pressures on European manufacturing. It is critical that we see progress in 2025 both in providing necessary emergency relief and creating a policy environment that incentivizes the investment required to accelerate decarbonization in Europe,” Mittal added.
In 2025, green steel growth is largely expected to be driven by stricter environmental regulations, increasing pressure from consumers and investors for sustainable products, and the EU’s commitment to achieving carbon neutrality, Fastmarkets reported.
ArcelorMittal provided an update on its decarbonization plans in Europe last November, pointing out that the unfavorable economic situation in Europe and uncertainty around environmental policies slow the transition to green steelmaking.
As a result, the company’s decarbonization investments in Europe are progressing at a slower pace than initially envisioned, ArcelorMittal said.
ArcelorMittal has made significant progress in decarbonizing its operations and remains committed to its green steelmaking goals, the company said in the Thursday release.
For instance, since 2018, ArcelorMittal’s absolute emissions (Scope 1 and 2) have decreased by about 50%, primarily due to footprint and portfolio optimization of some of its most carbon-intensive capacities, the release said.
In addition, electric-arc furnaces (EAFs) comprise 25% of the company’s global production, up from 19% in 2018, ArcelorMittal chief executive officer Aditya Mittal said in the release.
Since 2018, the company has invested $1 billion in decarbonization projects globally. These projects include the decarbonization of steelmaking operations in Gijón and Sestao in Spain, as well as launching ArcelorMittal’s green steel brand XCarb for recycled and renewably produced low-carbon-emission steel.
XCarb sales increased from 0.2 million tonnes in 2023 to 0.4 million tonnes in 2024, the company said.
The market for steel with reduced carbon emissions is still evolving in Europe, and sources expect more uptake of “green steel” across supply chains once environmental regulations — such as the CBAM — are implemented.
ArcelorMittal’s current decarbonization investments are focused on ramping up production of high-quality low-carbon flat products in Sestao and the new EAF construction in Gijón.
Notably, by 2026, flat steel production is targeted to reach 1.6 million tonnes per year at the plant in Sestao, where ArcelorMittal runs two EAFs. After ramp-up is completed, much of Sestao’s portfolio will be XCarb-brand low-carbon-emission steel.
According to market sources, HRC from Sestao has a carbon footprint of 580 kg of CO2 per 1 tonne of steel under Scope 1, 2 and upstream Scope 3.
Fastmarkets’ latest weekly assessment of the green steel domestic, flat-rolled, differential to HRC index, exw Northern Europe was €100-200 per tonne on January 30, stable since December 12.
Fastmarkets’ methodology defines European green steel as “steel produced with Scope 1, 2 & 3 emissions at a maximum of 0.8 tonne of CO2 per tonne of steel.”
Julia Bolotova in Brussels contributed to this report.
UK industry groups flag government policy risk
Industry association UK Steel has joined other energy-intensive industry trade associations in signing an open letter to the government detailing the risks of certain policy impacts on their respective sectors, Kallanish learns.
The letter to Sarah Jones, Minister of State for the Department for Business and Trade, was spearheaded by Arjan Geveke, director of the Energy Intensive Users Group (EIUG). As well as UK Steel, other signatories includes those from the glass and ceramics sectors, chemicals and refineries, paper and mineral sectors, as well as the GMB Union.
It says while they support the government’s ambitions to boost economic growth and meet the Net Zero target, their ability to invest in decarbonisation technologies is held back by relatively high electricity costs, policy uncertainty and risk of carbon leakage. This has often made investment in the UK uncompetitive.
It notes the UK currently has higher industrial energy costs than in Europe, the US and Asia. This is something UK Steel has flagged repeatedly, calling on the government to increase the rate of compensation for network charges from 60% to 90% to bring UK network charges closer to those in key European countries.
The letter also notes that security of energy supply is critical but the rise of “intermittent technologies”, such as renewables, generating electricity and changes in geo-political circumstances, has increased risk.
Meanwhile, it also says the UK’s Carbon Border Adjustment Mechanism (CBAM) needs significant improvement to make it effective and without loopholes. Its 2027 implementation risks trade barriers and trade diversion with the EU when the bloc’s CBAM starts in 2026.
“The 12-month gap could see detrimental impacts, as higher-carbon products that would have been imported to the EU risk being diverted to the UK instead,” it says.
If the government will not bring CBAM forward to 2026, it asks it to prepare mitigation measures, particularly around trade remedies. It also wants to ensure carbon leakage policy addresses both import and export risks.
The NESO Clean Power 2030 report includes a central estimate for gas price at 101p/therm and an ETS price assumption of £142/tonne, as well as an additional £25/tonne tariff for fossil-generated power to disincentivise exports of unabated power.
“Energy intensive industries will not be able to bear these carbon costs as long as there is no effective UK CBAM without loopholes and there are no commercial decarbonisation technologies available,” the letter states.
It also expresses concern over NESO’s proposed approach to fast-tracking grid connection for Clean Power 2030 which prioritises connecting low carbon power over industrial decarbonisation projects. It calls for industrial decarbonisation to be given the same priority as electricity decarbonisation in terms of network connections.
Carrie Bone UK

EU protectionism to weaken entire value chain
According to Italian flat steel processors, a turn on the screw on the current protectionist measures are likely to bolster European steelmakers’ price increases; however, this trend is unsustainable without a resurgence in downstream consumption, multiple sources tell Kallanish.
All eyes are on the implications of the recent European Steel Association (Eurofer) proposals submitted to the European Commission regarding the enhancement of safeguard and other protectionist measures.
“In addition to other demands, Eurofer is suggesting halving the safeguard quotas. If their requests are accepted, it would represent a significant setback for the European manufacturing sector,” states a representative from the Italian trade association Assofermet. “We are collaborating with the politicians representing us in Europe to ensure that EU officials take into account the potential impact on manufacturing. Steel consumers are likely to scale back their capacities as they will struggle to keep up with the accelerating price increases in Europe. A boomerang effect is likely to affect European producers if the EU complies with all of Eurofer’s requests. They may enjoy high prices in the future, but since this will destroy the manufacturing sector, orders will be reduced. This is what happens when only one area of the industry is protected.”
Assofermet is advocating for the European Commission to archive the existing safeguard measures and refrain from extending them beyond 31 December 2025. This is to avoid any overlap with the Carbon Border Adjustment Mechanism (CBAM), which could result in further cost increases for the EU steel processing sector (see separate article).
A large re-roller expects that Eurofer demands will be granted and is implementing price increases in line with hiking hot rolled coil prices.
A mid-size service centre also notes widespread apprehension that demands will be granted.
“This will lead to a significant decline in imports, resulting in a substantial loss of competitiveness for both service centres and our clients,” he comments.
Amidst the ongoing review of EU steel import safeguard measures, Eurofer has provided recommendations to the European Commission on making the measures more restrictive, according to Yuriy Rudyuk, partner at Van Bael & Bellis. Eurofer is proposing reducing tariff-rate quota volumes to reflect declining EU steel demand, raising the safeguard duty to 32-41%. It is capping quotas for other product categories at 15%, as was done from July for HRC and wire rod, Rudyuk indicates in a LinkedIn post.
The association has suggested removing the carry-over option and replacing residual quotas with country-specific ones. It also advocates halting new exemptions for developing countries in the final year of the measures (see Kallanish passim).
Natalia Capra France