IETA: European institutions should fast track remaining CBAM delegated acts
The EU’s carbon border adjustment mechanism is helping to catalyze new carbon pricing mechanisms worldwide, with countries implementing, expanding or reconsidering their approaches to their carbon pricing policies, Aurora D’Aprile, EU policy officer at the International Emissions Trading Association, told Platts.
However, the Commission should fast track the remaining implementing acts, she said, as clarity is needed on the calculation of carbon prices paid abroad and the discounts importers can obtain before the definitive period of CBAM starts in 2026.
“We strongly encourage the European institutions to fast track the implementing acts, and the recognition of how to calculate and to recognize the carbon price paid in third countries,” said Aurora D’Aprile in an interview with Platts, part of S&P Global Commodity Insights.
Fragmentation remains a key issue arising from the EU’s carbon levy, IETA said in a report published June 26.
“It’s a very fragmented, fast-paced space,” said D’Aprile. “CBAM has proved to catalyze carbon pricing evolution, carbon pricing initiatives and the evolution of emissions trading systems all over the world.”
However, CBAM cannot be seen as a purely environmental measure abroad, she warned, adding that the EU measure has to be considered in the context of geopolitical and climate trade discussions.
The first legal challenge arising as a response to the EU’s carbon border mechanism came in May, when Russia launched a formal dispute at the World Trade Organization against the bloc’s CBAM and emissions trading system.
Russia said the measures imposed by the EU were “discriminatory” and “do not concern a genuine environmental measure.”
“The decision by Russia to revert this issue to the WTO is of key relevance,” said D’Aprile. “The risk is that operating globally is going to become more and more complex and uncertain, and costly, due to fragmentation. This is not something that would benefit the climate.”
Carbon prices paid abroad
The EU’s CBAM regulation states that importers can claim a reduction in the number of certificates they must surrender, corresponding to the carbon price already effectively paid in the country of origin for the declared embedded emissions of CBAM goods.
The EC defines the carbon price as a “monetary amount paid in a third country, under a carbon emissions reduction scheme, in the form of a tax, levy or fee in the form of allowance under a greenhouse gas emissions trading system”.
However, the EC is still working on several implementing and delegated acts before the definitive phase of the regulation kicks in. The publication of the implementing act that is set to further address the deduction of carbon prices paid in third countries is expected by the end of 2025.
“This is a central element of key importance for all the businesses that operate globally and will have to consider this to assess their strategies and their liabilities,” D’Aprile said.
The transitional phase of CBAM runs from October 2023 to December 2025. During this period, importers of carbon-intensive products such as iron and steel, cement, fertilizer, aluminum, hydrogen and electricity are only required to report the greenhouse gas emissions embedded in their imports.

Companies are required to purchase certificates starting in February 2027 for goods imported in 2026, according to the latest simplification package put forward by the EU. However, market participants have previously said that several challenges remain ahead of the definitive period.
International credits
The regulation on reductions for carbon prices paid in third countries only extends to compliance carbon schemes such as emissions trading systems or carbon taxes and does not mention international carbon credits or Article 6 units under the Paris Agreement.
“The role of international credits is something that IETA encourages to be put into the discussion,” said D’Aprile.
She welcomed the EC’s decision to greenlight the use of international credits and Article 6 units toward meeting the bloc’s 2040 climate targets, saying that this was a positive signal.
The amendments to the bloc’s climate law earlier in July will allow the “limited use of high-quality international credits” under Article 6 of the Paris Agreement starting from 2036. The regulation will allow for 3% of the bloc’s 1990 net emissions to be counted toward the 2040 target.
The use of these Article 6 units toward obtaining discounts under the EU’s carbon border levy, however, has not been addressed by the EC.
“This is something that may, in the future, enter into the conversation, but as of now, the priority should be how to recognize the carbon price effectively paid,” D’Aprile said.
The role of Article 6 will likely become part of the CBAM discussion in the future, she said, because the EU’s trade partners are already considering Article 6 in their compliance mechanism.
Singapore and Japan have recently issued policies that may encourage the trading of Article 6.2 carbon credits, with Japan establishing a tailored system, the Joint Crediting Mechanism, which only accepts bilateral methodologies approved by JCM partners.
Once the regulation enters the definitive period, the price of CBAM certificates will be calculated based on the quarterly average of EU Allowances in the first stage, before the calculation moves to a weekly average.
Platts assessed the weekly average price of EU Allowances for the nearest December 2025 delivery at Eur70.71/mtCO2e ($82.66/mtCO2e) on July 11.
EU plate, slab spot liquidity drops amid summer lull
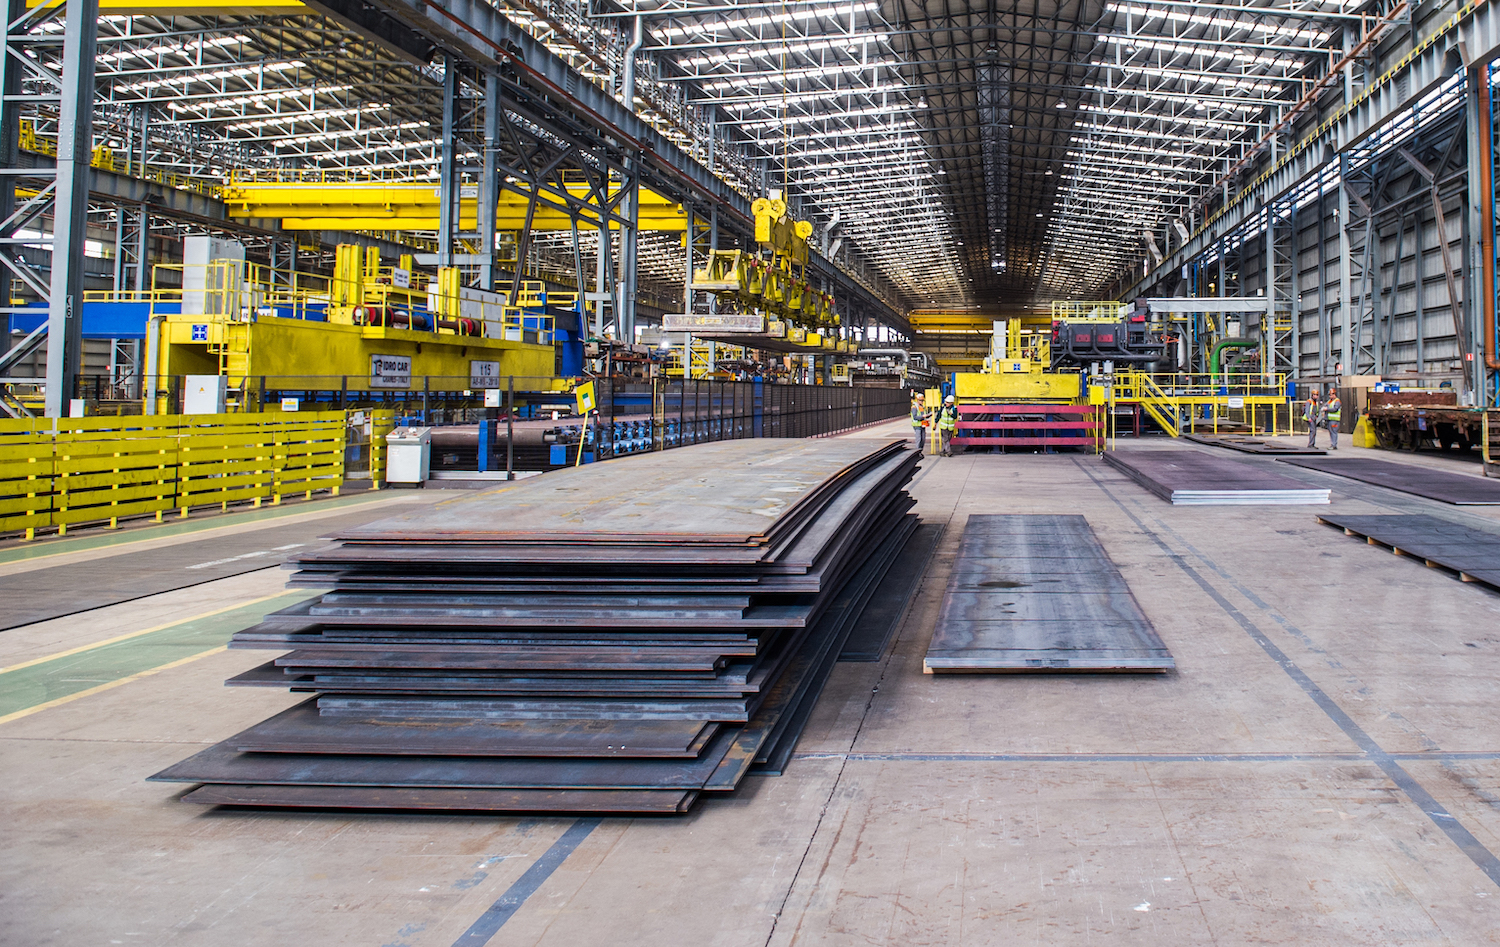
European heavy plate and slab prices remained stable July 11, as sources shared expectations for limited import interest ahead of CBAM and dwindling summer demand.
“We are having discussions for re-stocking needs, but we have to give discounts to get these orders,” one mill source said, who, despite the reduced buying interest, reported otherwise stable market conditions and forward views. “It’s not surprising, there is not so much competition in the market from imports.”
The same source also referred to minimal interest in imported plates due to the upcoming Carbon Border Adjustment Mechanism.
A trader also recognized a preference for domestic heavy plates and slabs. He said, “Imports are not pleasant and not too attractive considering unloading and transport costs. It will be similar to re-rolling.”
Looking forward, the trader said, “After summer, everyone will try to move domestic prices up, and for imports, everyone is concerned about CBAM, but unless imports have guaranteed customs clearance for this year, buyers won’t budge.”
A service center source also pointed to quieter spot conditions on the week, citing summer holidays and a general slowdown across all construction and automotive-based industries in Europe.
Platts assessed plate at Eur595/mt ex-works Italy and in Northern Europe at Eur650/mt ex-works Ruhr, both stable on the day.
Platts assessed slab at $495/mt CIF Italy, stable week over week.

EUROMETAL president says CBAM clarity vital as Europe steel trade enters transition phase
The Carbon Border Adjustment Mechanism (CBAM) will reshape European steel trade in the coming year, but the market still lacks key details needed for long-term planning, Alexander Julius, president of EUROMETAL, told S&P Global Commodity Insights in an interview.
Alexander said that the future of European trade policy lies in stronger federation-wide coordination. “Our intention is to further strengthen the joint voice of federations. We need more and more of one voice toward Brussels,” Julius said.
Market seeking DDP clarity
Julius emphasized that for most of Eurometal’s members, steel trade into Europe already occurs on a DDP (delivered duty paid) basis — a trend that CBAM is expected to accelerate.
“Our business has always been DDP — not a lot of CIF/CFR at all,” he said. “The industry wants DDP solutions. But to deliver those, we need full clarity on CBAM.”
Julius noted growing concerns from exporters within the EU, especially regarding necessary potential tax claims when exporting to non-ETS countries and the complexity of tracking embedded emissions downstream.
“If CBAM is digested as a tax, but you’re exporting to a country without an ETS, will there be a way to claim it back? That’s one of the unresolved questions,” he said. “It’s becoming another cost factor that needs to be built into calculations but then the question of competitiveness remains.
No premium, but ‘grey steel’ pricing may shift
Asked whether CBAM could lead to more EAF-based imports into Europe, Julius said there would not be a “green steel premium” but rather a premium for more carbon-intensive products.
“For blast furnace products, CBAM costs will be higher. You may see a kind of ‘grey steel premium’ emerge instead. The market will adapt,” he said.
Julius pointed to companies using both BF and EAF production routes, and suggested that, as mass-balancing and emissions accounting practices evolve in view of the EC plans to avoid resource shuffling, trade dynamics will be affected.
“In the end, CBAM won’t stop trade — but it will change its shape,” he said.
Industry still waiting for benchmarks
With no final EU CBAM benchmark and default values published yet, as well as the speculative EU ETS development until the end of 2026, carbon cost calculations remain a challenge for steel buyers and distributors. Julius said Eurometal members are relying on mill-reported emissions, ETS prices, and internal know-how to anticipate likely CBAM values.
“We’ve dealt with this in detail at the company level. We expect the benchmark to be within a certain range — close to ETS levels — but more certainty is essential,” he said.
He added that some buyers want CBAM costs broken out as a line item, while others prefer a bundled, inclusive price. “It depends on the customer — but everyone wants the calculation formula to be consistent and transparent,” Julius said.
As the EU’s CBAM looms on the horizon of 2026, many have suggested that there could be a deluge of imports, as buyers attempt to avoid the mandatory carbon reporting requirements from the legislation.
Industry consolidation and EUROMETAL’s evolving role
Looking ahead, Julius said the European steel landscape was becoming increasingly regionalized, with more consolidation in downstream sectors and a shift toward local sourcing.
Reflecting on Eurometal’s 75th anniversary event, Julius said the feedback had been overwhelmingly positive, despite some suggestions to include more voices from the distribution segment.
“A few people criticized that we didn’t have enough distribution businesses represented. But our speakers — from Henrik Adam to Marcegaglia — were very well received,” he said. “The dinner and cocktail night before was very important — it helped bringing people together. Attendance was strong, and the feedback we’ve had so far has been great.
EUROMETAL’s presence is getting stronger, more companies and associations are becoming part of our federation, and we gain an increasing market picture enabling is to better represent the interest of our industry.

European Commission launches public consultation on CBAM extension to downstream products
The European Commission launched a public consultation on a possible extension of the Carbon Border Adjustment Mechanism (CBAM) to include specific downstream products. This consultation is a key step in evaluating the mechanism’s next phase and is highly relevant for all actors across the steel and metals value chain.
Why this matters?
The current CBAM regulation covers basic materials such as steel, aluminium, cement, electricity, and fertilizers. However, to prevent carbon leakage further down the value chain, the Commission is now exploring whether CBAM should also apply to downstream products — goods that are manufactured using CBAM-covered inputs, such as processed steel components, machinery, or fabricated aluminium items.
This follows a clear signal from the European Steel and Metals Action Plan, which called for the inclusion of steel- and aluminium-intensive downstream goods to protect the EU’s industrial base and climate objectives.
What’s at stake?
EUROMETAL encourages its member companies and national federations to participate in this consultation and share concrete feedback on how an extended CBAM might affect supply chains, trade patterns, compliance costs, and competitiveness in the steel distribution and service centre sectors.
Deadline for feedback: 26 August 2025
How to participate?
You can submit your contribution directly on the European Commission’s portal. More information about this consultation can be found here:
European Parliament and Council agree on CBAM simplification
The European Parliament has announced that, together with the European Council, it has agreed on the proposed technical changes and simplifications made to the EU’s Carbon Border Adjustment Mechanism (CBAM).
The changes will introduce a new cumulative annual CBAM threshold of 50 mt per importer, exempting 90 percent of importers – mainly small and medium-sized enterprises (SMEs) and individuals importing small quantities of CBAM products – from CBAM rules, while still covering 99 percent of emissions from iron, steel, aluminum and cement imports. The changes will also simplify the authorization process for declarants, the calculation of emissions and the management of CBAM financial liability, while strengthening anti-abuse provisions. These changes aim to reduce the administrative burden for SMEs and occasional importers.
“The CBAM is designed to prevent carbon leakage and protect Europe’s cement, iron, steel, aluminum, fertilizer, electricity, and hydrogen industries. We have answered calls from companies to simplify and streamline the process and exempted 90 percent of importers of CBAM goods to facilitate competitiveness and growth for our businesses. As the CBAM will still cover 99 percent of total carbon emissions, we have maintained the EU’s environmental ambitions and remain fully committed to a just transition and to achieve climate neutrality by 2050,” Antonio Decaro, rapporteur of the parliament, stated.
Still, the changes have to be endorsed by both Parliament and Council. They will enter into force three days after publication in the EU Official Journal.

CBAM will hit EU hard at first
European steel industry players will struggle with the Carbon Border Adjustment Mechanism (CBAM) into 2026, when the measure takes full effect, participants said at Kallanish Europe Steel Markets 2025 in Amsterdam on Tuesday.
“I am not optimistic that 50% of players are prepared,” noted Stanislav Zinchenko, chief executive of Ukrainian consultancy GMK Center. “When your normal competence is that of a trader, people are not prepared in their business processes, and still do not understand this game,” he added, likening the buying of CBAM certificates to financial trading.
He predicted “chaos at the start”, and highlighted that CBAM will be less of a trade hurdle and more of a technical barrier to the supply chain on a trader and consumer level.
Tata Steel Nederland director markets, pricing & services Ronald de Haan said complications are not unusual in the early stages of a new measure.
“CBAM will be with us, not for years, but for decades,” de Haan noted. The mechanism needs enforcement tools and EU steelmakers will push for that. In an example of the complexity of the value chain, he wondered “if a reroller in Turkey buys hot rolled coil [substrate] from China, is he aware of those costs” when offering his final product into the EU.
ArcelorMittal Europe head of climate change – governmental affairs Stéphane Tondo reminded the panel that “CBAM is not meant to be a trade measure, and we Europeans should not expect it to protect us from clean steel coming from elsewhere”.
Christian Koehl Germany
CBAM-prompted imports may deepen oversupply in EU
Some European stainless steel buyers expect an influx of material into EU ports towards the end of 2025 as importers attempt to avoid the added administrative and cost burden of CBAM.
The European Commission’s emissions-based Carbon Border Adjustment Mechanism is currently scheduled for a full rollout from January 1, 2026. Under the current plans, registered declarants – those approved by the Commission to import material – will have to report all imports and their carbon content from that date.
They will also have to buy and submit CBAM certificates to reflect the greenhouse gas emissions generated during the production of the goods they bring into the EU. This means they will effectively pay a charge based on the quantity of carbon emitted during the manufacturing process in the country of origin.
Under changes proposed by the Commission in February, the purchase of CBAM certificates would be delayed until February 1, 2027, however. This is part of a package of measures which aim to simplify the process and further smooth a transition period which started in October 2023. Approval of the amendment was expected as the Stainless Steel Review was published.
The need to report stainless steel imports and their emissions will remain, regardless of the amendments’ approval. Consequently, some MEPS respondents anticipate that import volumes will grow in quarter four. However, others highlight that weak demand may mitigate any upturn in imports.
Any increase in third-country shipments would be an unwelcome development for European mills. MEPS respondents say that the use of Indonesian-origin slabs as a basis for coil production, and a reduction of scrap prices, may be helping to preserve certain producers’ profit margins. Nonetheless, low selling prices are challenging their profitability.
Inventories are rising, meanwhile, due to a combination of low demand and the loss of export business in the United States, following the implementation of 25% Section 232 import tariffs on March 12. Changes to the EU’s import safeguard measures have done little to reduce imports in recent weeks.
The UK plans to roll out its own CBAM scheme in 2027. The EU and UK have agreed to work towards linking their Emissions Trading Systems, effectively exempting shipments between the two from CBAM’s associated cost and administrative burdens.
Mills under price pressure
The quarter one financial results of Europe’s largest stainless producers indicate that oversupply will continue to apply downward pressure to stainless steel prices.
Acerinox reported a 29% quarter-on-quarter increase in melt shop production, to 512,000 tonnes, from its consolidated operations in Europe and the United States. This came despite an acknowledgement that inventories had increased amid pressure from imports, which have increased their share of the European market to 22%.
Acerinox expects US tariffs to improve the profitability of its US operations. However, chief executive Bernado Velázquez raised concerns that many of the exports that previously ended up in the US, and that have lost competitiveness as a result of the tariffs – including European exports – may now end up in the EU.
Outokumpu’s stainless steel deliveries, in Europe, rose by 10.8% quarter-on-quarter and 5% year-on-year, to 318,000 tonnes, in quarter one. The value of the steelmaker’s sales rose by a lesser 9.8% quarter-on-quarter and 3.4% year-on-year due to reduced selling prices.
Shipments from Aperam’s stainless and electrical steels division rose from 401,000 tonnes to 421,000 tonnes quarter-on-quarter. Nonetheless, its earnings before interest and tax declined by 30% quarter-on-quarter and 67% year-on-year, to EUR34m. The decrease was attributed to “intensive pricing pressure in Europe”.
All three producers forecast a more profitable quarter two. However, Aperam chief executive Timoteo Di Maulo said that reliable projections for the remainder of the year are “challenging in the current volatile environment”.

European long steel market remains subdued amid summer slowdown, CBAM uncertainty
The European domestic long steel market remained subdued in the week to June 4, as demand failed to recover following recent holidays, with participants citing seasonal slowdown and regulatory uncertainties – particularly around the Carbon Border Adjustment Mechanism – as key overhangs.
Tradable values for rebar were largely unchanged week over week, reported at Eur650-660/mt delivered to Germany, and Eur625-630/mt delivered to Belgium. One trader noted ex-works levels around Eur615-620/mt in Benelux, reflecting limited transactional movement and persistent buyer caution.
“Mills are struggling to keep the price — it’s not brilliant,” said a trading source. “Demand is weak for many reasons; the economy is what it is, and there’s still no clarity on CBAM implementation. We still don’t have benchmark values to work with.”
Medium sections were heard traded at Eur785/mt delivered Benelux for volumes around 2,000 mt, with broader tradable values seen at Eur785-790/mt delivered.
Across the long segment, participants noted the combination of May holidays and the early onset of the summer slowdown had stalled buying appetite. “It takes more time for spending approvals to come through, and activity is slower than expected,” one distributor noted.
Carbon-accounted offers continued to face resistance, with reported premiums between Eur30-65/mt deemed unworkable in the current market. “It’s a good idea, but it’s not working,” one source said. “People are paying for certificates, but the product is still the same.”
Platts assessed rebar at Eur620/mt ex-works Benelux, down Eur5/mt on the week. Platts assessed medium sections at Eur780/mt delivered Benelux, stable on the week.
Meanwhile, Platts assessed both carbon accounted rebar and carbon accounted medium sections at Eur30/mt, stable on the week.

EUROMETAL gathers Flat SSC leaders in Hamm to tackle industry challenges
Last thursday, EUROMETAL brought together 35 participants from leading German-speaking Flat Steel Services Centres companies in Hamm for a key meeting of the “SSC Arbeitskreis”. The event focused on the strategic challenges ahead for the sector.
The session was opened by Arbeitskreis Chairman Thomas Niederhofer (Knauf Interfer) and Head of Sales Automotive Bernd Tremmel (Becker Stahl-Service), who warmly welcomed the group.
The agenda covered essential topics including a compliance briefing by Alexander Bartsch (Henseler & Partner), an overview of the current challenges in the EU steel market by Alexander Julius (EUROMETAL), and legal insights on CBAM, embargoes, sanctions, and customs duties from Lars Hillmann (Cattwyk).
Stefan Grüll (S1Seven) introduced the role of digital mill certificates in supporting sustainability traceability across the steel supply chain.
Thomas Niederhofer (EUROMETAL) also shared the first ideas from the working group on cargo securing for vertically loaded slit coils.
EUROMETAL President, Alexander Julius emphasized the unknown variables in CBAM, urging companies to factor these into contracts and negotiations for 2026. He also highlighted EUROMETAL’s ongoing advocacy to ensure steel derivatives are properly included in CBAM taxation, and safeguard measures.
The day concluded with a guided visit to Becker Stahl-Service GmbH in Bönen.
These are decisive times for our industry. EUROMETAL will continue to be a strong voice to shape the path forward — with and for our members.


EU Parliament approves proposed CBAM simplifications
The European Parliament (EP) has approved proposed simplification changes to the Carbon Adjustment Border Mechanism (CBAM), Kallanish learns.
The changes, first proposed by the European Commission in February, as part of its Omnibus simplification package, include a new lower 50-tonne threshold. While the changes remove 90% of small companies from being liable for the carbon tax, the vast majority of steel companies remain within the scope.
Now approved, EP will move to finalise amendments with the European Council on the regulation.
Despite these changes being approved, Belgium-based climate think tank Sandbag and steelmakers’ association Eurofer have separately released statements calling for further changes.
Sandbag has released a position paper outlining reasons why CBAM should be extended horizontally to more products and vertically to include key precursors such as coke, lime and ferro-silicon, alongside international transport emissions. It says this is essential to close remaining emissions gaps.
This expansion is also needed to support the phase-out of free allocation under the EU Emissions Trading System (EU ETS), which currently fails to incentivise decarbonisation in the EU, it adds.
It has also called for scrap to be included within CBAM’s scope.
Eurofer meanwhile notes CBAM remains full of loopholes that need to be fixed. Failure to do this risks undermining decarbonisation investments, accelerating deindustrialisation, favouring production in third countries, and failing to cut global emissions.
It has created a toolbox on how to fix these loopholes. This includes keeping free allocation for exports to avoid carbon leakage in global markets. It notes that 70% of EU steel exports go to countries with no carbon pricing, therefore making European steel uncompetitive.
Other calls include extending CBAM to steel-intensive downstream goods with a simplified emissions calculation system for complex products.
Additionally, it says the origin of CBAM goods must be set where the steel was melted and poured.
It also notes a loophole where steel-intensive goods such as car components, machinery and household items can be imported without paying any carbon price, which puts EU producers of these products at a disadvantage.
Carrie Bone UK