Assofermet criticises EC CRC anti-dumping investigation
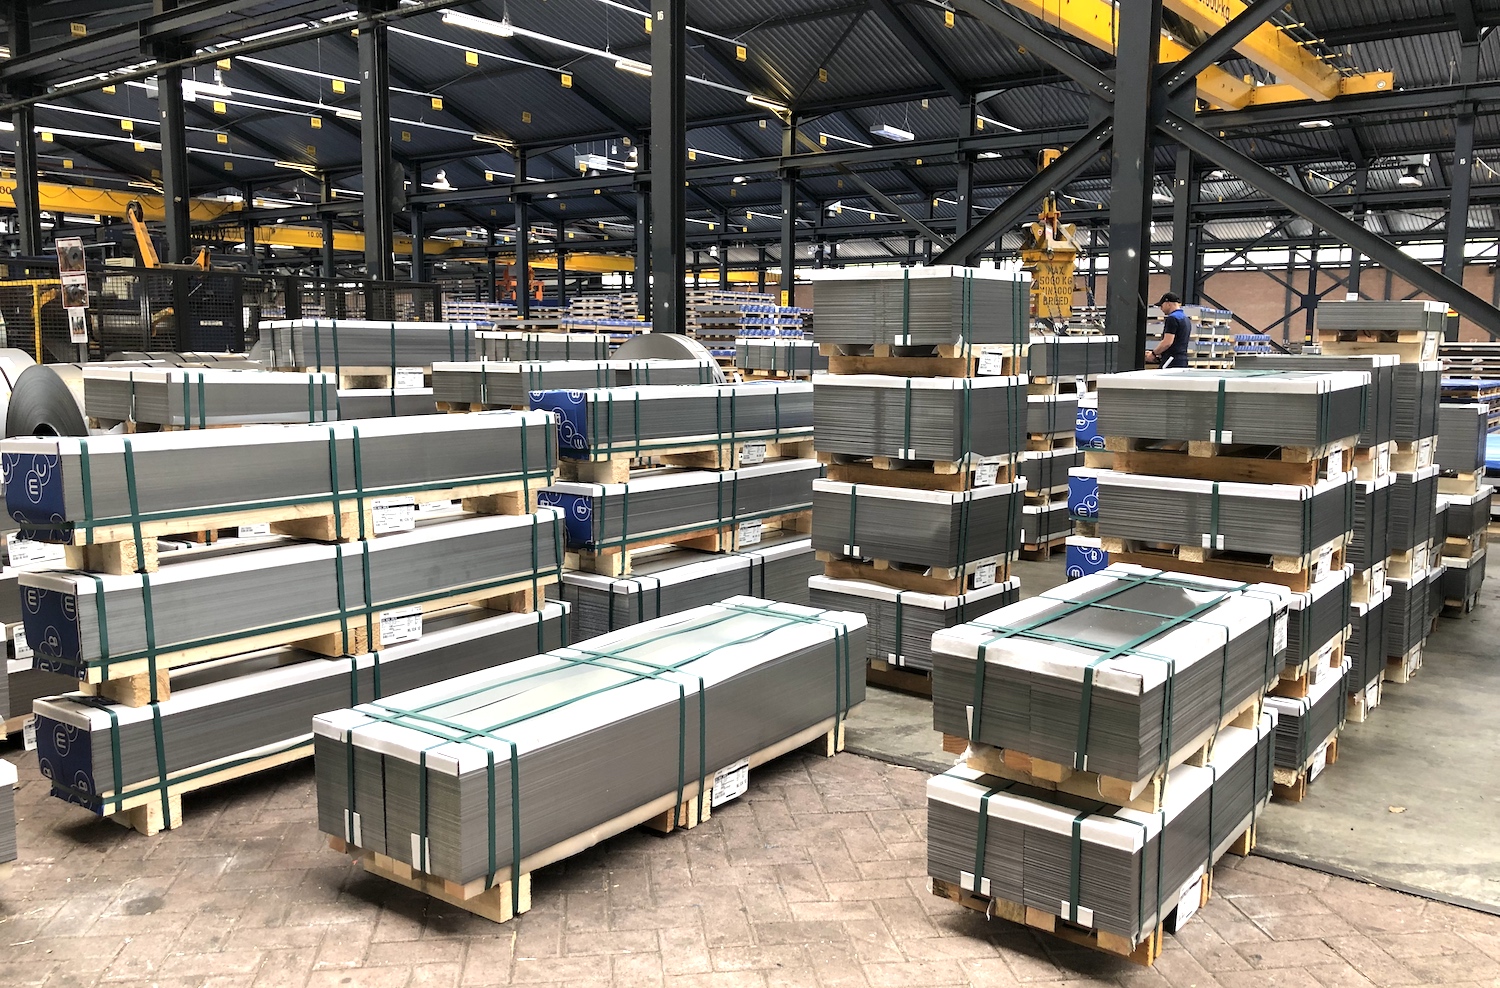
Italian steel distribution association Assofermet has expressed concern over the European Commission’s initiation of an anti-dumping (AD) investigation into cold-rolled coil (CRC) imports, alleging an insufficiency of domestic quality and supply of the products under investigation.
Assofermet “expresses strong disappointment and concern” in relation to the European Commission’s opening of the investigation last week, citing “higher quality standards” associated with relevant producers; downstream dependence on the targeted CRC imports; and existing overlaps with other trade instruments like the existing safeguard protections and anticipated impacts from the fiscal stage of the Carbon Border Adjustment Mechanism (CBAM) – effective from January.
The association condemns what it views as the progressively expanding, burdensome, and complex nature of the European steel trade defense framework, stating that compounding restrictions on European manufacturing’s access to international steel raw materials “significantly reduces the competitiveness of the Union’s manufacturing industry in international markets, with structurally negative impacts on both the economy and employment.”
Assofermet calls on the European Commission to take “a more balanced assessment” of the EU’s steel trade protection framework and its influence on the “stability of the industrial supply chains,” and at minimum exempt existing import flows with arrival before 2025’s end from any imposition of retroactive duties.
The anti-dumping investigation covers CRC imports from India, Japan, Turkey, Vietnam, and Taiwan, China and was prompted by complainant Eurofer on behalf of EU steel producers. Eurofer provided evidence that CRC imports have increased in both absolute volume and market share, alleging injury to the EU’s domestic industry. As part of its complaint, Eurofer highlighted relevant export controls imposed on raw materials used in CRC production processes, which are not accounted for in international export prices, indicating market distortion.
European producers have preferred to focus on steel products other than CRC due to the low domestic margins premising the Commission’s investigation, McCloskey understands from conversations with market participants, seeing producers instead prefer to process value-added hot-dip galvanized (HDG) steel straight from their hot-rolled coil (HRC) portfolio. This deprioritisation of CRC alleviates additional energy costs inherent to cold-rolling processes and allows mills to weight their allocations to stronger margin products, important in a time of crisis for the wider European steel sector and the role played by high energy costs.
Market participants expect that potential new AD measures could have a significant impact on European importers and the attractiveness of international CRC, as trade protection for CRC has traditionally been limited to safeguard provisions without heavy AD or anti-subsidisation exposure.
The European Commission committed to replacing the EU’s steel safeguard mechanism – expiring in 2026 as per WTO rules – earlier this year with a long-term protective instrument in its Steel and Metals Action Plan (SMAP), with early proposals now expected in the first half of October. Under the SMAP the Commission also relaxed the legal threshold for the initiation of trade defense investigations to a “threat of injury” to better facilitate more proactive trade defenses, and has launched import monitoring tools for the bloc’s imports.
The European Economic and Social Committee (EESC) – which advises the Commission via consultation with industry stakeholders – released its official opinion on the SMAP 18 September, generally supporting the Commission’s “step in the right direction” but emphasising “that immediate action is required.”
Part of the EESC’s recommendations to the Commission and most relevant to wider AD investigations, is for a more selective application of the ‘lesser duty’ rule, and the introduction of a ‘melted and poured’ element across EU trade defence measures to better shield EU industry from global overcapacities and circumventionary evasion of its steel trade protections.
Benjamin Steven Journalist, Steel


Elmarakby Steel targets EU market edge with carbon reporting
Egyptian steel producer Elmarakby Steel has positioned itself for enhanced competitiveness in European Union markets by voluntarily reporting carbon emissions of 0.44 tons of CO2 per ton of finished steel under the EU’s Carbon Border Adjustment Mechanism for the first and second quarters of 2025, the company said Sept. 21.
“Our products’ carbon footprint was calculated at 0.44 t CO2 per ton of finished steel, including direct and indirect emissions for Q2-2025,” it said.
This achievement aligns perfectly with Elmarakbysteel’s commitment to voluntarily report its carbon emissions and footprint, accelerating its decarbonization strategy and meeting the needs of its customers in markets worldwide, the company said.
The Carbon Border Adjustment Mechanism is the EU’s tool to put a fair price on carbon emitted during the production of carbon-intensive goods that are entering the EU, and to encourage cleaner industrial production in non-EU countries.
Steel imports with lower carbon footprints will face reduced carbon adjustment charges, potentially making Egyptian steel more competitive in EU markets compared to higher-emission alternatives from other regions.
The voluntary reporting also positions Elmarakby to attract environmentally conscious customers and potentially access green financing options that are increasingly available to low-carbon industrial operations. As global steel buyers implement their own decarbonization targets, suppliers with verified low-carbon credentials are likely to command premium pricing and preferential contract terms.
Elmarakby Steel, meanwhile, recently commissioned SMS group to upgrade its minimill to increase capacity and reduce operating costs.
The upgrade will expand the company’s product portfolio and boost the production capacity of the minimill from 400,000 mt/year to 460,000 mt/year of rebar and wire rod.
Platts, part of S&P Global Commodity Insights, assessed Turkish exported rebar at $534/mt FOB Sept. 19, down $1/mt day over day.

EU HRC markets struggle under CBAM uncertainty
European hot-rolled coil prices continued their near-term stability on Sept. 22, as market participants cited CBAM uncertainty and poor downstream demand.
“There is no confidence from the downstream. Nobody knows how big the fee for CBAM will be for next year, and if demand increases a little bit, it will push domestic prices higher,” said a service center source.
Wider conversations in the market continued to point toward significant uncertainty and unease over the lack of forward price discovery, largely attributed to a lack of information surrounding CBAM charges.
“EU producers will take advantage of the moment and try to raise prices, so nothing will change until demand in Europe returns to normal. If there is no demand the price falls,” said a trader, also discussing the difficulty in negotiating contracts for 2026 due to the unknown CBAM component.
A distributor also referred to the safeguard quotas as further limiting market liquidity and buying interest.
“Buyers are largely purchasing hand-to-mouth, and while imports remain theoretically competitive, they are unattractive due to the quota risks,” the distributor said, noting an increase in speculative inquiries from buyers but maintaining that market sentiment continued to be weakened by poor downstream demand.
Platts assessed Northern European HRC at Eur570/mt EXW Ruhr, and Southern European HRC at Eur555/mt EXW Italy, both stable dau pver day.
Platts assessed imported HRC at Eur480/mt CIF Antwerp and Eur480/mt CIF South Europe, both stable day over day.

Assofermet urges effective EU response to US tariffs
Italian steel trade association Assofermet is warning that new EU policies in response to tensions with the United States could severely disrupt supply chains and weaken Europe’s manufacturing sector.
“After months of negotiations, the agreement reached between the EU and the US has not resolved the issue of tariffs on steel and aluminium, which have remained at 50% since 4 June … This situation risks generating a massive relocation of exports to Europe, putting pressure on the EU market,” Assofermet says in a note sent to Kallanish.
The association is renewing its appeal to Italian and European authorities to ensure that any new measures remain balanced, proportionate, and effective, protecting not only European steel producers but also downstream users. At stake, the association stresses, is the competitiveness of the European industry and its ability to remain integrated within global trade flows.
The debate on steel is focused on the replacement of the current safeguard system, set to expire at the end of June 2026. The European Commission is to propose a new, allegedly more balanced, trade defence instrument. Assofermet is instead suggesting a mechanism based on annual and quarterly quotas, not tied to specific exporting countries. Such a framework would better balance the protection of Europe’s steel producers with the need to guarantee sufficient supply for EU manufacturing.
The association warns that excessive import restrictions could have “devastating effects” on the European industry, already under strain from high energy costs and the introduction of the Carbon Border Adjustment Mechanism (CBAM).
Earlier this week, the association urged the European Commission to rethink the protectionist and environmental policies currently under discussion, underlining the necessity to ensure a balance between environmental goals, industrial resilience, and the protection of Europe’s metals and steel value chain. Without such a balance, the association warned, the EU risks undermining the competitiveness and sustainability of its own manufacturing base.
Natalia Capra France
Development of regional ETSs possible antidote to EU industry’s CBAM woes
CBAM will enter its definitive phase on January 1 2026, and is intended to level the playing field between domestic producers that are exposed to the EU’s Emissions Trading System (ETS) and international producers that are not under the same requirement.
Market participants have frequently pointed to loopholes within the policy that they say threaten the competitiveness of Europe’s industry and fail to deliver on decarbonization objectives.
Sources have pointed to the so-called “scrap loophole” whereby remelted aluminium scrap is allocated a zero emissions rating under CBAM. This means that non-EU producers can avoid CBAM costs, while EU producers are still subject to the ETS, potentially leaving a gap ripe for exploitation.
In addition, the “downstream product loophole” is another challenge, with some arguing Europe could be exposed to an influx of downstream products as it has no CBAM liability, potentially resulting in a competitive disadvantage for EU producers.
Other challenges include continuing uncertainty around the policy’s ambit, open consultations, and questions around when and if to include Scope 2 emissions.
But the development of ETSs in other regions could offer a solution to some of the issues that have been raised in relation to CBAM.
Instead of paying a tax on embedded emissions in imported goods, the carbon price would be paid within the origin country’s ETS, with carbon tax revenue staying in that region rather than being spent in the EU.
“In the case of Turkey, there is a direct linkage with what’s happening to EU policy and market,” Fastmarkets’ Head of Carbon Modeling, Shyamal Patel, said during the panel.
“The actions of European policymakers are certainly influencing their international counterparts – really in some ways that is a step towards the ideal,” Patel added.
The Turkish ETS is set to enter its two-year pilot phase in 2026. Under Turkey’s Climate Change Mitigation Strategy and Action Plan (CCMSAP), which outlines the country’s plan for achieving net-zero emissions by 2053 – it was noted that the development of its ETS would align with the EU’s ETS and its CBAM.
“In an ideal world, CBAMs would not be needed – there would be domestic carbon pricing in every jurisdiction, and those carbon revenues would be recovered at home – in Turkey, India, China and beyond. CBAM would be much less of a concern in all our minds,” he added.
This sentiment was echoed by Clement Silva, Partner at Osrich SA, on the panel.
“The UK CBAM should be implemented in 2027… So, what they are trying to do is to link it to EU CBAM… The same for Turkey’s [ETS], and Serbia has also created their own strong emission scheme,” Silva said.
In April, the UK published draft primary legislation for its CBAM, which will become effective from January 1 2027, using the previous quarter’s average UK ETS auction price to calculate liabilities under the mechanism. And, in May, the UK and EU agreed to work toward linking their ETSs.
Serbia, meanwhile, is currently preparing to introduce a carbon pricing mechanism through the establishment of a national Monitoring, Reporting and Verification (MRV) system.
“Taiwan as well, which has joined to imitate the EU CBAM because they also want to have close links with the EU,” he added.
Taiwan signed a memorandum of understanding (MOU) with the European Energy Exchange (EEX) in July of this year, in a move to establish its own ETS.
“I think there has definitely been a lot of international criticism, especially from developing countries on CBAM and on the taxation,” Leah Wieczorek, Vice President of EMEA and APAC Carbon Markets at StoneX, said on the panel.
“We see a lot of countries that are now really prioritizing establishing carbon pricing, which I think is a really good thing, specifically if we look at the APAC region,” Wieczorek said.
“We see South Korea, Japan, Taiwan, China, all those countries really pushing ahead. And I think that some of the initiatives that those countries [are engaging in] are actually quite helpful,” she said.
“Specifically, for example, in South Korea or in the UAE, you see that the government has done a lot of capacity building on CBAM, where they are actually aiming to support the suppliers in really getting prepared for that,” she said.
“I think that’s really meaningful in shifting awareness to the subject,” she added.
But complexities do arise around how the charge on carbon is done in different locations.
“The proposed US Foreign Pollution Fee Act would be based on national average emissions assumptions. The EU is, at the moment, facility specific, which could create a lot of issues around re-exporting, and more broadly, for the flow of material around the world,” Patel said.
“The EU wants to avoid double charging by reducing the number of certificates required to reflect any effective carbon price already paid in the country of production. But the more different mechanisms and interpretations of carbon policy there are, the more complex it gets,” he added.
Despite this, the desire for more interconnectedness across global markets was strong on the panel.
“I think, in an ideal world, we would have carbon pricing that’s across all different kinds of jurisdictions, which then means we don’t really need a CBAM anymore, [though this] would unfortunately be a very ambitious goal,” Wieczorek said.
“The ideal world would be without CBAM – the world where there is an emissions market for everyone and everyone pays for their free externality,” Silva said.
In early September, the EU Commission launched a call for evidence on CBAM rules and methodology across three different topics, one of which was the Commission seeking inputs into the rules for importers applying for a reduction in the number of CBAM certificates required to purchase to take into account the carbon price paid in a third country.
UK to implement a CBAM in 2027 to prevent carbon leakage
The UK has confirmed that it will introduce a Carbon Border Adjustment Mechanism (CBAM) starting January 1, 2027, aimed at tackling carbon leakage and supporting its target for net zero emissions by 2050.
This move aligns with the UK’s commitment to reduce emissions by 68 percent by 2030 and by 81 percent by 2035, compared to 1990 levels.
Why CBAM is needed
The UK Emissions Trading Scheme (UK ETS) is reducing allowances by 45 percent between 2023 and 2027, pushing carbon prices higher. Free allowances are guaranteed until 2026, with their future under review. While this accelerates decarbonization, it also increases the risk of industries relocating production abroad, where climate regulations are weaker, a phenomenon known as carbon leakage.
To address this risk, the CBAM will cover emissions-intensive imports such as aluminum, cement, fertilizer, hydrogen, and iron and steel. Importers will pay a carbon price based on embedded emissions, either through verified data or government-set default values. The tax rate will also reflect the domestic carbon price that would have been incurred, had the goods been produced in the UK. The first tax returns and payments are due in May 2028.
Scope and coverage
The CBAM will apply to specific goods identified by UK tariff commodity codes under the Combined Nomenclature (CN), linked to the Harmonized System (HS). While upstream materials such as aluminum sheets and steel bars are included, finished products such as car doors are excluded. Both direct emissions and indirect emissions fall within the scope of the CBAM.
Rate and relief
- CBAM rates will be set quarterly from 2027, mirroring the UK ETS allowance price and Carbon Price Support (CPS).
- Importers may claim carbon price relief if equivalent carbon costs were paid abroad.
- A registration threshold of £50,000 per year ensures small importers are exempt, while still capturing over 99 percent of imported emissions.
Comparison with EU CBAM
While the UK and EU CBAMs share the same core purpose, there are key differences:
| Aspect | UK CBAM | EU CBAM |
|---|---|---|
| Sectors covered | Aluminum, cement, fertilizer, hydrogen, iron & steel. Electricity not included in the UK CBAM due to different carbon leakage risk profile | Aluminum, cement, fertilizer, hydrogen, iron & steel, electricity |
| Implementation timeline | Full obligations start Jan. 1, 2027. No prior reporting period. | Reporting-only period started Oct. 2023. Liabilities apply from 2026. |
| Mechanism | Works like a domestic tax. Importers declare embodied emissions and pay HMRC after each accounting period. | Importers must buy and surrender CBAM certificates equivalent to emissions of imports. |
| Emissions reporting | Based on verified actual emissions data or default global average values (from 2027). | Verified actual emissions data required; default values based on exporting country averages, with adjustments. |
| Verification of emissions | Independent bodies accredited by members of the International Accreditation Forum (IAF). | Independent verifiers accredited under EU accreditation frameworks. |
| Threshold for registration | Only applies if the total value of CBAM imports in a rolling 12-month period meets or exceeds £50,000. | Exemption for importers of less than 50 ton per year of CBAM goods. |
Looking ahead
The UK and EU are working on linking their ETS systems, which could lead to mutual exemptions from CBAM obligations. Future updates will refine emissions methodologies, align with global carbon pricing, and review the role of free allowances in maintaining competitiveness.

No postponement of CBAM: European Commission confirms implementation timeline
EUROMETAL has requested urgent clarification from the European Commission regarding recent press reports and market rumours suggesting a possible postponement of the Carbon Border Adjustment Mechanism (CBAM).
In his official reply to EUROMETAL, Director-General of DG TAXUD, confirmed that the current legislative timeline remains unchanged:
“The date of coming into effect of CBAM on 1 January 2026 is EU Law. It can only change with a legal proposal by the European Commission and the agreement of the European Parliament and the European Council. There is no such proposal on the table.”
The Commission also made clear that it does not comment on rumours circulating in the market.
This clarification confirms that the fiscal phase of CBAM will begin as scheduled on 1 January 2026, in line with the existing regulation.
EUROMETAL will continue to closely monitor CBAM implementation and provide regular updates to its members as official information becomes available.

CBAM autumn pricing influence questionable, says consultant
The assumption that the Carbon Border Adjustment Mechanism (CBAM) will deter importers from buying overseas, leading to a European domestic price recovery, could be overstated, warns German consultant Andreas Schneider.
“The EU’s increasingly protectionist course is likely to lead to lower imports in conjunction with CBAM,” he concedes. But “how quickly and to what extent this will be felt on the market is difficult to predict.”
The overall picture is made up of international price discrepancies, exchange rates, demand in the EU and other EU import duties or quantity restrictions, he finds.
“Recent weeks in particular have shown that even high EU import duties can be at least partially offset by favourable exchange rates and significant price advantages offered by third-country suppliers,” he argues. He also warns that imports could be ordered in excess of actual demand in the short term, to avoid CBAM costs. “It is therefore difficult to predict the extent to which CBAM will divert some of the demand for imports to EU plants,” he notes.
On the European domestic coil market, mills have hiked prices twice in quick succession, aiming to prepare the market for higher transaction prices. Hot rolled coil deal values have since inched above the bottom line of €550/tonne ($642) ex-works, but remained way below the €600/t envisaged by some mills.
According to a Dutch observer, prices for hot-dip galvanised coil are also showing a slight increase, with the level now at around €655/t ex-works for delivery in September to October.
Paid prices could even be higher, for HDG as well as for cold rolled coil, a German buyer says. He finds the two are nearly identical in price these days. “While were are used to price gaps of €10-20 [between CRC and HDG], you will hardly see one at the moment,” he tells Kallanish.
A Scandinavian source notes he has not bought HDG lately, but supplies projects with larger volumes of CRC, for which he pays less than a premium of €100/t on top of HRC.
An Austrian manager also sees CRC values being lower than HDG, but adds he generally dismisses discussion about fluctuations in the CRC/HDG premium. “This is just very relative, subject to the mill’s respective energy cost structure at a given moment,” he asserts.
“I deal with mills that have kept their premium differentials for years,” he states, adding the price relativity is often just a matter of how suppliers define their bases. “Some mills have an €80 premium for CRC and ask for €30 more for HDG. Others charge €100+ for CRC, and ask for €10 more for HDG. In both cases, you end up with €110,” he notes.
Christian Koehl Germany

Assofermet sees CBAM-driven potential flats price rebound
Market sentiment in the flat steel segment is not entirely negative, says Italian steel trade association Assofermet. A potential rebound from current low price levels cannot be ruled out in the coming weeks, supported by expectations surrounding Carbon Border Adjustment Mechanism (CBAM) implementation and mounting cost pressure on steel producers.
However, distributors and first-stage processors continue to face significant challenges, as declining demand coincides with rising production and logistics costs. At the same time, the market remains under strong pressure from Far East producers, the association says in its most recent note sent to Kallanish.
“Geopolitical tensions, the slowdown of the Chinese economy, and US protectionist policies continue to weigh on the economic climate, hindering any potential recovery in demand across Europe. Adding to these challenges are the effects of controversial EU environmental policies, which are having a negative impact on several steel-consuming sectors,” the note says.
Carbon tubes and plates have shown signs of recovery, helping to offset the continued weakness in stainless steel within the same product categories. In the long products segment, the decline in merchant bar has been offset by a solid performance in beams, keeping the segment relatively stable. “The current context gives the impression of a potential turning point,” Assofermet notes.
At the international level, although major conflicts remain unresolved, some mixed signals are emerging that suggest a potential path towards diplomatic solutions.
Natalia Capra France

ArcelorMittal delivers stronger EU profit, lower production
ArcelorMittal’s global steel output remained largely steady, whilst production in Europe saw a slight decline. Yet Europe showed improved financial results, including a skyrocketing Ebitda, the steelmaker says in its second-quarter results monitored by Kallanish.
The striking figure emerging from the report is the steelmaker’s European Ebitda, which surged 69.7% to $627 million in Q2, up from $370m in the first quarter and from $462m in Q2 2024. The improvement reflects a stronger price-cost spread, slightly offset by reduced shipment volumes.
ArcelorMittal’s global crude steel output edged upward year-on-year to 29.2 million tonnes in the first half of 2025, from 29.1mt in H1 2024. Quarterly production remained broadly stable, easing slightly from 14.8mt in Q1 to 14.4mt in Q2 2025. On-year, Q2 output declined moderately from 14.7mt. In Europe, production in the recent quarter fell compared with the previous quarter, primarily due to the planned reline of the Dunkirk’s blast furnace no. 4, which was restarted in mid-July. In the first six months of the year, crude output in Europe stood at 15.5mt, slightly down from 15.6mt in the same period last year. In the second quarter output reached 7.5mt, down from the 7.9mt achieved in the first quarter and from 8,041t of Q2 2024.
“Sales in 2Q 2025 increased by 6.0% to $7.7 billion as compared to $7.2 billion in 1Q 2025, primarily due to a 11.0% increase in average steel selling prices offset in part by a 3.0% decline in steel shipment volumes which was impacted by apparent demand. 2Q 2025 steel shipments were 1.4% lower year-on-year, reflecting a 6% decline in long product shipments whilst flat product shipments were stable,” the reports states.
European sales in the first half reached $14.87 billion, reflecting a y-o-y decrease from $15.66 billion in H1 2024. Ebitda soared in H1 to $997m from $805m in the same period last year. Steel shipment in the six-month period increased slightly on-year to 14.833t from 14.643t the previous year.
According to the report, in Europe demand is holding up relatively well, with apparent flat product consumption forecast to grow 0.5-1.5% in 2025, thanks to limited tariff impacts and easing interest rates. Despite short-term headwinds such as seasonally weaker demand and subdued manufacturing activity, European inventories remain relatively low. In the medium term, Europe may see notable improvement supported by trade policy, the Carbon Border Adjustment Mechanism (CBAM), and increased public investment in infrastructure and defence.
The group’s first-half sales stood at $30.72 billion, compared with $32.53 billion in H1 2024. H1 Ebitda stood at $ 3.44 billion, declining from $ 3.82 billion in H1 last year (see separate article).
Natalia Capra France