


French construction sector improves further
French construction industry managers’ opinion about the sector improved in January, according to a l’Institut National de la Statistique et des Études Économiques (Insee) report monitored by Kallanish.
Companies remain quite confident on the general outlook of the sector in the next three months. More business managers in the construction industry than in the previous month reported that their recent activity increased over the past three months, the report says.
Given their present staff size, companies consider their order books provide 9.9 months of work, slightly more than in December and much more than the long-term average, Insee explains.
Last month, capacity utilisation rate increased again. At the same time, production bottlenecks became more significant after easing in December, concerning 40% of the construction companies surveyed.
In January, significantly more business managers reported an improvement in their cash-flow position. A greater number also said they will increase their prices over the next three months, the report concludes.

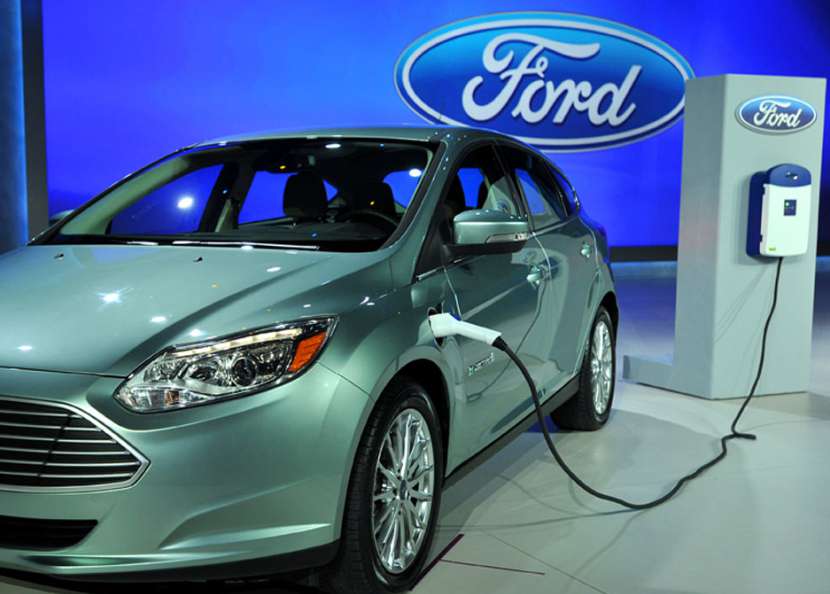
Steel mills see silver lining in semiconductor shortage
US auto producer Ford could lose 10-20% of its first-quarter production due to the global semiconductor shortage, according to chief financial officer John Lawler.
That’s no cause for concern for steel, however, market sources say.
Lawler notes that the semiconductor shortage is creating short-term volatility for the company’s 2021 guidance.
“The semiconductor situation is changing constantly, so it’s premature to try to size what availability will mean for our full-year performance,” he says. “Right now, estimates from suppliers could suggest losing 10-20% of our planned first-quarter production.”
Balancing the production losses against new initiatives in the EV and autonomous sectors remains a priority, he adds.
“Our team is working with suppliers around the clock to optimise the constrained supply and minimize profit impact, while prioritising customer orders, new-vehicle launches and compliance with C02 emissions regulations.”
A source at one top-tier domestic steel producer says that Ford will compensate for any production shortfall in Q1 with increased output during the year. A similar catch-up campaign contributed to the surge in hot-rolled prices in the US in late 2020, Kallanish notes.
“Inventories are 20% below one year ago, and the daily sales rate in January was 0.3% higher than January of last year – the first time the daily sales rate was higher than the year ago period since Covid began,” he says. “Low inventories that potentially impact sales in the next two months will only serve to prolong the demand.”
Eurofer throttles hopes for US trade policy liberalisation
European steel association Eurofer director general Axel Eggert warns against expectations for a liberalisation in external trade under new US President Joe Biden.
On the one hand, Biden has long been known as a supporter of trade liberalisation, Eggert notes. As vice president he championed the Trans-Pacific Partnership (TPP), and as a senator he voted for NAFTA and China’s entry into the WTO. This previous attitude does not seem to translate into Biden’s presidency, Eggert finds. “Noticeable by its absence is any change to the aggressive Trumpian trade policy in [Biden’s] initial package of measures,” he writes in a note to members.
Among other things, there has been no move so far to undo Section 232 tariffs. “Indeed, on his fourth day in office, President Biden signed an executive order further strengthening ‘Buy American’ regulations,” Eggert observes. “For now, at least, it would seem that the motivation – if not the rhetoric – behind the ‘America First’ strategy of the previous administration has not changed.”
Eggert calls on EU leaders to take note and defend the bloc’s interests. “Other regions are willing to take advantage of Europe’s promotion of ‘free’ trade without sharing its matching commitment to ‘fair’,” he states in the note seen by Kallanish.
For steel, this means extending existing steel safeguards, and swiftly deploying the full extent of available remedial trade defences when there are grounds to do so. Also, the EU ought to take “…pro-competitive” steps to improve raw materials flows – such as by preventing scrap exports, Eggert says. Thirdly, the EU should ensure that carbon leakage measures remain firmly in place to encourage other regions to follow Europe’s decarbonisation lead.

Canada finalizes duties on plate from Taiwan and Germany, Turkey excused
The Canadian International Trade Tribunal (CITT) ruled Feb. 5 that heavy plate imports from Taiwan and Germany have caused material injury to Canadian producers.
The affirmative injury determinations finalize antidumping duties set Jan. 7 by the Canada Border Services Agency (CBSA) of 7.0% for Taiwan’s China Steel Corp. and 80.6% for all other Taiwan exporters, and 6.3% for AG der Dillinger Huttenwerke and 68.6% from all other German exporters.
The CITT terminated its inquiry into dumped heavy plate imports from Turkey, saying that “the volume of dumped goods originating in or exported from Turkey is negligible.”
The CBSA launched the dumping investigation on May 27, 2020 and in preliminary duty findings in October dismissed cases against producers from two other countries, South Korea and Malaysia.
On April 6, 2020 Canada’s Algoma Steel filed a complaint with the CBSA alleging imports of heavy plate from the five countries were being dumped into Canada and injuring domestic producers.
— Tom Balcerek

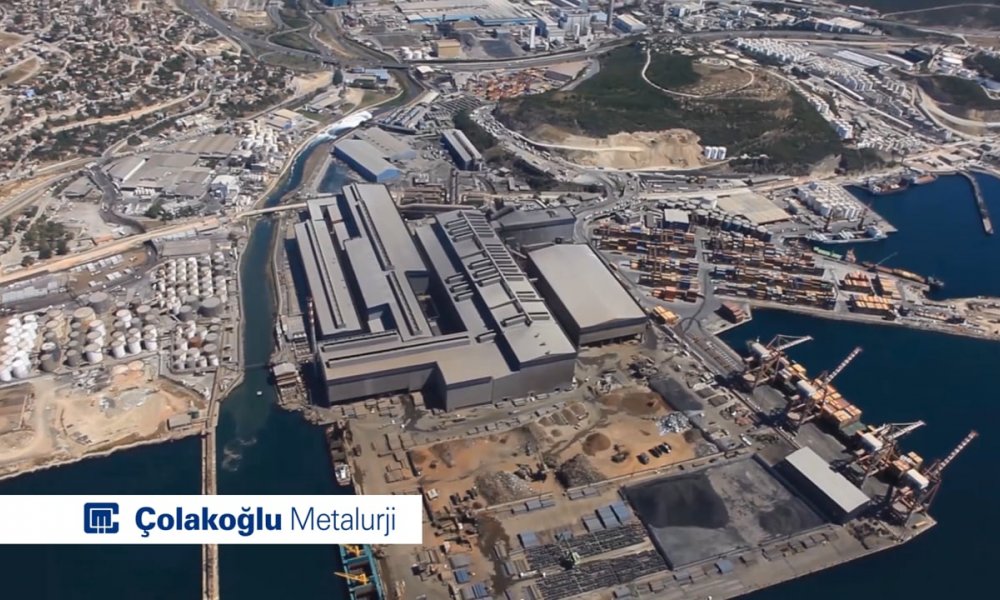
Colakoglu sets maintenance for May, raising HRC capacity 50% in Q2 2022
One of Turkey’s largest steel producers, Colakoglu, is planning to pause output at its rolling mills in May for maintenance work, S&P Global Platts learned from Ugur Dalbeler, CEO of the company, on Feb. 5.
“It is a planned maintenance,” he said, adding that they can reevaluate the timing of the maintenance according to market conditions. The executive, however said he couldn’t give an exact time for the duration of the maintenance.
An informed industry source said the maintenance could be long enough to create some some supply problems in the market. “This could also support mills’ HRC pricing at that time,” he said.
Higher demand, shortages and higher scrap costs pushed Turkish mill HRC prices above $800/mt in December, as Platts has reported. But, Turkish mills’ HRC prices have begun to soften gradually in recent weeks, due to eased shortages, low demand both in the domestic and export markets, cheaper import offers, especially from China, and the notable declines seen in scrap prices.
Some Turkish mills have begun offering HRC at $770-$780/mt ex-works for May rollings, while some mills’ HRC export offer prices have fallen below $760/mt FOB.
An industry source said a major Turkish HRC producer even pulled down its HRC export offer price to $740/mt FOB on Feb. 4, while a service center manager on Feb. 5 reported hearing from a colleague in the EU that the mill recently offered HRC as low as $730/mt FOB to the region.
Taking into account the scrap price decline and Chinese mills’ notable HRC exports to Turkey in previous weeks with prices as low as $675-$685/mt CFR, Turkish mills’ new discounted prices are still considered high by some market sources.
Although some market sources are expecting Turkish mill offer prices to touch $700/mt FOB, these mills continued efforts to keep offer prices firm till the return of Chinese mills’ from New Year holidays, in expectation of a strong raw materials and finished product pricing sentiment after the return.
Also. there have been some delays in Turkish mills’ HRC deliveries in recent weeks, some re-rollers told Platts.
Some end users meanwhile have continued to claim that shortages and price rises in the market were arising from insufficient HRC production capacity in Turkey, and they have been criticizing the recent dumping investigation started by Turkey against HRC imports from the EU region as well as South Korea.
Turkish mills are denying this claim, saying the shortages arose from the sharp rise in end user demand after the ease of the pandemic and domestic mills mostly focused on meeting domestic demand.
Colakoglu to raise HRC output capacity by 50%
Major Turkish steelmaker Colakoglu has decided to raise its HRC output capacity by 50% with a new annealing furnace investment.
Ugur Dalbeler, CEO of the company told Platts Feb. 5 that their HRC production capacity will reach 4.5-5 million mt with this investment as of the second quarter of 2022. “We will continue our investments afterwards to raise our value-added steel production,” he said.
Colakoglu currently has bar output capacity of 1 million mt/year and HRC production capacity of 3 million mt/year.
With the notable rise in Colakoglu’s HRC production capacity and a new 2 million mt HRC mill project by another major Turkish steelmaker, Tosyali Demir Celik, installed HRC output capacity in Turkey is expected to reach 23 million mt as of the end of 2022.
— Cenk Can
Brexit supply chain problems?
Because of Brexit, logistics and warehousing companies in The Netherlands are getting tons of requests from British businesses looking to rent warehouse space.
In an interview with The Guardian, our very own Business Development Manager Europe, Jochem Sanders, said: “We know for a fact it is going to be complete madness into summer.” Read the full article here.
Eurozone construction rebounds but post-pandemic uncertainties remain: ING
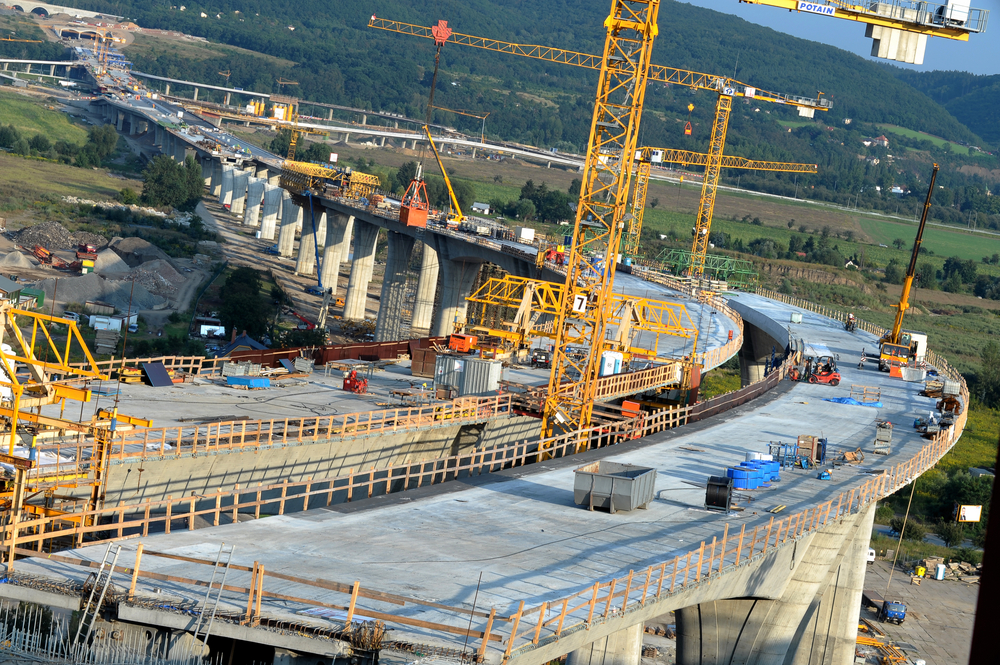
Eurozone construction output should recover by 4% on-year in 2021, but the recession will leave its mark, says ING Bank. Permits for new dwellings – a strong indicator of future production – plunged in France and Spain in 2020, which may hinder the completion of new dwellings in the coming years, even as the pandemic abates.
Infrastructure companies are receiving fewer orders, and the high uncertainty and weakening financial position of many firms mean investments in commercial building are also expected to decline.
During the first Covid-19-related lockdown, the construction sector was only modestly affected, although France experienced a large contraction. Eurozone order books showed only a small decrease from 8.4 months of ensured work at the beginning of 2020 to 8.0 months in January 2021. The rebound this year will be pronounced in countries, such as France and Spain, that had strict lockdowns. More construction sites will remain open in France during the second pandemic wave.
“Given that the uncertainty regarding the duration of the pandemic is very high and the financial position of many firms is weakening, private and public investment is expected to be lower in 2021,” ING says in a report sent to Kallanish. “As a result, eurozone construction output growth is unlikely to fully compensate for the decrease of 2020 this year alone.”
During economic crises, governments typically attempt to stimulate the economy by investing into infrastructure. “However, this time appears to be somewhat different, as it is not certain whether we will return to the same traffic congestion as before,” ING says. “This is because an increasing number of people will probably continue to work from home and fewer people going on business trips.”
Economic recovery schemes for the pandemic are focusing on other investment categories than just infrastructure, with the EU recovery fund aiming to make European economies and societies more sustainable. Moreover, central governments are unlikely to skip or postpone infrastructure projects, but local governments might due to the pandemic.

Outokumpu sees first-quarter deliveries growing 10-20%
Stainless steel group Outokumpu expects first-quarter deliveries to jump significantly compared with Q4 levels, Kallanish learns from the company’s annual results.
“The demand for stainless steel is strengthening and both business areas Europe and Americas are expected to see a seasonal increase in volumes,” Outokumpu says. The jump in Q1 deliveries should be 10-20% on-quarter globally, it adds.
In 2020 the group’s steel deliveries reached 2.1 million tonnes, almost in line with 2019 levels. Turnover was nevertheless down by €800 million ($959.6m) to €5.6 billion ($6.7 billion) and net loss reached €116m compared with a €75m loss in the previous year.
Going forward, the company says it will continue focusing on strict cost and capital discipline, strong customer engagement, and a lean and delayered organization. In Q4 Outkumpu significantly reduced its headcount to make the group leaner and more competitive.
Group chief executive Heikki Malinen has again called for stronger import barriers in Europe for stainless steel. “Import penetration into Europe remains high despite a decrease to 24% in the fourth quarter,” he observes. “We continue to call for available trade enforcement tools to be applied in full to restore a level playing field and secure a sustainable future for the European stainless industry.”
Severstal to reduce capital expenditure in 2021
Russian steelmaker and miner Severstal will invest in 2021 around $1.35 billion into major projects at its steel and resources divisions, some -20% less than in 2020.
The investments continue to form part of the firm’s $2.5 billion strategy spanning to 2023. They will include key focus strategy areas such as customer service excellence, cost leadership and new opportunities, the company says in a statement sent to Kallanish.
The firm will invest around $785 million into the steel division, with $469m invested into development projects including the second stage of coke battery No.11 construction. The latter was commissioned at the end of 2020 and is due for completion in 2022. Additionally, blast furnace No.3 will be brought to design capacity and long-range mill and heating furnaces will be upgraded.
Maintenance of existing facilities is penned at $453m, while industrial safety improvement will receive $42m, along with labour protection and environmental projects.
The resource division, incorporating mining and processing iron ore and coking coal facilities, as well as scrap procurement, will receive $524m, of which $267m will be used to develop production further.
The main phase of construction of the cycle-flow technology complex at the Karelsky Okatysh iron ore mine is one of the chief investment areas this year. This is along with the Yakovlevsky mine, leading to an increase in iron ore mining volumes to 5 million tonnes by 2023.
Ongoing works at the Vorkuta Coal coking coal mine and the development of the Pechegubsky field are aimed at increasing output by 2.4mt to 5.6m t/year in 2023, enabling 90% coking coal self-sufficiency.

Demand weakens for Italian longs
Italian long products demand has weakened this week, with scrap prices falling and rebar values down €30/tonne ($35) in recent days, market participants tell Kallanish.
Rebar has hit the level of €300-320/t base ex-works in the majority of transactions, or €560-580/t including size extras. Other long product prices are however holding for the moment, even though the high point of the January price range is not being paid.
Merchant bar quotes remain at €240-250/t base ex-works. Very few contracts have been signed at €260/t base ex-works. Including size extras, domestic material is at €660-680/t base ex-works.
Meanwhile, the first category of domestic sections remains at €325-340/t base ex-works, with a few high points at €360/t base ex-works. This represents effective prices of €710-725/t and €745/t. Prices increase by €20/t for each subsequent category, sources say.