


Low Italian, Spanish pricing concerns European longs mills
Italian merchant bar and beam prices remain largely stable, despite a broader market downturn affecting wire rod, rebar, mesh, and all flat products. The recent upward momentum in scrap prices within the country also appears to be waning, with indications of a potential decline ahead.
The current trend, coupled with the weakness observed in Turkish scrap and steel markets, is raising concerns among European long steel producers, who are closely monitoring developments in southern Europe.
Several mill and buy-side sources tell Kallanish that Spain is experiencing a comparable downturn, with uncertainty prevailing in the market. In northern Europe, three sources indicate customers are firmly rejecting the elevated prices currently enforced in France, Germany, Austria and other countries for long products, and are pushing for discounts in upcoming contracts.
A significant buyer in France says he will refrain from acquiring any material unless he secures a price reduction that aligns with the current downturn in downstream demand. Two buyers in France and Austria note they are adopting a wait-and-see approach, while German mills are striving to maintain their elevated pricing levels, beginning to lose orders.
Merchant bar demand in Italy continues to exhibit significant weakness, with a pessimistic forecast provided for the coming weeks. Producers are contemplating an increase in quotes to mitigate the ongoing decline; however, there is a palpable concern regarding the potential loss of orders.
Domestic merchant bar prices are currently under pressure due to import offers from Turkey and Spain at considerably lower rates than those from Italy. Domestic merchant bar is at approximately €650-670/tonne ($742-765) ex-works, inclusive of size extras.
The first category of beams is stable within the range of €780-790/t, inclusive of delivery costs. Lower values are available as Spanish material is being offered at a €40/t discount, and there is a significant rise in competition and supply within the country, with more producers focusing on selling beams.
Meanwhile, Italian rebar is also on a downward trend, with prices descending every week. Values have now reached €250/t base ex-works. Producers are selling at €510-520/t ex-works including €260-270/t size extras.
Natalia Capra France


EU reintroduces country-specific sections safeguard quotas
The European Commission has removed, effective 1 July, the 15% cap on the category 17 angles, shapes and sections EU safeguard quota. It will also re-introduce country-specific quotas for the UK, Türkiye and Korea, and reinstate the residual quota without a cap, Kallanish notes.
The 15% cap was introduced recently because of undue crowding out of certain traditional suppliers. However, that country-cap is affecting the traditional trade flows of certain trading partners, restricting their access to duty-free volumes to levels below their historical trade levels, the Commission notes.
As part of the upcoming change, the country-specific quota holders will not have access to the residual quota during the last quarter of a safeguard year.
The measure applies to HS codes 7216 31 10, 7216 31 90, 7216 32 11, 7216 32 19, 7216 32 91, 7216 32 99, 7216 33 10 and 7216 33 90. Ukraine will have a quarterly quota exceeding 31,600t, the UK 27,500t, Türkiye 22,800t and Korea 5,000t, with the residual quota at 12,555t.
The duration of the measure remains until 30 June 2026 and the rate of liberalisation remains 0.1% yearly.
Consultations on the change will take place, either in person in Brussels or in a virtual setting, from 12 June until 19 June.
Adam Smith Poland

Uncertainty, low margins downstream compromise French steel prices
French steel prices are experiencing a slight decline, particularly for coil derivatives and certain long products. This decrease is primarily attributed to weak downstream consumption and market uncertainty, which is raising concerns, especially for some coil derivatives like sheets and tubes, buyers tell Kallanish.
Market participants anticipate prices will remain weak, particularly for longs, due to competitive pressure from Italian and Spanish producers who are offering at lower prices than domestic products. Profitability continues to be a critical concern and the primary factor driving buyers to seek discounts.
A major buyer indicates that while volumes are meeting expectations, low profitability is compelling numerous firms to put pressure on producers to secure price reductions.
The downstream sector, encompassing construction firms and distributors, is focusing simply on achieving breakeven each quarter, with little expectation for a more positive outcome in the near term.
A distributor remarks: “Companies with strong financial foundations will endure, while others are likely to face big challenges.” He notes that if the downstream sector experiences financial difficulties, it will create a ripple effect upstream.
May saw a downturn in sales and June appears to be subdued, with numerous buyers adopting a wait-and-see approach. A source from a distribution network indicates there is significant pressure to cut costs due to low margins. “We will continue to put pressure on producers to reduce prices,” he comments.
Domestic sections are stable, whereas rebar, mesh, and merchant bar are experiencing a slight decline of approximately €10-20/tonne ($11-22) on average, compared to the peak observed in early May. This trend is influenced by competitive import offers from within Europe.
First category beams are now at €770/t delivered, while domestic merchant bar prices in France are observed at €230-240/t base delivered, with effective prices, inclusive of size extras, at €650-660/t delivered. Domestic rebar is hovering at €630-640/t delivered on average, sources suggest.
Natalia Capra France

SSAB, Danieli sign contract for new Luleå mini-mill
Swedish steelmaker SSAB and Italian equipment supplier Danieli have signed a contract for the supply of equipment for SSAB’s new mini-mill in Luleå, the companies said on 10 June.
This contract followed an Early Service Agreement (ESA) signed in July 2024.
The new Luleå mill will consist of two electric arc furnaces (EAFs) with a total capacity of 2.5 mt per year, secondary metallurgy, a caster and direct strip rolling mill, and a cold rolling complex.
The mini-mill will produce hot-rolled strip in thicknesses ranging from 1.3 mm to 25.4 mm.
When completed, SSAB will decommission the existing blast furnace-based production system in Luleå. This will reduce Sweden’s CO2 emissions by 7% in addition to the 3% from the Oxelösund mill conversion, SSAB said.
In the second quarter, enquiries for green steel flat products have increased, but actual transactions remained limited. Buyers are apparently also less interested in mass-balanced material, preferring embedded carbon reductions.
McCloskey’s reduced carbon marker, calculated in reference to all green HRC premium indications reported in the week to publication, stood at €60.46/t on 6 June.
Maria Tanatar

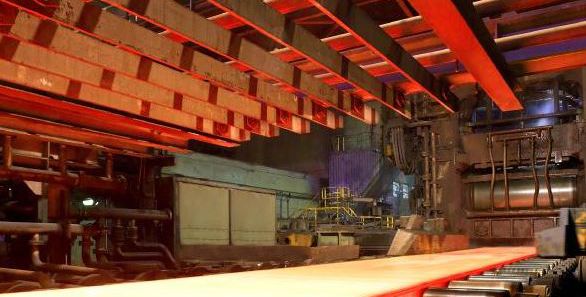
Thyssenkrupp launches new continuous casting line
Germany’s Thyssenkrupp said it has started trial production of steel slabs at its new continuous casting line No. 4 at its Bruckhausen plant in Duisburg.
Further trial production runs will take place in the coming weeks, the steelmaker said.
The modernization also includes a new fully automated slab storage yard and completely modernized hot strip mill 4 with a new preliminary line and two new walking beam furnaces.
“The aim is to further expand production of high-quality steel grades with the highest standards of strength, dimensional accuracy, and surface quality – particularly for applications in electric mobility, lightweight construction, and the energy sector,” Thyssenkrupp said.
The Bruckhausen upgrade is one of the largest modernization projects in Thyssenkrupp’s history and the central investment package in its 20-30 Strategy. The aim of the project is to make the Duisburg production site more efficient and flexible, and focus on products with higher added value.
Maria Tanatar
Piombino steel plant relaunch plans unveiled
Steel company Metinvest Adria presented plans for the relaunch of steel production at Piombino, Italy, at a meeting on 10 June attended by Italian authorities including the Ministry of Enterprises and Made in Italy (MIMIT) and Italian trade unions.
An agreement will be formalized after approval by the trade unions.
Following the meeting, the unions called off a strike that had been planned for 12 June, Italian trade unions FIUM-CGL and UILM said.
In February this year, Ukrainian steelmaker Metinvest and equipment manufacturer and engineering firm Danieli signed a shareholder agreement governing their partnership in a new steel plant in Piombino, Italy. The project is governed through a joint partnership Metinvest Adria.
The Piombino steel plant, which is owned by JSW Steel, produces long steel products, including rails and operates at low capacity. Last year, Metinvest Adria finalised an agreement with JSW Steel Italia to secure access to industrial areas.
In 2024, Metinvest and MIMIT signed a declaration to promote the industrial revitalisation of Piombino through a large green steel production plant.
The new project of Metinvest Adria Piombino is anticipated to have capacity of 2.7 mt/y via electric-arc furnace production, with recycled feedstock including scrap, pig iron and direct reduced iron. The plant will partially source these raw materials from Metinvest’s operations in Ukraine. Production at the new plant is expected to start in 2027, according to McCloskey’s European Green Steel Profile.
Maria Tanatar

ArcelorMittal Poland calls for decarbonisation support
ArcelorMittal Poland has called for support in its decarbonisation efforts as it says mills cannot bear the additional costs in challenging market conditions, the company told McCloskey on 13 June.
Decarbonisation requires installation of new equipment and implementation of new technologies to meet the EU’s CO2 emission targets. And the transition needs to be done under strain of a challenging market, which already has some additional costs that non-EU steelmakers do not face, including the EU Emission Trading System (ETS). In addition, energy costs in Europe are the highest in the world, ArcelorMittal said.
The EU aims to achieve a 55% reduction in emissions by 2030, and to become carbon-neutral by 2050.
The EU market has been under pressure from the rapid rise of competitive steel imports: “Imports from outside the EU, where production costs are significantly lower, already satisfy almost 30% of apparent steel consumption in Europe,” the company said.
The statement has been confirmed by market participants who cited low import offers for hot-rolled coil as one of the driving forces behind the domestic price drop.
“Against this backdrop, no steel producer can bear the costs of the transition to low carbon-emissions steelmaking alone,” ArcelorMittal Poland said.
The steelmaker also calls for a reduction of energy costs and effective mechanism to prevent carbon leakage.
“We are glad that the European Commission has taken into account the majority of the steel industry’s requests in the Steel and Metals Action Plan. Now, it will be crucial to implement these measures quickly,” the producer said.
The European Commission unveiled its official European Steel and Metals Action Plan on 19 March.
ArcelorMittal Poland has spent over 1 billion zlotys (around $270 million) on projects aimed at reducing its environmental impact and increasing energy efficiency, including blast furnace overhaul. For additional details on steel decarbonisation initiatives in Europe, please see McCloskey’s European Green Steel Profile.
ArcelorMittal’s Dąbrowa Górnicza plant is one of several producers of 120-metre long rail used in high-speed rail.
Maria Tanatar

Tata UK operations risk full 50% US tariff rate
Tata Steel UK has warned that US President Trump’s 50% tariff on steel and aluminium could threaten its operations if a melt-and-poured condition is included under a UK-US trade agreement.
CEO Rajesh Nair urged the UK government to “secure a deal as soon as possible” in a statement 6 June, due to Tata’s continued reliance on imports to feed its supply chain.
“Tata Steel UK will need to import steel substrate until Electric Arc Furnace steelmaking is operational in Port Talbot from late 2027 onwards,” Nair said.
Blast furnace operations were terminated at the Port Talbot site in October last year, to facilitate a transition to less-carbon intensive electric-arc furnace production (EAF). The renovation was partly financed with £500m of public funding, scheduled for completion in late-2027.
In the meantime, Tata has predominantly resorted to importing steel melted in its associated operations in India and the Netherlands. US President Trump’s latest tariff offensives – namely the now-50% tariff rate on steel imports – threatens to undermine the competitiveness of Tata’s exports to the US if the company is not granted specific consideration in UK negotiations with Trump’s administration.
The UK government is looking to ensure the tariff rate falls to zero in finalizing details of the US-UK Economic Prosperity Deal (EPD), the general terms of which were signed 8 May.
The EPD states that “[t]he United Kingdom will work to promptly meet U.S. requirements on the security of the supply chains of steel and aluminum products intended for export to the United States and on the nature of ownership of relevant production facilities.”
If satisfied, the US will create a quota for UK steel exports at most favoured nation rates.
This indirectly refers to the UK government’s passing of emergency legislation to seize control of Chinese-owned British Steel earlier this year, motivated by fears of long-term damage to the UK’s sole active steelmaking assets in Scunthorpe if the furnaces were allowed to run out of raw materials and cease production.
Influenced by the deal, the UK was temporarily spared from the 50% rate – instead facing a reduced US steel tariff of 25% – but possible imposition of a melt-and-poured condition for future tariff-exemptions have raised concerns for Tata and their US export portfolio.
“[O]ur mills continue to transform imported steel coil and slab into high-value, specialist products which are not available from US producers and are therefore essential to our US customers,” said Nair. “It is therefore critical for our business that melted and poured in the UK is not a requirement to access the steel quotas in any future trade deal.”
Tata already has a carve-out from the UK’s own safeguard measures under product category 1B, structured to ensure Tata and other importers can continue to competitively service the UK’s downstream markets with imported hot-rolled coil.
Trump has stated that the tariff on the UK may be increased “on or after July 9,” contingent on whether the US “determines that the United Kingdom has complied with relevant aspects of EPD”.
Nair says that Tata “would be happy to provide the US Government with any needed assurances on the provenance and processing of the steel we supply.”

Liberty Galati faces technical setback days after relighting BF No5
Operations at rolling mills were scheduled to commence next week using feedstock that has already been produced.
On June 12, BF No5 was stopped due to a technical failure, just days after it was restarted following more than a year of downtime, multiple source told Fastmarkets.
The accident overnight June 12 involved a detached “salamander” – a solid accumulation of molten iron and slag – that broke free and blocked the furnace’s drain outlets. This forced an emergency shutdown, sources familiar with the matter said.
They added that production could resume after the blockage was cleared if no further damage were found.
Liberty did not comment on the nature of the accident, noting out that its plan was to resume steel production at Galati as planned.
“The blast furnace is in the process of increasing and stabilizing production,” Liberty’s spokesperson told Fastmarkets on June 13. “During this phase, technical adjustments are necessary, and our team is focused on managing safely a technical issue caused by the rapid cooling of the liquids, which will be resolved soon.
“With raw materials in stock and a solid supply chain, Liberty Galați continues to produce high-quality steel and will start deliveries to customers,” the spokesperson added.
Despite the accident, plans to resume rolling mill operations seemed to be unaffected, and volumes of semi-finished steel products have already been accumulated.
“Liberty Galați successfully started its production operations last week, including the blast furnace, sinter plant and steel shop, and it has already produced more than 15,000 tonnes of slab for rolling, to commence next week,” the spokesperson said.
The company restarted BF No5 on June 4 [LINK]. The equipment was idled in May 2024 amid difficult market conditions.
The Galati steelworks, islocated on the west bank of the River Danube, in southeastern Romania. It has capacity for 3.5 million tonnes per year of hot-rolled coil, 1 million tpy of cold-rolled coil, 1.2 million tpy of steel plate and 350,000 tpy of hot-dipped galvanized coil, according to Fastmarkets’ information.
The company has five BFs with combined capacity for more than 6 million tpy of pig iron, but at present only the 2 million-tpy BF No5 is in operation.

European HRC prices slide in recent transactions
In Northern Europe, HRC with July lead times was heard offered by integrated mills at €610-630 ($705-728) per tonne ex-works or delivered.
Italy-origin coil was offered to Germany at €620 per tonne delivered, with transactions for bigger lots reported during the week at €600 per tonne delivered.
Buyer estimations of tradable prices were heard at €570-600 per tonne ex-works on Friday.
Some bids were reported at even lower levels of €540-550 per tonne ex-works, but no confirmed trading at these levels has been reported so far.
“There is a lot of speculation, as always in the falling market,” one mill source told Fastmarkets. “Prices [for HRC] are not below €600 per tonne delivered now.”
Sources reported better trading in the past few days but stressed that “nothing was booming.”
“We were getting more inquiries and traded some decent volumes [in the week of June 9] but overall the market is not booming,” a second mill said. “This week [commencing June 9] was short due to a public holiday on June 9 and the following week will be short again due to Corpus Christi holiday [celebrated June 19].”
Fastmarkets’ calculation of the daily steel HRC index, domestic, exw Northern Europe was €594.00 per tonne on Friday, down by €6.00 per tonne from €600.00 per tonne on Thursday June 12.
The Northern European index was down by €12.38 per tonne week on week and by €54.00 per tonne month on month.
Meanwhile, domestic HRC prices in Central Europe were stable during the assessment period, according to market sources.
Mill sources indicated the market level for HRC at €600-630 per tonne ex-works in the region in the week to Wednesday June 11, unchanged from the previous assessment.
Buyers were more bearish with indications reported mainly below €600 per tonne ex-works by Friday.
Fastmarkets’ weekly price assessment for steel HRC, domestic, exw Central Europe was €600-630 per tonne on Wednesday, unchanged week on week.
Meanwhile, Fastmarkets’ daily steel HRC index, domestic, exw Italy was calculated at €580 per tonne on Friday, down by €1.88 per tonne day on day.
The Italian index was down by €10.00 per tonne week on week and by €30.00 per tonne month on month.
An integrated supplier in Italy was offering HRC at €585-590 per tonne ex-works, with sources telling Fastmarkets that this supplier was “reluctant to provide discounts from these levels.”
Offers from a reroller were heard at €570-580 per tonne ex-works.
Some rerollers were still able to offer late-June lead times, while integrated mills offered July delivery.
One source reported a sale of HRC from a major European mill to Italy at €555 per tonne ex-works, but this information could not be confirmed by the time of publication.
Buyers estimated tradable prices at €570-580 per tonne ex-works, with some bids reported as low as €550 per tonne ex-works.
In the secondary market, 4 mm HR sheet was traded at €660-680 per tonne CPT.
Sources were not ruling out the downtrend continuation in the coming weeks, but also pointed out that “no big shocks” were expected.
“There might be some correction of [HRC] prices, but not a nosedive. Plus, we are heading into the quiet summer period so everything slows down,” a buyer source said.
Import HRC offers were stable to slightly weaker in the week to Friday.
Indonesian HRC was heard offered at €490-500 per tonne CFR to Italy earlier this week, with offers heard sliding to €480 per tonne CFR by Friday.
A large-tonnage transaction for Indonesian HRC was reported at €480-485 per tonne CFR to Italy.
India-origin material was offered around €535-540 per tonne CFR, while Turkish coil was said to be available at €530-540 per tonne CFR, duty paid.
Algerian coil was offered to Italy at €530 per tonne CFR.
From Vietnam and Thailand HRC offers were reported at €515 per tonne CFR to Italy.
Market participants expressed broader concerns about potential import trade flow disruptions amid upcoming implementation of the EU’s Carbon Border Adjustment Mechanism (CBAM) added to the prevailing uncertainty.
“The costs of handling imports will dramatically change starting next year and buyers should start to prepare now,” a buyer in Italy said.
“There is a chance we will see rushed import bookings with lead times in 2025 – before CBAM kicks in – and then in the first quarter 2026 there will be a pause in import deliveries and stronger reliance on Europe-origin HRC” a mill source told Fastmarkets.
Other sources argued that with safeguards in place, there was no chance to “rush imports bookings due to high risks.”
