


Evraz expects Russian rebar consumption increase
Russian construction steel demand should increase in 2021, driven by rebar after its consumption fell in 2020, says general director of Evraz trading arm Metall Inprom (EMI) Sergei Sintsov.
EMI is a large player in the market for processing rolled metal products for construction purposes. In recent years, the company has been actively introducing the processing of structural shapes.
“We expect an increase in the consumption of rebar within 3-5% on-year; this is the most capacious segment of the market for rolled products for construction purposes,” Sintsov says in an interview on the EMI website. “We also expect insignificant growth in the rest of the construction profiles.”
In 2021, the dynamics of the domestic market will largely depend on external factors – primarily the pandemic and economic situation, he comments. The direction of the global steel market will also play a significant role.
“As for the production of metal structures, the key influence on the development of this segment will traditionally be provided by large infrastructure projects, which are highly dependent on both project financing and the economic environment,” Sintsov observes.
In 2020, parent company Evraz’s crude steel output declined 1.3% on-year to 13.81 million tonnes (see Kallanish passim). Russian output inched up 0.8% to 12.1mt but North America’s declined 15.1% to 1.58mt, on oil and gas market turbulence affecting demand.
Consolidated 2020 steel product sales declined 3.1% to 13.1mt, with sales of semis rising 6.1% to 6.18mt on higher slab and billet volumes in export markets.

ArcelorMittal sees boost to steel production at Sestao, Spain
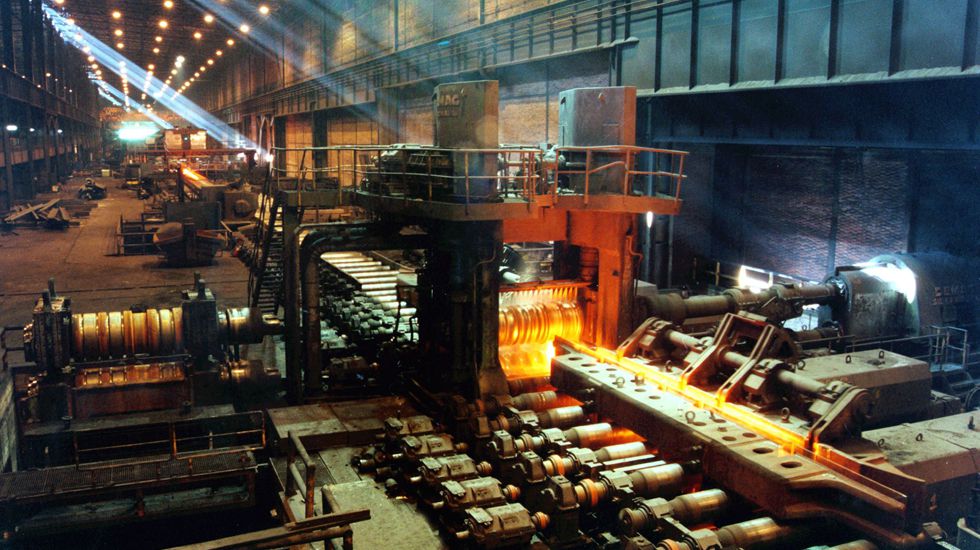
ArcelorMittal expects to further hike steel production from its Spanish Sestao site to around 70,000 mt/month by the second quarter due to a favorable demand outlook, the company’s Spanish subsidiary said Feb. 15.
The increase follows an initial target that was set a month ago to reach 45,000 mt/month. The plant has the capacity to produce 1 million mt/year of steel, or 83,000 mt/month.
The electric arc furnace at Sestao was restarted in September 2020 after being halted by the COVID-19 pandemic in April 2020, with an initial objective of hitting 40,000 mt/month production.
In its other operations, the company also restarted its A Sinter in Gijon on Jan. 4, which had been halted since April 2020, while its furnaces at Gijon, with a combined capacity of 5 million mt/year, the integrated sheet steel production site at Aviles, and the coking batteries are all in operation.
— Gianluca Baratti

Weather leads to FM at German steelmaker Salzgitter; disruption at Thyssenkrupp
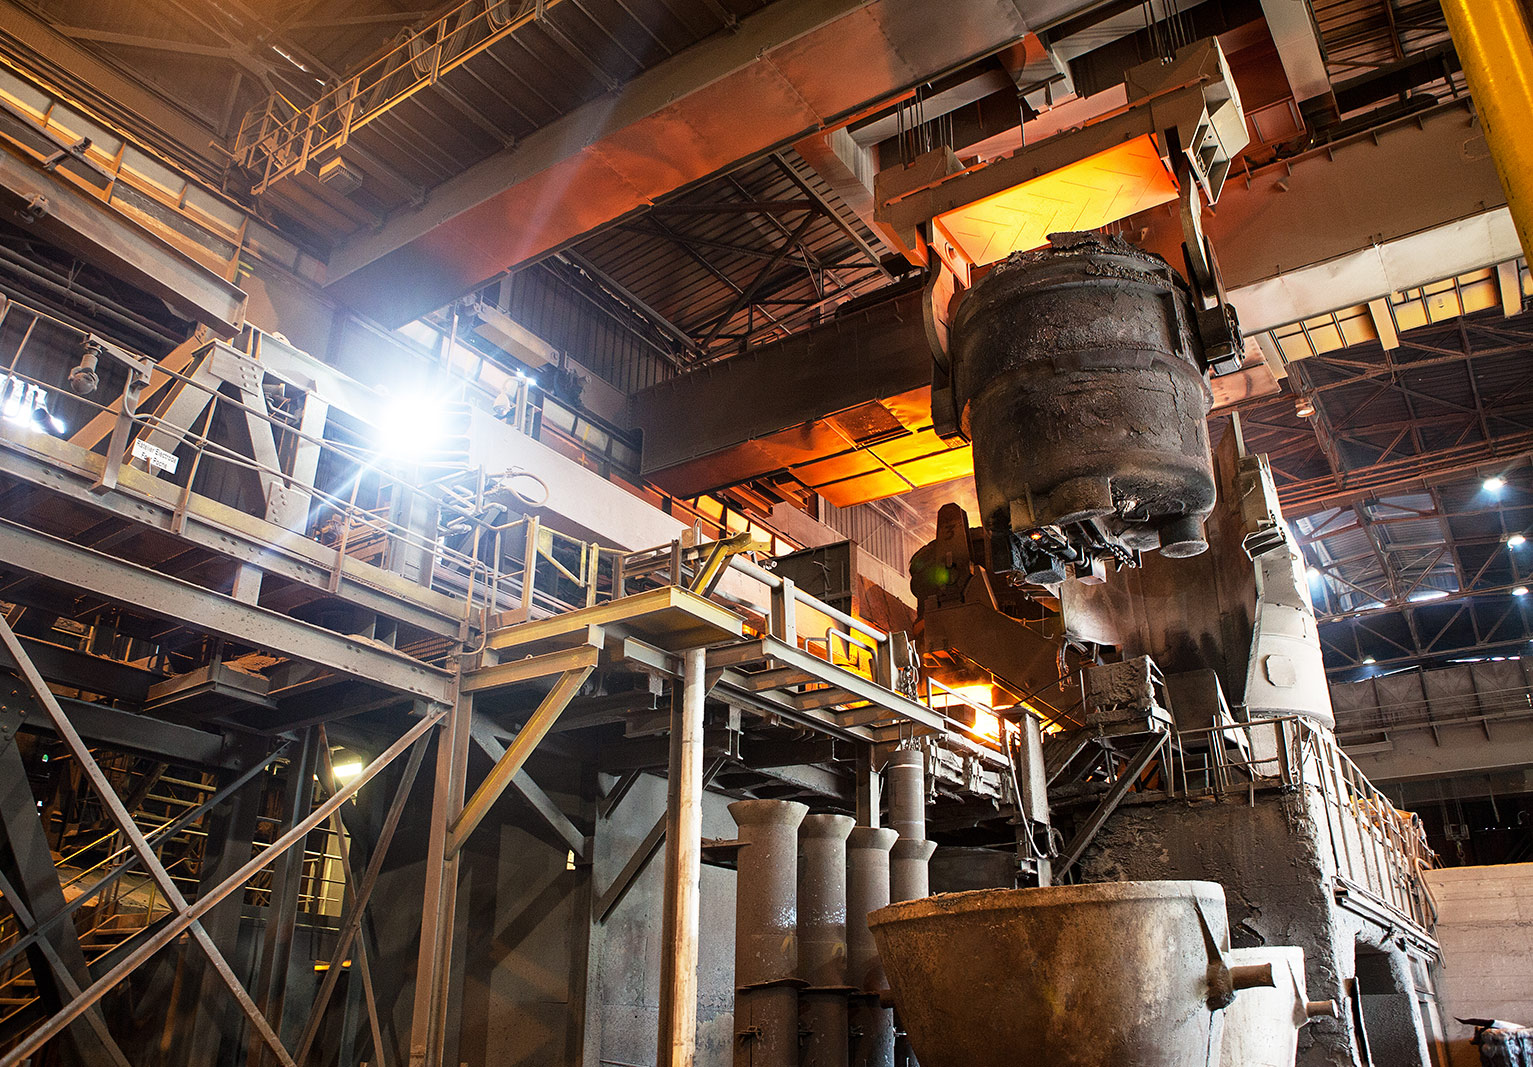
Salzgitter, Germany’s third largest steelmaker, has declared force majeure due to inclement winter weather conditions which have impacted transportation of its steel deliveries via road, rail and inland waterway, the company confirmed to S&P Global Platts Feb. 15. Thyssenkrupp, Germany’s largest steelmaker, said it was facing plant disruption due to the weather “aggravating conditions”.
A Salzgitter spokesperson confirmed a letter to customers from Feb. 10 that there have been “dramatic” weather conditions with no relief on shipments yet.
Both Salzgitter and Thyssenkrupp have been impacted by snowfall and strong winds as extreme winter weather conditions have hit Germany in recent days.
Salzgitter’s letter to customers stated that the Salzgitter-Beddingen freight station, which is important for the rail transports of several Salzgitter Group companies, could not be accessed at this moment, with train congestion throughout the entire rail freight network.
“Since the continuous supply of raw materials and inert gases, which is absolutely necessary for our plant, has come to a standstill in the meantime, we can no longer exclude production disruptions in the next few days. Until further notice, it is not possible to ship goods by rail or inland railway,” the letter said.
A source close to the matter said customers have been informed of the disruption in the supply chain due to weather conditions out of the mill’s control.
“It is a precautionary measure, as last week has seen all the weather-related road and railway blockages; so far we have only seen a few not that significant deliveries,” a German trader said. “For the next days higher temps are forecast, even up to 10-13 degrees, this could cause issues with water levels and some isolated flooding remains to be seen.”
The same source said that the weather in Dusseldorf was expected to turn warmer in the coming days.
S&P Global Platts assessed Northern European hot rolled coil prices at Eur730/mt ex-works on Feb. 12, up Eur10/mt on the day and their highest level since Sept, 1 2008, on tight supplies in a market where demand is now widely recovering from the impact of last year’s coronavirus restrictions.
Thyssenkrupp – some easing
Steelmaker Thyssenkrupp also sent a customer letter Feb. 11 declaring an “aggravation of the supply situation”. A Thyssenkrupp spokesperson told Platts that starting Feb. 15 the steelmaker was seeing some easing of the supply situation.
In the customer letter, Thyssenkrupp said that on top of demand outpacing production since summer 2020 which has led to production delays, the producer is facing disruptions within the plants caused by the weather conditions. “We are currently not able to foresee the full impact of these exceptional circumstances. We expect this to delay the normalization of the supply situation significantly.”
“As the only region in Germany we have not only been facing the complete stoppage of public railroad lines, but also the first-time ban on the transport of hazardous goods on public roads. The supply of materials that are necessary for our production is still not secure due to the interruption of supplies – for example of hydrogen.”
Thyssenkrupp said it would attempt to increase production by purchasing pre-materials, “despite the economic disadvantages this involves”.
In recent days, German steel deliveries have been hindered by blocked railway tracks and rising water levels on the Ruhr and Rhine rivers after Storm Darcy hit northern Germany Feb. 7.
Shipping was halted for a few days due to the water levels, but was able to resume Feb. 8 with all vessels loaded at just 50-60% capacity and buyers needing to pay extra for deliveries.
Thyssenkrupp has a crude steel capacity of 11 million mt/year. Salzgitter produced 6.6 million mt of crude steel in 2019.
— Amanda Flint, Laura Varriale
UK quota for other country rebar becomes critical
UK tariff rate quotas for the first quarter for rebar from other countries have reached a “critical” level, UK steel distributors’ association NASS informs Kallanish.
Q1 quotas for stainless wire rod from Taiwan and tinplate from China remain critical, as they were a week ago.
The quota used for other welded tube from Turkey has risen to 97%, for merchant bar and light sections from Turkey to 72%, and for gas pipes from Turkey to 60%.
Organic coated sheets from South Korea and category 4A metallic coated sheet from South Korea usage remains unchanged at above 60% from last week (see Kallanish passim).
The HMRC monitoring system is still experiencing delays in updating of around two working days.

Tribunal orders Taranto hot-end area closure
The Apulia regional tribunal has given ArcelorMittal Italia 60 days to shut down the hot-end area at the Taranto steelworks due to excessive carbon emissions, Kallanish learns from the tribunal’s ruling and sources at the company.
Explaining its decision, Tribunale Amministrativo Regionale (TAR) Puglia says emissions from the steelworks are “out of control” and present a danger to the lives of the citizens of Taranto.
“In relation to the ruling issued by the TAR of Puglia, ArcelorMittal Italia announces that it will immediately appeal to the Council of State against the closure of the hot area of the Taranto plant,” ArcelorMittal Italia says.
Local authorities and unions who have condemned the tribunal decision have asked Mario Draghi, the new Italian prime mister, for an urgent meeting with all parties in order to speed up the decision-making process.
Meanwhile, steel producers’ association Federacciai has expressed concern over the TAR ruling and says it hopes it will be suspended. “The fear is that such action could stop or slow down the relaunch of the steelworks,” says association president Alessandro Banzato. Environmental improvement works and production recovery are ongoing at the site, he adds.

Winter triggers force majeure in Germany
Temperatures below -20C and heavy snowfall mainly in northwest Germany have caused Salzgitter to declare force majeure to their customers, a company spokesman tells Kallanish.
“At the moment and until further notice, it is not possible to ship goods by rail or inland waterway,” the company writes in the communiqué. It notes that truck transports can still be handled, but depending on the route, carriers are increasingly struggling with closed, blocked or poorly passable roads, traffic jams, and other related impairments.
The mill has its own port to the Mittelland canal, which froze last week. That did not cause much of an issue because the waterway plays a lesser role than the railways, which have been subject to massive delays in recent days, the spokesman says.
Thyssenkrupp Steel states that its supplies have been throttled by the winter conditions as well, but that it has not declared force majeure. In addition to impairments for trucks and trains that have caused shortages, certain hazardous freights are banned from roads, meaning that, for example, oxygen and hydrogen cannot be transported as usual. Like Salzgitter, tk Steel had to scale down production because of the shortcomings, a group spokesman says.
Volkswagen: hydrogen belongs in steel, not cars
The chairman of Volkswagen says hydrogen belongs in heavy industry like steel – not personal vehicles, Kallanish learns from statements he made on Twitter.
Herbert Diess responded on the platform to a press release by the European Automobile Manufacturers’ Association calling for 1 million new charging stations by 2024.
“It’s time for politicians to accept science: Green hydrogen is needed for steel, chemical, aero…[sic] and should not end up in cars. Far too expensive, inefficient, slow and difficult to rollout and transport. After all: no #hydrogen cars in sight,” he writes.
A split appears to be emerging in the zero-emission sector between proponents of battery electric vehicles and those that rely on hydrogen fuel cells. A rough analogue can be made between batteries and hydrogen and gasoline and diesel fuel. Small, personal transports appear to be more efficient when powered by batteries, while heavy, long-range transports – buses, ships, and trucks – appear to be more efficient when powered by hydrogen.
Charging time is the big knock against battery vehicles; hydrogen vehicles could be fueled much as existing internal combustion vehicles are, via a retail station. However, proponents of battery vehicles point out that home charging is likely to be the norm and doesn’t require much in the way of new public infrastructure – though fast-charging stations will still need to be put in place.
Hydrogen is gaining increased acceptance in the steel sphere as a potential route to fossil-free production. SSAB is at the forefront of hydrogen-based steelmaking, with a pilot plant already in operation.
Berlin-based excess steel auction platform boosts transactions
Vanilla Steel, an e-auction platform for excess volumes of carbon and stainless steels, has more than doubled the monthly volume of transactions since its launch in October, and enlarged its base of suppliers.
While it has been more difficult to source steel within Europe, the platform lifted the volume handled from 3,400 tonnes in October to 8,700t in January. The surge was achieved amid an extremely volatile market, exacerbated by the difficulties in importing steel, the Berlin-based company notes.
“We are building a secondary market for the European steel ecosystem to help them trade
steel that is available for immediate sale more efficiently,” Kallanish hears from Vanilla Steel co-founder Alexis Ducros.
The platform offers a one-stop-shop for buyers, where they can go and find excess material across Europe. The number of European steel suppliers that have joined Vanilla Steel has now reached 50, Ducros notes.
Every Monday, new auctions are published on the platform. An order can be made in a few clicks and logistics services can additionally be booked directly. The platform was founded last summer as a market for excess capacities that have accrued during the Covid-19 pandemic (see Kallanish passim).
Severstal digital investments to raise 2021 production
Russian steelmaker and miner Severstal will increase finished steel production by carrying out new IT and digital projects in 2021, the company tells Kallanish.
Based on experience, an increase in productivity can be expected by more than 3% on-year to over 150,000 tonnes of additional rolled products at mill 2000 at its Cherepovets Steelworks (CherMK). This will also significantly accelerate the heating of slab in the sheet-rolling shop of the CherMK tube production.
“At the same time, we are still at the stage of developing a solution, so it is too early to talk about the exact effect,” the enterprise claims.
Total investment in more than 200 digital projects will amount to RUB 9.1 billion ($122.6 million) this year. The largest of them lie in the field of production, sales and logistics.
In 2020, significant progress was made in the areas of energy efficiency and production growth. Severstal implemented a solution based on artificial intelligence at continuous pickling unit No.3 of CherMK, which increased its productivity by more than 6.5% on-year.
In addition, a machine learning model for the automatic control of air compressors was successfully launched, which allows for more efficient use of electricity. Karelsky Okatysh is currently testing a model that will save energy at the roasting machines.
Severstal’s 2020 crude steel output and consolidated product sales each declined -4% on-year to 11.85 million tonnes and 11.2mt, respectively (see Kallanish passim). Revenue was down -15.8% on-year to $6.87 billion due to the Covid-19 pandemic impact.

LME scrap, rebar contracts gain on near-term physical market strength
Scrap, rebar futures contracts on the London Metal Exchange saw sharp gains over the week to Feb. 11, on expectations of a strengthening physical market in the near term.
Futures contracts for February-May gained on the week, with the scrap forward curve contango strengthening significantly on the week over February-March, before shifting into a slight backwardation over April-May. This might indicate futures trader expectations that the physical market price is likely to strengthen by the end of the first quarter before slightly softening during the second quarter.
S&P Global Platts assessed the February contract up $2/mt on the week at $417/mt on Feb. 11. The March contract gained by $24.50/mt over the week to $449.50/mt. The April contract increased $28/mt to $450.50/mt on the week and the May contract rose $22/mt on the week to $443.50/mt.
Spot prices for physical imports of premium heavy melting scrap 1/2 (80:20) increased $12.50/mt on the week to $410/mt CFR Turkey on Feb. 11, as Turkish mills returned to book cargoes at higher levels, after the index dropped to a near two-month low of $394/mt CFR on Feb. 5.
“The Turks don’t want the price to be much higher than $415-$420/mt CFR because they have to get higher prices for their finished steel later to cover it. They are allowing for scrap to go up now because they have sold well in the domestic market,” one trading source said.
“Even if scrap goes down at some point, it won’t go down a lot because there is incentive to buy in Europe and the US, so offers for Turkey will stay higher,” he added.
Weekly scrap futures trading volumes over the week to Feb. 11 totaled 53,090 mt, down from 78,480 mt recorded last week.
Rebar futures also saw gains on the week for February-May contracts, with the forward curve showing a significant contango over February-March contracts, before shifting into a slight backwardation over April-May contracts. This might indicate futures traders’ expectations that the physical market might strengthen by the end of the first quarter.
Platts assessed the February contract up $4/mt on the week at $598.50/mt on Feb. 11, while the March contract saw gains of $28/mt on the week at $620.50/mt. The April rebar contract increased $18/mt to $620.50/mt on the week, and the May contract rose $16/mt to $615.50/mt over the week.
The Turkish physical rebar export market saw a significant gain in prices as sources reported multiple sales to Israel, Yemen, African destinations as well as position cargoes booked by trading sources. The Platts assessment of Turkish exported rebar increased $12.50/mt on the week to $597.50/mt FOB Turkey on Feb. 11.
One Turkish trader said that Chinese traders expect positive movement in the market once the Lunar New Year holidays are over. Although Turkish market participants reported low demand from Southeast Asia given the holiday period, market participants saw some demand from Africa, he added.
“Perhaps next week we’ll see Turkish mills starting to sell for April shipment,” he said.
Rebar futures’ weekly trading volume this week on the London Metal Exchange totaled 9,070 mt, lower than 11,220 mt recorded last week.
The outright spread between Turkish exported rebar and import scrap was stable on the week at $187.50/mt on Feb. 11.
— Rabia Arif