


Italian rebar prices gain traction
Italian rebar prices are beginning to rise following an increase attempt by domestic steelmakers in mid-October.
This week, mills are quoting at around €270/tonne ($314/t) base ex-works, with no offers accepted at below €260/t. One producer says that further increases may be introduced in November.
Some material shortages are being reported as certain steelmakers have not been operating at full capacity in recent weeks. While many buyers continue to adopt a wait-and-see approach, one tells Kallanish he is purchasing small volumes at €260/t base ex-works, adding that he doubts the sustainability of the current price increases.
A construction company notes that activity has slowed compared with June and July, though projects are still ongoing. A distributor reports some demand for rebar and mesh this month. Meanwhile, several French distributors in the south are complaining about a strong Italian presence, with material being offered at lower prices than domestic suppliers.
Recent domestic transactions are reported at around €250-260/t base. Including size extras of €260-270/t, effective prices are in the range of €520-530/t ex-works. Mesh prices are also trending upwards, averaging at €250-260/t base ex-works, excluding an additional €300/t in size extras.
Natalia Capra France


European HRC prices climb gradually; buying slow
Deals for January delivery have not been numerous yet in Northern Europe, as some mills have not been active in offers. But some volumes were heard booked at €610 ($710) per tonne ex-works, in line with earlier voiced expectations versus mills’ bullish targets of €620-650 per tonne ex-works.
Nevertheless, €610 per tonne ex-works is still a progress from the level of €580-590 per tonne ex-works which was widely seen in deals for December-delivery material.
Market participants expected the next several weeks to be quiet with customers still digesting price rises and upcoming changes in protection measures, with buying activity expected to pick up by December.
Additionally, information came to light about a fire halting production at thyssenkrupp’s hot strip mill in Duisburg, Germany, late on Friday October 24. The market is still assessing the effect of the accident.
Fastmarkets’ daily steel hot-rolled coil index domestic, exw Northern Europe was €602 per tonne on October 27, up slightly from €600.88 per tonne on October 24.
The index was up by €10.54 per tonne week on week and by €24.29 per tonne month on month.
In Italy, the situation with December-delivery coils was quite similar to Northern Europe, with January volumes not widely available yet, according to sources.
Current workable levels were heard at €575-585 per tonne ex-works, versus offers at €600-610 per tonne ex-works.
Fastmarkets’ corresponding daily steel hot-rolled coil index domestic, exw Italy was calculated at €591.25 per tonne on Monday, up from €590 per tonne on October 24.
The Italian index was up by €6.25 per tonne week on week and by €40.62 per tonne month on month.
After last week’s information about a booking of 40,000 tonnes of Indonesian HRC at €465-470 per tonne CFR with delivery in 2026 and a buyer covering all costs, several market sources reported news about the possible inclusion of Indonesia in safeguards as early as January 2026. No official document confirming this was seen by Fastmarkets.


Daimler Truck, HHLA, and Kawasaki launch collaboration to develop a liquid hydrogen supply network in Europe
Daimler Truck, Hamburger Hafen und Logistik AG (HHLA), and Kawasaki Heavy Industries have launched a strategic partnership to establish a green liquid hydrogen supply chain in Europe. The system, which will extend from the Port of Hamburg to inland regions of the continent, aims to accelerate the use of hydrogen in logistics and industrial applications.
At the Hydrogen Technology World Expo in Hamburg, Daimler Truck, Hamburger Hafen und Logistik AG (HHLA), and Kawasaki Heavy Industries signed a Memorandum of Understanding (MoU) to develop a safe and cost-efficient supply chain for green liquid hydrogen. The project will enable imports of liquid hydrogen from producing countries to Germany and strengthen Hamburg’s position as Europe’s leading hub for sustainable energy logistics.
Under the joint initiative, the partners will assess the logistics infrastructure for transporting liquid hydrogen via road and rail through Hamburg in the coming months. The plan also includes establishing an international hydrogen consortium covering the entire supply chain.
Dr. Andreas Gorbach, Member of the Board of Management at Daimler Truck, emphasized hydrogen’s key role in Europe’s energy transition: “Our Mercedes-Benz GenH2 trucks not only run on liquid green hydrogen but can also transport it. This technology is key to accelerating decarbonization and overcoming the limitations caused by the slow expansion of the energy grid.”
Annette Walter, Chief Financial Officer at HHLA, highlighted hydrogen’s flexibility in transport and logistics: “Liquid hydrogen offers major advantages for SMEs and industries because it can be transported independently of pipeline infrastructure. Our goal is to ensure a reliable hydrogen supply to industry through our pan-European logistics network.”
Kei Nomura, Head of Hydrogen Strategy at Kawasaki Heavy Industries, noted the company’s long-standing expertise: “Kawasaki has been developing technologies for the production, storage, and transportation of liquid hydrogen for many years. Our collaboration with HHLA and Daimler Truck marks a significant step toward building an integrated hydrogen supply network in Europe.”
Experts say this partnership sends a strong signal for Europe’s energy transition. Kawasaki is developing tanker vessels of various capacities capable of transporting liquid hydrogen, while HHLA aims to expand the use of fuel cell technologies in port operations as part of its goal to achieve a carbon-neutral logistics network by 2040. Daimler Truck, pursuing both battery-electric and hydrogen-based strategies, plans to start small-scale hydrogen truck production by 2026 and move toward full-scale series production in the 2030s.


EU should advance competitiveness, close trade loopholes
Market participants have called for the promotion of a competitive industry, a support system to make financing the energy transition feasible, and the closing of loopholes that allow the entry of products from third countries which creates unfair competition.
The comments were made at the recent “Forging the future: key factors for a competitive EU steel industry” conference.
All these challenges come within a framework of enormous difficulties, such as reaching agreements within the EU amid the multiple interests of its member countries, steel industry representatives noted during a seminar held in Avilés last week by the Commission for Economic Policy under the European Committee of the Regions (CoR).
According to the executive director of ArcelorMittal Spain, Philippe Meyran, EU policy must be more engaged in promoting the consumption of low-emission steel. Maintaining a strong steel industry is essential for developed economies and social welfare.
“We have to tackle Europe’s problems by tackling the problems of the steel industry,” Meyran commented at the event monitored by Kallanish. “Companies must be profitable, but we have problems, such as with dumping from third countries, CO2 emissions taxes that account for 25% of costs, the energy price and the high level of wages compared to other non-EU producers.”
The executive explained that the sector must have a level playing field across Europe, with sufficient electricity generation at an acceptable cost to achieve decarbonisation goals, and a sufficient electricity transmission grid.
His point of view was supported by German MEP Isolde Ries, who warned of the risk of a legal gap that allows Chinese products to enter the EU via Turkey.
“We need real protectionist measures, abundant energy at affordable prices and solidarity,” she remarked.
“Europe needs a decarbonised steel sector and must promote low-emission products, while raising awareness among society to consume them, even if this means paying a little more,” she concluded.
The European Commission is considering including the steel processing industry, in particular the metalworking sector, into its new protection plan. Alberto Cirio, president of the Commission for Economic Affairs, explained that the CoR is in the final stages of drafting its report on the action plan, and the conclusions drawn from it will be very important for the Commission’s final decision.

Todor Kirkov Bulgaria
Overcapacity, protectionism impact European steel
Overcapacity and protectionist measures are exacerbating pressure on the European steel industry, Kallanish heard at the Steel Tech 2025 conference in Bilbao last week.
In recent years, China, along with Southeast Asia and North Africa, has significantly increased its installed capacity, while no answer has been found on how to contain the new volume within the countries where it is generated.
“The sector is witnessing a global increase in trade protectionism measures. Furthermore, the constant increase in capacity in certain regions and increasingly aggressive export behaviour are having an impact on the trading environment,” Enrique Arrieta, European Commission policy officer for trade and economic security, said at the event.
Currently, countries such as the United States, Canada, Mexico, Colombia, the United Kingdom, Turkey, India and Egypt have adopted protective measures to safeguard their markets. China is meanwhile attaining export records every year, resulting in the disruption of traditional markets.
One of the most illustrative cases is Vietnam, which in the last eight years has doubled its installed capacity from around 15 million tonnes/year to almost 30mt. “The problem arises because, given China’s aggressive export behaviour, the Asian country is not only flooding the Vietnamese market, but also displacing Vietnam from its traditional export destinations, such as Thailand or the United Arab Emirates,” the expert explained.
As a result, Vietnamese steel exports to the EU have increased by 70% since the pandemic, making the country the fourth largest steel supplier to Europe, a shift that occurred “very quickly”, according to the official.
A similar phenomenon can be observed in Japan, which, despite not having increased capacity in recent years, has redirected volumes to Europe after losing influence in key markets such as Indonesia, South Korea and Thailand, which are now dominated by Chinese steel. Japan went from exporting marginal quantities to the EU to shipping close to 2mt between 2023 and 2024.
“These trends are occurring while the EU maintains a quota-based system of safeguards, which limits its capacity to respond. The combination of third-country protectionism and the effects of global overcapacity are creating a very unsustainable situation for Europe,” Arrieta said. “Ideally, the problem of overcapacity should be addressed globally. But as the past has shown, this has not been possible. If overcapacity is not discussed, it is very difficult to attack its causes without punishing those who create the problem.”
The European Commission is open to the possibility of reopening the debate on overcapacity, intending to seek a global solution that reinforces the protection of European industries while minimising the impact on international supply chains, Arrieta confirmed.
Todor Kirkov Bulgaria

Blechexpo: Plate prices seen increasing, demand improves
Plate sellers are expecting price increases in the first quarter of 2026 to be driven by a sharp decline in imports into Europe and ongoing infrastructure projects, sources at last week’s Blechexpo trade fair in Stuttgart told Kallanish.
For S275 material, sources expect prices to reach around €700/tonne ($819/t) ex-works for southern Europe and €30-40/t more for northern Europe, where prices remain slightly higher.
Demand is described as improving, with producers’ lead times currently extending into December. European plate mills are seeking to restore profitability, as margins have been under sustained pressure in recent months.
One seller at the trade show noted that achieving Ebitda margins of around 7-8% would be “at least acceptable”, adding that “we’re not asking for the moon”.
Demand for plate in northwestern Europe did not see a substantial revival after the summer break but it is said to be improving in October. Prices in northern European countries are hovering between €650-670/t ex-works, while in Italy, producers are asking for €650/t for S275 material, with current transactions between €630-630/t ex-works.
Another producer said plate sales are now strong after a period of uncertainty. “We will close the year well and rebalance our finances in the fourth quarter,” he commented.
Market sources downstream, however, remain cautious, emphasising that any price increases should be moderate and implemented gradually to allow customers time to adapt.
Natalia Capra France

EU Steel Distribution: Confidence slips slightly, but activity stabilises
The latest EUROMETAL Market Sentiment Survey for October 2025 shows a mixed picture for Europe’s steel distribution sector. While current activity appears to have stabilised, forward-looking indicators suggest that confidence in a recovery remains fragile.
After September’s tentative signs of improvement, October’s results show a sector still cautious, with no strong upward momentum and a wait-and-see approach dominating behaviour.
Current activity remains stable
The assessment of current activity remained stable in October, holding at similar levels to September. While still modestly negative and below the neutral line, this marks the second consecutive month without further deterioration — a potential sign that the market may have found its floor after the sharp summer downturn.
Near-term outlook softens again
Expectations for activity in the next quarter declined slightly in October, reversing part of the cautious optimism seen in September. While not a dramatic shift, the trend reflects ongoing uncertainty and weak demand fundamentals heading into Q4.
Inventory strategies unchanged
The stock volume outlook remains consistent with previous months. Distributors are largely maintaining defensive inventory strategies, with most respondents expecting stock levels to remain stable in the near term. This cautious approach signals continued risk aversion across the sector.
Price expectations continue upward trend
October marks the third consecutive month of rising price expectations among European steel distributors. Following the dip in Q2, sentiment has steadily improved, and October shows the strongest positive outlook since early spring.
While price sentiment is not yet decisively bullish, the trend indicates that more respondents are beginning to expect moderate price increases in the coming months. This shift may reflect signs of tightening supply, stabilised demand, or anticipation of restocking cycles in Q4.
Key Takeaway
While there are early signs of improvement in price sentiment, the October 2025 data continue to reflect a market constrained by weak demand and low visibility. Current activity has stabilised, and inventories remain steady — both indicators of a sector in a holding pattern.
However, the continuation of upward price expectations is notable and could signal the beginning of a more positive trend — if demand fundamentals start to improve. Until then, caution remains the dominant mood across Europe’s steel distribution sector.
This analysis is based on the EUROMETAL Market Sentiment Survey, reflecting the views of 214 industry participants for October 2025.

Interested in our Sentiment Tool? Contact us.
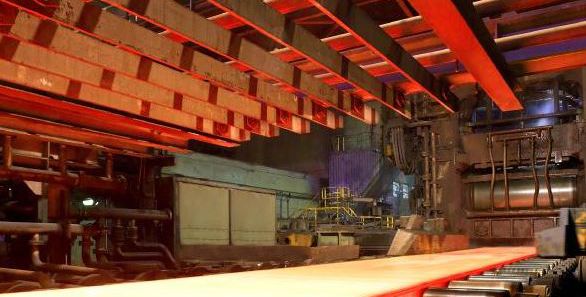
Fire at thyssenkrupp Steel in Duisburg in the Bruckhausen plant area
A fire broke out on the evening of October 24, 2025, at the hot strip mill of thyssenkrupp Steel’s Bruckhausen plant in Duisburg, Germany.
The incident occurred around 10:15 p.m. and was quickly brought under control by the plant’s emergency services, supported by the professional fire department of Duisburg.
No injuries were reported, and the NINA warning app has since issued an official all-clear.
The fire occurred in a facility that produces flat steel for critical downstream applications, including the automotive sector. As one of Europe’s largest flat steel manufacturers, thyssenkrupp Steel’s Duisburg site employs nearly 13,000 people, with an additional 500 trainees.
Authorities have been kept informed, and no broader disruptions have been announced as of now.
Source: thyssenkrupp-steel.com

Metinvest confirms initial interest in acquiring idled Liberty Galati steel plant
Metinvest has confirmed a preliminary interest in Romania’s 3 million mt/year integrated iron and steel works Liberty Galati.
The Ukrainian mining and steel company confirmed to Platts, part of S&P Global Commodity Insights, it is examining the feasibility of such an acquisition and the potential synergies with its business, but added it has not yet put in a bid.
Given the Romanian state’s exposure to around Eur400 million of Liberty Galati’s cumulative debt, in mid-September the government set up the Committee for Protecting the State Interests at the Galați steel plant, according to its website.
The committee has been investigating a loan granted to the producer for the restart of its blast furnace No. 5, which came online earlier this year, but for a short period only. It has also been assessing the intentions of potential investors interested in acquiring or supporting the production activities of the steelmaking asset.
It did not specify those companies or persons, but local media mentioned Dorinel Umbrarescu, the owner of Romanian construction group UMB, as another candidate.
The state’s interest is to maintain the domestic steel industry functioning because the entire construction sector in Romania relies heavily on metal production, and also because Romania will have additional gas production from 2027, and so it would be illogical not to produce key metal components domestically, Prime Minister Ilie Bolojan said during his last month’s press conference.
In September, the plant’s administration notified the unions that technical unemployment would continue through October, with prospects for production to resume being slim, according to the Romanian government’s website.
The restructuring plan for Liberty Galati, approved by creditors and confirmed by the Galati Court in August 2025, is meant to help the steel mill avoid insolvency and implies securing the financing, and collaboration with potential investors.


Blechexpo: EU CRC market braced for strong impact from new trade regime, anti-dumping investigation
Stakeholders said that new trade policies and and a pending anti-dumping investigation into CRC imports were driving positive market expectations for 2026, even though they acknowledged that real demand is not expected to grow.
On September 18, the European Commission initiated an anti-dumping (AD) investigation targeting CRC originating in India, Japan, Taiwan, Turkey and Vietnam. The probe affects more than half of all EU CRC imports.
In 2024, those five countries accounted for 65.2% (1.9 million tonnes) of the total 3 million tonnes of CRC sold into the EU.
“In our opinion, if there were to be a shortage of material next year, it will be cold-rolled coil,” a German buyer told Fastmarkets on the sidelines at Blechexpo.
CRC prices in Northern Europe have moved slightly higher in mid-October, prompted by positive views among sellers after the new EU regime for 2026 was announced on October 7.
The German buyer source said that domestic mills were “not interested in selling big volumes of cold rolled coil, at least for commodity steel grades”, adding that suppliers preferred to use CRC to produce galvanized material.
“Producing CRC is expensive in Europe. And [CRC] has been import-dominated for years,” a second German buyer said.
Sources said that most EU mills use the batch annealing process to make CRC, which is very energy-intensive.
And only three suppliers could make CRC via continuous annealing, which is more energy-efficient, sources said
While trade restrictions and lower imports were seen as supportive factors for the market, weak end-user demand – particularly from key sectors such as automotive – is expected to offset much of that positive impact, sources said.
“We don’t expect our business with the automotive sector to grow,” a third German buyer said.
Buyers also questioned the sustainability of any potential price increases, given the low levels of demand.
According to a report published by the European Association of Automotive Suppliers (CLEPA) in March 2025, almost half do not expect to be profitable in 2025.
And a Benelux-based seller said that domestic prices CRC were unlikely to “shoot up” because of potential product shortages caused by the new import measures.
According to the seller, there is an “underestimation” of the ability for local mills to “fill the gap” left in the market by lower import volumes.
“There is a big part [of CRC] that is used to produce very basic quality value galvanized coil, which we won’t need to do if the price of CRC increases,” the seller said. “It depends on the balance that you make.”
Fastmarkets’ weekly price assessment for steel cold-rolled coil domestic, exw Northern Europe was €670-690 per tonne on Wednesday, compared to €660-670 per tonne the previous week.
For January delivery, local suppliers told Fastmarkets they were looking to get €730-750 per tonne ex-works for CRC.